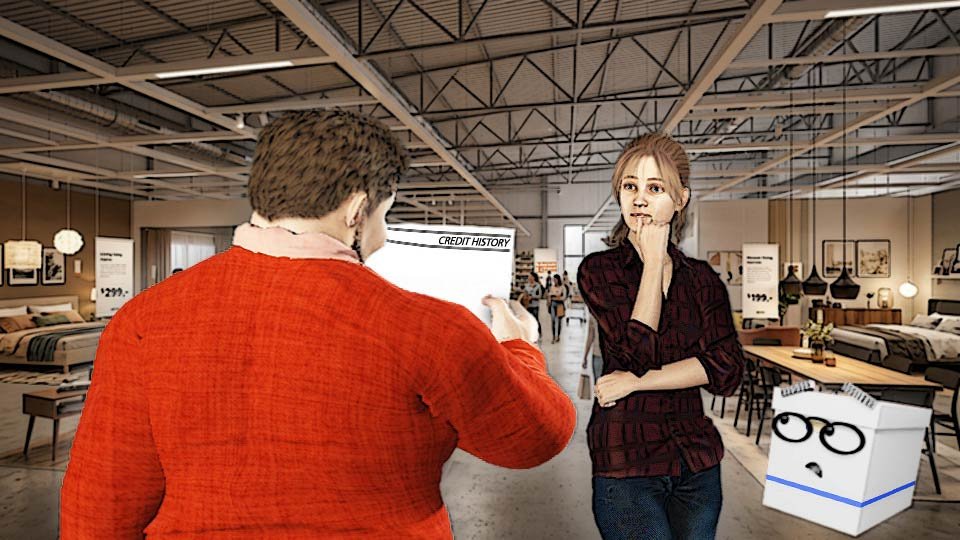
Alexa stood in a furniture superstore, picking out her first real couch, feeling genuinely like an adult for possibly the first time in her life. Then the salesman pulled up the financing application, watched her credit page load in front of him, and watched it stay completely, perfectly blank.
He looked at it. He looked at her.
“And, we’re paying in cash today?” he asked, in the tone of a man recalculating his entire afternoon.
She was not, in fact, planning on paying cash today.
She spent the drive home trying to figure out whether “no credit” was the same problem as “bad credit,” since both seemed to produce the exact same polite, faintly pitying rejection.
❓ Wait, Why Does This Even Matter?
Here’s the part nobody explains before you’re standing in a showroom getting quietly judged by a salesman: a credit score isn’t really about whether you’re a good person, or even whether you’re good with money in any broad sense.
It’s a lender’s best guess at one specific question — if they hand you money, how likely are you to pay it back. That number then follows you into a surprising number of rooms that have nothing to do with loans at all.
- Buying a car, obviously.
- But also renting an apartment — plenty of landlords pull a credit check before they’ll hand you keys.
- Getting a cell phone plan without a hefty deposit.
- Financing that couch, or a laptop, or literally anything at a checkout counter that offers “pay over time.”
- In some states, even your car insurance premium.
- Eventually, a mortgage, where a good score can genuinely save you tens of thousands of dollars in interest over the life of the loan.
None of these institutions knows you personally. The score is the introduction they’re working from instead.
An empty credit file doesn’t say “this person is risky.” It says “we have literally no information to work with,” which, to a nervous lender, ends up looking almost the same in practice. The fix isn’t proving you’re trustworthy through sheer force of personality. It’s giving the file something to actually say.
⚖️ No Credit Is Not the Same as Bad Credit
Bad credit means a history of missed payments or other negative marks — a track record, just not a good one.
No credit means there’s no track record at all yet, positive or negative. Lenders treat them similarly in practice, since both look risky from their side, but for completely different reasons.
Bad credit needs repair, which takes real time and real discipline to undo.
No credit just needs a starting point, which is a much easier problem to solve — you’re not fixing a mistake, you’re just making a first entry.
🔒 Starting Point One: A Secured Credit Card
Covered in its own post, but worth repeating here as step one: a secured card reports to the credit bureaus exactly like a regular card does.
It’s specifically designed for people in exactly Alexa’s situation — you put down a deposit that becomes your credit limit, use the card normally, and the on-time payments start building a file where there wasn’t one before.
👥 Starting Point Two: Becoming an Authorized User
If a parent or someone else you genuinely trust has a credit card in good standing, they can add you as an authorized user.
Their account’s positive history can then start showing up on your credit report too, even though you’re not the one primarily responsible for the bill.
It’s a genuinely fast way to build some initial history — provided the primary cardholder’s habits are actually good ones. Being added to someone’s account who pays late or carries a huge balance doesn’t help you. It just hands you their problem with your name attached to it.
💳 Starting Point Three: A Credit-Builder Loan
Some banks and credit unions offer a loan specifically designed for this exact purpose. You “borrow” a small amount that actually sits in a locked savings account the entire time. You make fixed payments on it. The money gets released to you once it’s fully paid off.
The payments themselves report to the credit bureaus the whole way through, building history through a process that’s about as low-risk as borrowing gets, since you’re essentially paying yourself back with extra steps and a paper trail.
🧾 What Actually Matters Once You Have Any Credit at All
On-time payments, every single time, without exception — this is the single biggest factor in the whole system.
Keeping your utilization low, meaning you’re not maxing out whatever limit you’ve got. Owing, say, $4,800 on a credit card with a $5,000 limit is considered very high utilization. Owing, say, $400 on the same card would be low utilization.
And simply letting time pass. Length of credit history is a real, weighted factor in the formula, and there’s no shortcut around it except starting as early as reasonably makes sense, which is exactly what Alexa is doing now, slightly later than she’d have liked, in a furniture store parking lot.
⏳ How Long This Actually Takes
A usable, decent score can build within about six months to a year of responsible activity. A genuinely strong score takes longer than that, since length of history is baked directly into the formula and can’t be rushed no matter how perfectly you behave. There’s no legitimate fast track, no trick, no secret cheat code a finance influencer is hiding from you.
Just a first step, taken as early as it reasonably can be — which, as it happens, is available to Alexa the moment she leaves that showroom.
🔗 Related Reads
- Secured vs. Unsecured Credit Cards: Which One You Actually Need
- What a Credit Score Actually Measures
- Applying for Your First Credit Card: What Actually Matters
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
52001
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
3 thoughts on “Building Credit From Zero: The Actual First Steps”