What a Credit Score Actually Measures

A credit score sounds like a mysterious verdict handed down from on high. It’s really just a report card for one very specific behavior.

Marty has heard the phrase “good credit score” roughly a thousand times in his life, has a general sense that a higher number is better, and could not, if put on the spot, explain what a credit score is actually measuring — good at what, exactly? Being a nice person? Showing up on time? He genuinely didn’t know.

🎯 What It’s Actually Measuring: One Thing

A credit score is a three-digit number, typically ranging from 300 to 850, that predicts one specific thing: how likely you are to repay borrowed money on time, based entirely on your past history of borrowing and repaying.

It’s not a measure of income, net worth, intelligence, or general trustworthiness as a human being — purely and only a track record of debt behavior.

🧮 The Five Ingredients, and Roughly How Much Each One Weighs

Your credit score is determined by these five factors:

  • Payment history (do you pay on time) is the single biggest factor, roughly 35% of the score.
  • Credit utilization (how much of your available credit you’re actually using, covered in its own post) is next, around 30%.
  • Length of credit history — how long you’ve had credit accounts open — makes up about 15%.
  • The mix of credit types you have (credit cards, loans, etc.) contributes about 10%.
  • And new credit inquiries — how often you’ve recently applied for new credit — rounds out the last 10%.

📊 What the Actual Ranges Mean

Roughly speaking, these are the credit range rankings:

  • 800-850 is considered exceptional
  • 740-799 very good
  • 670-739 good
  • 580-669 fair
  • below 580 poor

Lenders use these ranges to decide not just whether to approve you, but what interest rate to actually offer — a real, dollars-and-cents difference, not just a bragging-rights number.

🎢 Interest Rates: The Price of Being a Mystery

Here’s the part that last section undersells: that number doesn’t just decide whether you get approved. It decides how much the approval actually costs you.

Every loan and card comes with an interest rate attached — basically a rental fee for borrowing someone else’s money. Lenders don’t hand that fee out equally. A high score says “this person pays reliably, historically, boringly” and earns a better rate. A low score, or no score at all, says “no idea, never met this person” — and lenders protect themselves from that uncertainty the only way they know how: by charging more, just in case.

The gap adds up fast, too. Same car, same dealership, same day: the guy with a low credit score might be looking at $785 a month, while the guy with excellent credit drives off in the identical car for as little as $550. Same loan. Different mystery level. Different price tag every single month for the next five years.

So the number isn’t a report card. It’s a discount code, earned one on-time payment at a time — and the alternative is paying full price for being a stranger.

👻 The Myth Worth Killing Immediately

Checking your own credit score does not lower it.

This is one of the most persistent, wrong beliefs out there, and it keeps people from looking at a number that genuinely affects their financial life.

Checking your own score is called a “soft inquiry” and has zero impact — it’s only when a lender checks your credit as part of an actual application (a “hard inquiry”) that it can cause a small, temporary dip.

🆓 How to Actually Check It, for Free

Many credit card companies and banks now offer free credit score access right inside their app.

Sites like AnnualCreditReport.com provide free access to your full credit report (a different, more detailed document than just the score) once a year from each of the three major bureaus.

There’s no good reason to pay a monthly fee just to see a number you’re entitled to check for free.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Secured vs. Unsecured Credit Cards: Which One You Actually Need

One of these cards asks for a deposit before it trusts you with credit. That’s not a punishment — it’s actually a smart starting move.

Alexa applied for a regular credit card, got denied for having “insufficient credit history,” and felt the specific, circular frustration of being told she needed credit history to get credit, with no apparent door leading in. There’s a door. It’s just a slightly different one than she was knocking on.

🛋️ Secured vs. Unsecured: What’s the Difference?

Picture two strangers who show up at your door on the same afternoon, both wanting to borrow $300, both with an honest face and a suspiciously specific repayment plan.

The first guy hands you a driver’s license, shakes your hand, and promises to pay you back $27.50 a month for the next twelve months — $330 total, meaning you walk away $30 richer for helping him out. Nice guy. You believe him. You have, however, no actual leverage beyond his word and a mild sense that he seemed trustworthy.

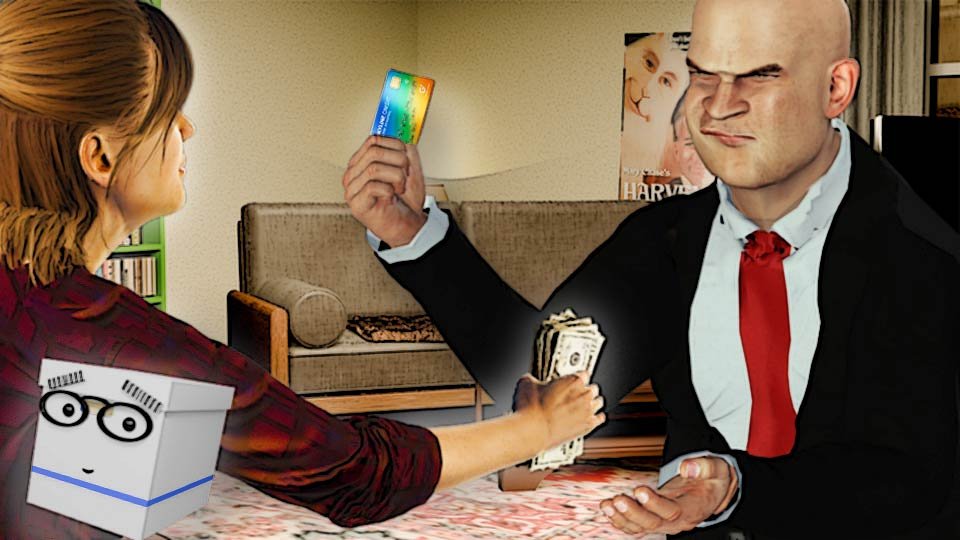
The second guy wants to buy your couch, also for $300, and offers the exact same deal — $27.50 a month for a year. Except he takes the couch home with him today, right now, sofa cushions and all, on nothing but that same promise to pay.

Here’s the entire difference in one sentence: if guy number two stops paying, you know exactly where your couch is, and you’re legally entitled to go get it back. If guy number one stops paying, you’ve got a phone number, a memory of a firm handshake, and absolutely nothing else.

That’s secured versus unsecured credit in a nutshell. A secured line is backed by real, repossessable property — the couch, a car, a house. An unsecured line is backed by nothing but your word that you’ll pay it back, which is exactly why lenders charge more interest for it and check your credit history more carefully before handing it over. Collateral isn’t a technicality. It’s the entire reason one of these guys sleeps easier than the other.

🔓 Unsecured: The “Normal” Credit Card

An unsecured credit card is what most people picture when they think of a “credit card” — no deposit required, the credit limit is based purely on the bank’s assessment of your creditworthiness.

The catch: banks and credit card companies typically require an existing credit history before they’ll approve you for one in the first place — which is exactly the wall Alexa ran into.

The second catch: because they’re lending you money on nothing but your word, banks and credit card companies usually charge a higher interest rate on that line of credit than they would on a secured one.

🔒 Secured: The Same Card, With a Deposit Attached

A secured credit card requires a refundable security deposit upfront — commonly matching your credit limit, so a $300 deposit gets you a $300 limit.

That deposit is the bank’s insurance policy against someone with no track record yet — not a punishment, just how a bank manages risk with an unknown quantity.

It’s the same idea as the couch. If you don’t pay, the bank keeps your $300 — the equivalent of you collecting the couch.

🪜 Why Secured Cards Are Genuinely the Smart Starting Move

A secured card reports to the credit bureaus exactly the same way an unsecured one does — on-time payments build real credit history either way.

It’s specifically designed as a stepping stone: use it responsibly for a while, and many issuers will actually convert it to an unsecured card automatically, refunding your original deposit once they do.

The downside: you have to come up with $300 first.

Now, you’re not paying a $300 fee that just vanishes. You’ll get that money back eventually, and in the meantime it’s sitting there as your actual credit limit, doing its job.

And it’s available to you on your new credit card – you’ll most likely have at least a $300 credit limit. Use the card to buy your groceries and stuff, just paying off the card at the end of the month.

But you do need to have that $300 up front.

💵 What Happens to the Deposit

As long as the account stays in good standing, the deposit isn’t a fee — it’s held, and returned to you either when the card converts to unsecured or when you close the account with no outstanding balance.

It’s genuinely your money the entire time, just serving as collateral rather than sitting in a regular savings account.

🎯 The Actual Decision

If you have zero credit history, a secured card is very often the realistic starting point, not a lesser option — plenty of people with excellent credit today started on exactly this kind of card.

If you already have some credit history through another route (a co-signed account, a student loan, being an authorized user on a parent’s card), you may already qualify for unsecured directly.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Filling Out Your First Credit Card Application: What They’re Actually Asking

Applying for a first credit card feels like it should come with an instruction manual. It doesn’t, so here’s one.

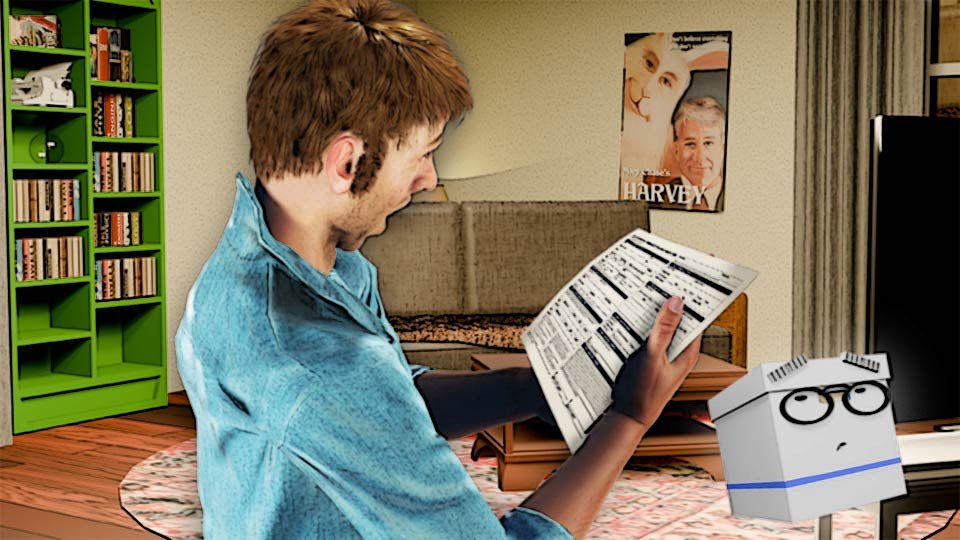
Marty sat down with an actual paper application, pencil in hand, and stared at Section 2: Financial Details like it had just asked him to disclose state secrets. Annual income. Employer. Years employed. Monthly rent.

It felt like the kind of form you’d need a briefcase full of documents to complete.

He did not own a briefcase. He owned a pencil and a mounting sense of dread. Neither turned out to be necessary, though the pencil helped.

🪪 Applicant Information — What It Actually Wants

Name, address, phone number, date of birth, and your Social Security number. That last one is usually the part that makes people pause, hovering the pencil, wondering if handing it over on a form is a mistake.

It isn’t.

The credit card company, called “the issuer,” needs it for two specific reasons: confirming you’re actually who you say you are, and pulling your credit report.

That credit repor is the whole reason this section exists at all. Without it, they have no file to check and nothing to approve you against.

💵 Financial Details — The Question That Feels Like a Trap

Annual income, employer name, how long you’ve worked there, and your monthly rent or mortgage payment.

This is the section that makes an application feel like an audit, but it’s really just one calculation in disguise: how much money is coming in, versus how much is already going out.

That ratio is called debt-to-income, and it’s the main thing an issuer uses to decide both whether to approve you and what starting credit limit makes sense. It’s not a judgment on your life choices. It’s just math they need before they hand you a number.

📄 Do You Need Your Tax Returns for This?

No — and this is worth saying plainly, because it’s the exact thing that makes people freeze up before they’ve even started.

For a standard personal credit card, income is self-reported. You write the number down.

You don’t attach a W-2, a pay stub, or a tax return to prove it.

The issuer may occasionally verify income after approval, especially for a high limit (a card that has, maybe, $5,000 or more available), but that’s the exception, not the standard process.

Marty didn’t need a briefcase. He needed the number, from memory, and honesty.

🔁 Balance Transfer Options — You Can Skip This One

This section asks about moving an existing balance from another credit card onto this new one, usually to take advantage of a lower promotional interest rate on the new card.

If this is genuinely your first credit card, you don’t have an existing balance anywhere to transfer. Leave the whole box blank and just move on. It isn’t relevant to you yet, and nothing about your application suffers for skipping it.

🎨 Card Design Preferences — The Only Part With No Wrong Answer

Which design you want the physical card to look like.

That’s it.

No financial mechanics hiding underneath this one, no calculation, no consequence. This is the one section on the entire form where Marty could relax, and possibly the only part of the whole process anyone designed to actually be fun.

✍️ Signature and Consent — What You’re Actually Agreeing To

Signing authorizes two things: that the information you provided is accurate, and that the issuer can pull your credit report to make a decision.

That credit pull is called a hard inquiry. For most applicants, it causes a small, temporary dip in an existing score, although you won’t — but have an existing score to dip.

With no credit history yet, this inquiry isn’t shaving points off anything. It’s the first entry in a file that’s currently empty, the actual starting gun on the score he doesn’t have yet.

Either way, it’s a completely normal, expected part of applying for any credit, not a red flag or a mistake. Signing isn’t the scary part of the form. It’s just the part where you confirm everything above it was true.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52006

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Building Credit From Zero: The Actual First Steps

No credit history isn’t bad credit — it’s just an empty file. Here’s why that empty file matters, and how to actually start filling it in.

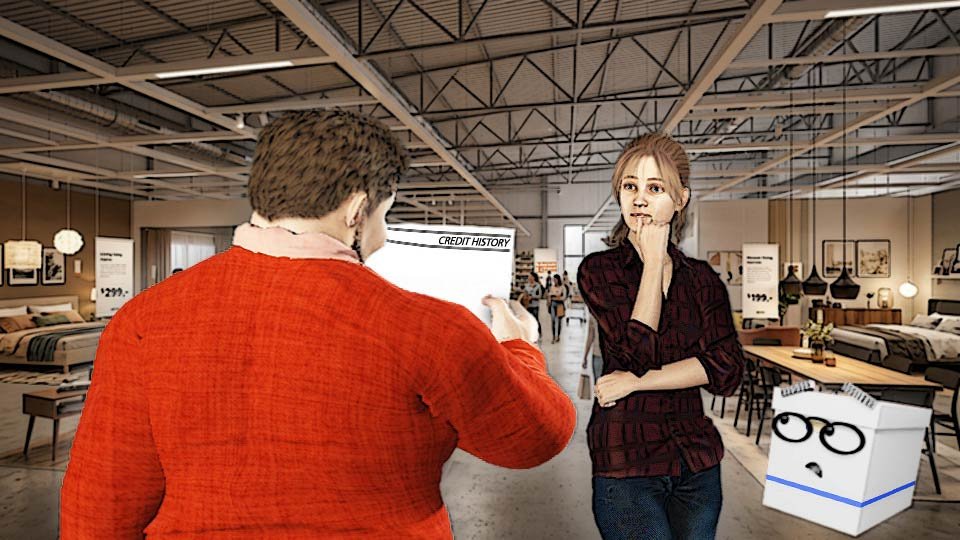
Alexa stood in a furniture superstore, picking out her first real couch, feeling genuinely like an adult for possibly the first time in her life. Then the salesman pulled up the financing application, watched her credit page load in front of him, and watched it stay completely, perfectly blank.

He looked at it. He looked at her.

“And, we’re paying in cash today?” he asked, in the tone of a man recalculating his entire afternoon.

She was not, in fact, planning on paying cash today.

She spent the drive home trying to figure out whether “no credit” was the same problem as “bad credit,” since both seemed to produce the exact same polite, faintly pitying rejection.

❓ Wait, Why Does This Even Matter?

Here’s the part nobody explains before you’re standing in a showroom getting quietly judged by a salesman: a credit score isn’t really about whether you’re a good person, or even whether you’re good with money in any broad sense.

It’s a lender’s best guess at one specific question — if they hand you money, how likely are you to pay it back. That number then follows you into a surprising number of rooms that have nothing to do with loans at all.

  • Buying a car, obviously.
  • But also renting an apartment — plenty of landlords pull a credit check before they’ll hand you keys.
  • Getting a cell phone plan without a hefty deposit.
  • Financing that couch, or a laptop, or literally anything at a checkout counter that offers “pay over time.”
  • In some states, even your car insurance premium.
  • Eventually, a mortgage, where a good score can genuinely save you tens of thousands of dollars in interest over the life of the loan.

None of these institutions knows you personally. The score is the introduction they’re working from instead.

An empty credit file doesn’t say “this person is risky.” It says “we have literally no information to work with,” which, to a nervous lender, ends up looking almost the same in practice. The fix isn’t proving you’re trustworthy through sheer force of personality. It’s giving the file something to actually say.

⚖️ No Credit Is Not the Same as Bad Credit

Bad credit means a history of missed payments or other negative marks — a track record, just not a good one.

No credit means there’s no track record at all yet, positive or negative. Lenders treat them similarly in practice, since both look risky from their side, but for completely different reasons.

Bad credit needs repair, which takes real time and real discipline to undo.

No credit just needs a starting point, which is a much easier problem to solve — you’re not fixing a mistake, you’re just making a first entry.

🔒 Starting Point One: A Secured Credit Card

Covered in its own post, but worth repeating here as step one: a secured card reports to the credit bureaus exactly like a regular card does.

It’s specifically designed for people in exactly Alexa’s situation — you put down a deposit that becomes your credit limit, use the card normally, and the on-time payments start building a file where there wasn’t one before.

👥 Starting Point Two: Becoming an Authorized User

If a parent or someone else you genuinely trust has a credit card in good standing, they can add you as an authorized user.

Their account’s positive history can then start showing up on your credit report too, even though you’re not the one primarily responsible for the bill.

It’s a genuinely fast way to build some initial history — provided the primary cardholder’s habits are actually good ones. Being added to someone’s account who pays late or carries a huge balance doesn’t help you. It just hands you their problem with your name attached to it.

💳 Starting Point Three: A Credit-Builder Loan

Some banks and credit unions offer a loan specifically designed for this exact purpose. You “borrow” a small amount that actually sits in a locked savings account the entire time. You make fixed payments on it. The money gets released to you once it’s fully paid off.

The payments themselves report to the credit bureaus the whole way through, building history through a process that’s about as low-risk as borrowing gets, since you’re essentially paying yourself back with extra steps and a paper trail.

🧾 What Actually Matters Once You Have Any Credit at All

On-time payments, every single time, without exception — this is the single biggest factor in the whole system.

Keeping your utilization low, meaning you’re not maxing out whatever limit you’ve got. Owing, say, $4,800 on a credit card with a $5,000 limit is considered very high utilization. Owing, say, $400 on the same card would be low utilization.

And simply letting time pass. Length of credit history is a real, weighted factor in the formula, and there’s no shortcut around it except starting as early as reasonably makes sense, which is exactly what Alexa is doing now, slightly later than she’d have liked, in a furniture store parking lot.

⏳ How Long This Actually Takes

A usable, decent score can build within about six months to a year of responsible activity. A genuinely strong score takes longer than that, since length of history is baked directly into the formula and can’t be rushed no matter how perfectly you behave. There’s no legitimate fast track, no trick, no secret cheat code a finance influencer is hiding from you.

Just a first step, taken as early as it reasonably can be — which, as it happens, is available to Alexa the moment she leaves that showroom.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved