What a Warranty Actually Promises (and What It Doesn’t)

A warranty sounds like a blanket promise that nothing will go wrong. It’s actually a much narrower, much more specific deal than that.

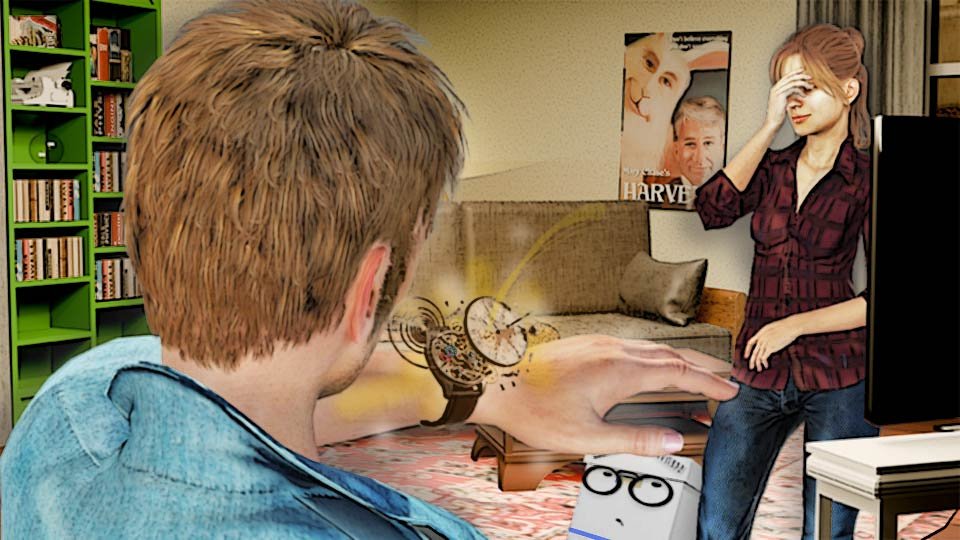
Marty bought a Firefly watch — a nice one, mechanical, the kind with visible gears you can watch tick through the case back — and saw “2-year warranty” stamped proudly on the box.

He mentally filed that away as “nothing bad can happen to this watch for two years,” a genuinely reasonable-sounding assumption.

Right up until the morning it spontaneously detonated on his wrist, gears and hairspring flying in every direction, for no reason he could identify. No drop. No water. No dumb decision on his part. Just a watch that decided, apparently on its own schedule, to stop being a watch.

Whether that two-year promise on the box actually covers something this dramatic is exactly the question worth understanding before it happens to you too.

📜 The Actual, Narrow Promise Being Made

A warranty is a promise from the manufacturer, or sometimes the seller, to repair or replace a product if it fails due to a defect in materials or workmanship.

  • It’s covered if there’s something wrong with how the thing was made.
  • It’s not covered for simply anything that could ever go wrong with it once it’s in your hands.

That distinction is the entire concept, and it’s exactly the part that gets lost in translation between the confident stamp on a box and what a customer assumes it means.

Marty’s watch spontaneously flying apart, with no outside cause anyone can point to, is close to a textbook example of the kind of failure a warranty is actually built to cover — a flaw baked in from the factory floor, not something life did to it afterward.

🔨 What a Warranty Generally Does NOT Cover

  • Normal wear and tear — a leather watch band that eventually cracks after five years of daily wear, a blender blade that dulls after thousands of smoothies.
  • Accidental damage — dropping the watch on tile, spilling something into the blender’s motor housing.
  • Misuse, or damage from ignoring the included instructions — running that same blender dry for ten minutes because you forgot to add liquid first. .

All of these are almost universally excluded, and for a consistent reason: a warranty protects against the product being flawed from the moment it left the factory. It doesn’t protect against ordinary life happening to the product afterward, no matter how sympathetic the story is

⏳ The Coverage Period: A Real, Specific Clock

Warranties run for a defined length of time — 90 days for something small and cheap, one year for most electronics, two years or more for major appliances and higher-end goods like Marty’s watch.

The clock starts on the purchase date, not from whenever you actually get around to using the thing. A watch that sat wrapped in its box for eight months as a gift, unopened, still had its warranty clock quietly ticking the entire time.

A warranty that expired while an item sat unused in a closet is still, unfortunately, expired. Nobody pauses the clock for you.

🧾 Why the Purchase Receipt Matters So Much

Nearly every warranty claim requires proof of purchase — the original receipt, an order confirmation email, or a credit card statement showing when and where the item was bought.

Without that proof, a manufacturer has no way to confirm the item is even still inside its warranty window, no matter how obviously, dramatically defective it looks sitting in pieces on your kitchen counter.

This is exactly why it’s worth photographing a receipt or forwarding an order confirmation email to yourself the day you buy anything with real warranty value. Future you, holding a broken watch and an expired memory of where it came from, will be grateful.

🔧 Repair, Replace, or Refund — Not Always Your Choice

Most warranties give the manufacturer, not you, the choice of how to resolve a valid claim: repairing the item, replacing it outright with a new one, or occasionally refunding the purchase price.

The specific wording of the warranty usually spells out which of these the company is actually obligated to offer, rather than leaving it up to your personal preference.

Marty might want a brand-new watch handed to him on the spot. Firefly’s warranty terms might only actually promise a repair. Reading the fine print before a claim, not during one, is the only way to know which outcome you’re actually entitled to.

🧭 The Big Takeaway Worth Carrying Into Every Purchase

A warranty is real, genuine protection against a product being defectively made — not a blanket insurance policy against anything that could ever happen to it in your possession.

Knowing that distinction going in means far fewer surprises when a claim actually gets filed later, whether it’s a watch that exploded for no visible reason or a blender that finally gave up the ghost on a smoothie that was, this time, entirely its own fault.

🔗 Related Reads

  • What “Limited Warranty” Actually Limits
  • What Voids a Warranty Without You Realizing It
  • How to Actually File a Warranty Claim

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

57010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
The Last Sleepover for Lewis: What Makes a Good Houseguest

Being a good houseguest isn’t complicated. It’s just a long list of small things nobody tells you until you’ve already gotten every one of them wrong.

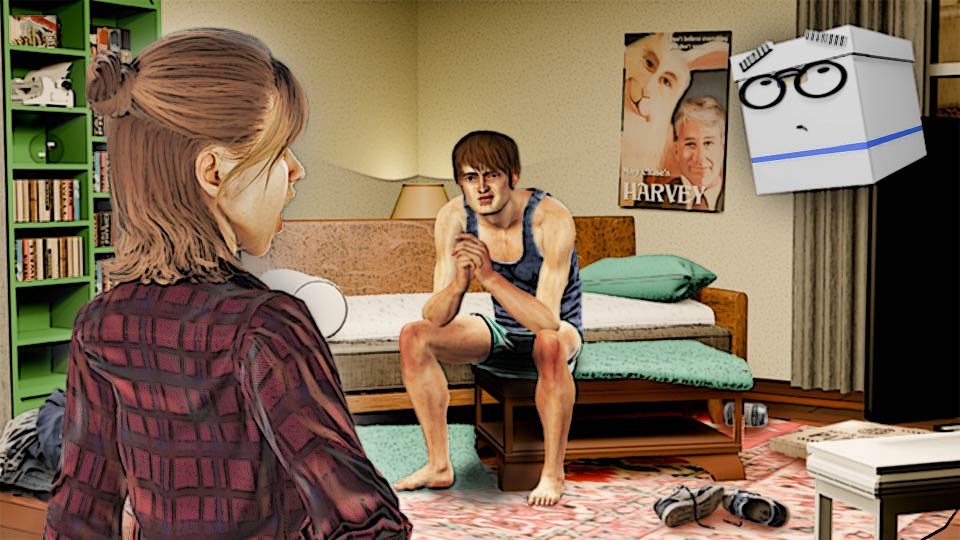
Lewis has stayed over four times now. This was going to be the last one, though he didn’t know that yet, sitting on the edge of the coffee table while Alexa delivered the news in the calm, measured tone of someone who had rehearsed this speech in the shower that morning.

Lewis is a genuinely nice guy. He is also the kind of houseguest who leaves the bed looking like a crime scene, has never once offered to buy groceries, and treats “what time works for breakfast” as a rhetorical question rather than one requiring an actual answer.

None of this made him a bad person. It made him, four visits running, a bad guest — which turns out to be its own separate skill nobody teaches directly.

🛏️ The Basics: Treat the Space With Real Respect

Keep your area reasonably tidy — not showroom-perfect, just not actively hazardous. Ask before using anything that wasn’t obviously offered to you: specific towels, the good coffee, whatever’s clearly someone’s personal shampoo and not the guest bottle.

Be mindful of noise, especially early morning and late night, when the rest of the house is asleep and you are, apparently, watching videos at full volume on your phone with the ringer still on.

None of this is complicated. It’s just “this isn’t your space” translated into the specific, boring, practical decisions that come up every single hour of an actual stay.

🍽️ Contribute Without Waiting to Be Asked

Offer to help with a meal. Pick up groceries once during the stay, unprompted.

Handle a chore — empty the dishwasher, take out the trash — without being asked to.

A host almost never asks directly for any of this, because asking a guest to help feels rude to most hosts, even when they’d genuinely appreciate it.

That means the entire signal has to come from you offering first.

Lewis, notably, never offered. Lewis assumed hospitality was a bottomless resource that simply regenerated on its own, like a video game health bar.

📅 Have a Real Sense of Your Own Schedule

Know roughly what you’re doing each day of the visit, rather than treating your host like a full-time cruise director whose entire job is entertaining you.

Your host has an actual life continuing to happen around your visit — work, errands, other obligations — and “what are we doing today?” asked fresh every single morning, with zero ideas of your own attached, gets exhausting to answer by day three.

🛏️ The Bed: Strip It or Make It, Don’t Just Leave It

On departure, strip the bedding if that’s the house norm, or at minimum make the bed neatly if it isn’t.

This is a small gesture that costs you ninety seconds and genuinely changes how the whole visit gets remembered.

A rumpled, abandoned bed is the specific image burned into Alexa’s mind from visit number three, and it is, as of this conversation, the reason visit number five isn’t happening.

🎁 The Host Gift: A Real, Worthwhile Gesture

Bring something for your host — beyond a single dinner contribution, especially for a multi-night stay.

A bottle of something, a small specialty from wherever you’re traveling from, or simply treating them to a nice meal out during the visit all genuinely round things out. It doesn’t need to be expensive.

It needs to exist, which puts it several steps ahead of whatever Lewis brought, which was nothing, four separate times, with a level of consistency that was almost impressive.

✍️ The Thank-You Afterward

Send a genuine thank-you message after you’ve left — not the rushed “thanks for having me!” shouted over your shoulder on the way out the door, but something sent later, that actually names the specific effort they put in.

For a longer or more significant stay, this is exactly the situation from the thank-you note post where an actual written note, not just a text, earns its extra effort.

Lewis sent a text. It said “lol thx.” He is currently, as far as he knows, still welcome for a fifth visit.

🔗 Related Reads

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54009

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Tipping: Who, How Much, and When

Tipping culture has quietly expanded to include a tablet turned toward you at the coffee counter. Here’s an actual framework for navigating all of it.

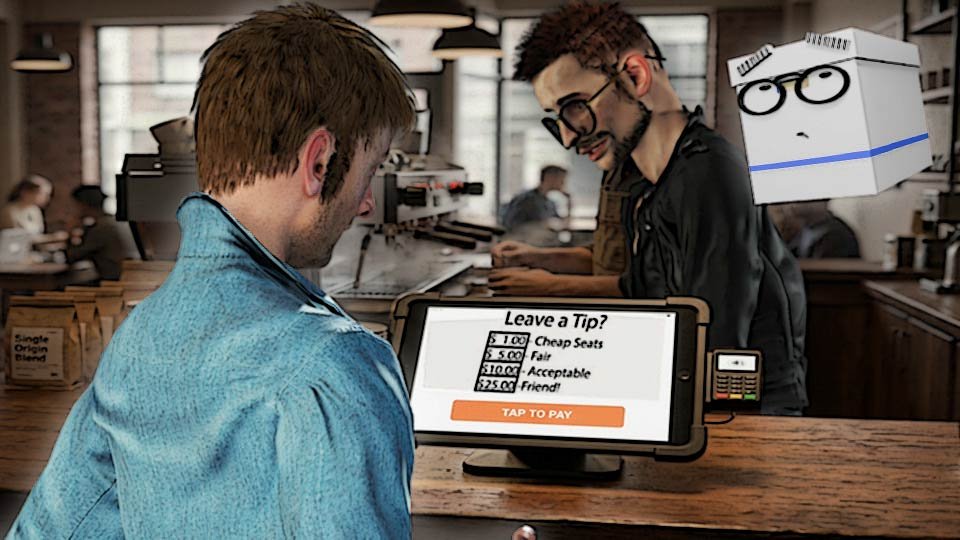
Marty ordered a single coffee. One coffee. A beverage that involved a machine and roughly eleven seconds of another human’s time. The card reader spun around to reveal three preset tip options, the lowest of which was still a genuinely startling percentage of four dollars.

He stood there, frozen, doing quiet, anxious math in front of a growing line of people, all of whom were presumably judging him for taking so long to decide the fate of sixty cents.

🍽️ Restaurants: The Most Established Baseline

Sit-down restaurant service is the one category almost everyone already agrees on: roughly 15-20% of the pre-tax bill for typical service, higher for something genuinely excellent.

It’s honestly fine to tip less for service that was genuinely bad — not “they forgot the extra napkins” bad, but “you had to physically go find your own server” bad.

Most people default toward the higher end of that range without thinking too hard about it, which is a perfectly reasonable way to not have to digest numbers while digesting dinner.

🚗 Delivery and Rideshare: A Real, Expected Category

Food delivery and rideshare drivers genuinely rely on tips as real income, not a bonus, the same way a restaurant server does.

A common range is 15-20%, or a flat few dollars for a short trip.

It’s worth treating this category with the same seriousness as sit-down dining, not as some kind of optional extra.

The driver isn’t tangential to the transaction. He is, structurally, most of it.

💇 Personal Services: Hairdressers, Barbers, and Similar

Generally 15-20%, same as a restaurant.

One wrinkle worth knowing: some salon owners who own their own chair don’t expect a tip the same way an employee stylist does, since they’re not splitting the proceeds with a business owner above them.

This is a genuinely normal thing to just ask about directly — “do you take tips?” is not an awkward question, it’s a completely standard one, asked constantly, by people who did not want to do the math either.

📱 The Tablet-Turned-Toward-You Situation: You Genuinely Have Options

Counter service — coffee shops, quick takeout, the eleven-second transactions of the world — is where tipping culture has expanded fastest and least consistently, and it’s worth understanding why that screen makes you feel the way it does before deciding what to do about it.

Those preset percentages aren’t neutral. They’re deliberately set high, because a screen that starts at 25% makes 15% feel like the stingy option, even on a four-dollar coffee that took eleven seconds to make. That’s not etiquette. That’s a psychology experiment wearing a payment terminal’s clothes.

So, the actual solution: decide your own policy in advance, before you’re standing there with a line behind you and a cashier definitely not watching your screen nearly as closely as you assume they are.

A reasonable, defensible line is to tip when something was genuinely made for you — a latte someone actually steamed and poured, a sandwich someone built — and to skip it, guilt-free, for something that was just handed to you, like a bottled drink or a bag of chips rung up at a register.

Hit “custom amount,” type in zero, and move on with your day. The moment of awkwardness lasts about two seconds and is forgotten by literally everyone else in that line before they’ve even reached the counter.

A tablet prompting you is a business choice, not a social contract. You’re allowed to treat it as optional, because it is.

🏨 Hotels: An Easy Category to Forget Entirely

Housekeeping is worth a few dollars a day, left directly in the room — in cash, and clearly marked (a small envelope, a note that says “thank you”) so it doesn’t get mistaken for money someone accidentally left behind and skipped entirely.

This is genuinely easy to forget, since unlike a server, housekeeping staff are rarely standing there for you to hand something to directly. Nobody’s going to chase you down about it.

That’s exactly why it’s worth building the habit of leaving it before you check out, not after you’re already in the elevator wondering if you should have.

🎯 The General Principle Underneath All of This

Tipping norms genuinely vary by service type, by region, and sometimes by the individual business you happen to be standing in.

When you’re truly unsure, a quick, discreet search for “tipping norms for [specific situation]” settles most uncertainty faster than the anxious math Marty was doing in that coffee line.

And here’s the part worth actually believing: nobody has ever once been offended by a guest who clearly put a little thought into it — whichever way that thought landed.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What a Credit Score Actually Measures

A credit score sounds like a mysterious verdict handed down from on high. It’s really just a report card for one very specific behavior.

Marty has heard the phrase “good credit score” roughly a thousand times in his life, has a general sense that a higher number is better, and could not, if put on the spot, explain what a credit score is actually measuring — good at what, exactly? Being a nice person? Showing up on time? He genuinely didn’t know.

🎯 What It’s Actually Measuring: One Thing

A credit score is a three-digit number, typically ranging from 300 to 850, that predicts one specific thing: how likely you are to repay borrowed money on time, based entirely on your past history of borrowing and repaying.

It’s not a measure of income, net worth, intelligence, or general trustworthiness as a human being — purely and only a track record of debt behavior.

🧮 The Five Ingredients, and Roughly How Much Each One Weighs

Your credit score is determined by these five factors:

  • Payment history (do you pay on time) is the single biggest factor, roughly 35% of the score.
  • Credit utilization (how much of your available credit you’re actually using, covered in its own post) is next, around 30%.
  • Length of credit history — how long you’ve had credit accounts open — makes up about 15%.
  • The mix of credit types you have (credit cards, loans, etc.) contributes about 10%.
  • And new credit inquiries — how often you’ve recently applied for new credit — rounds out the last 10%.

📊 What the Actual Ranges Mean

Roughly speaking, these are the credit range rankings:

  • 800-850 is considered exceptional
  • 740-799 very good
  • 670-739 good
  • 580-669 fair
  • below 580 poor

Lenders use these ranges to decide not just whether to approve you, but what interest rate to actually offer — a real, dollars-and-cents difference, not just a bragging-rights number.

🎢 Interest Rates: The Price of Being a Mystery

Here’s the part that last section undersells: that number doesn’t just decide whether you get approved. It decides how much the approval actually costs you.

Every loan and card comes with an interest rate attached — basically a rental fee for borrowing someone else’s money. Lenders don’t hand that fee out equally. A high score says “this person pays reliably, historically, boringly” and earns a better rate. A low score, or no score at all, says “no idea, never met this person” — and lenders protect themselves from that uncertainty the only way they know how: by charging more, just in case.

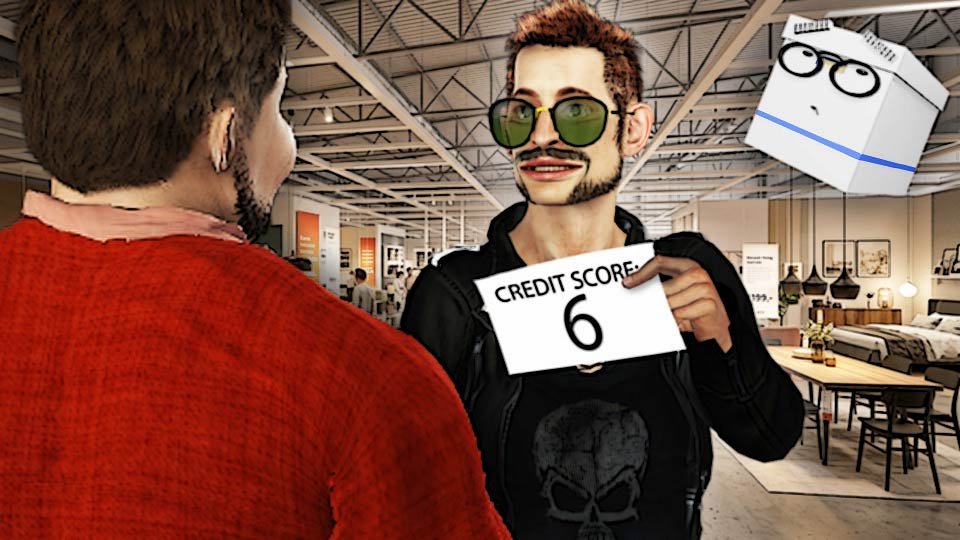
The gap adds up fast, too. Same car, same dealership, same day: the guy with a low credit score might be looking at $785 a month, while the guy with excellent credit drives off in the identical car for as little as $550. Same loan. Different mystery level. Different price tag every single month for the next five years.

So the number isn’t a report card. It’s a discount code, earned one on-time payment at a time — and the alternative is paying full price for being a stranger.

👻 The Myth Worth Killing Immediately

Checking your own credit score does not lower it.

This is one of the most persistent, wrong beliefs out there, and it keeps people from looking at a number that genuinely affects their financial life.

Checking your own score is called a “soft inquiry” and has zero impact — it’s only when a lender checks your credit as part of an actual application (a “hard inquiry”) that it can cause a small, temporary dip.

🆓 How to Actually Check It, for Free

Many credit card companies and banks now offer free credit score access right inside their app.

Sites like AnnualCreditReport.com provide free access to your full credit report (a different, more detailed document than just the score) once a year from each of the three major bureaus.

There’s no good reason to pay a monthly fee just to see a number you’re entitled to check for free.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Secured vs. Unsecured Credit Cards: Which One You Actually Need

One of these cards asks for a deposit before it trusts you with credit. That’s not a punishment — it’s actually a smart starting move.

Alexa applied for a regular credit card, got denied for having “insufficient credit history,” and felt the specific, circular frustration of being told she needed credit history to get credit, with no apparent door leading in. There’s a door. It’s just a slightly different one than she was knocking on.

🛋️ Secured vs. Unsecured: What’s the Difference?

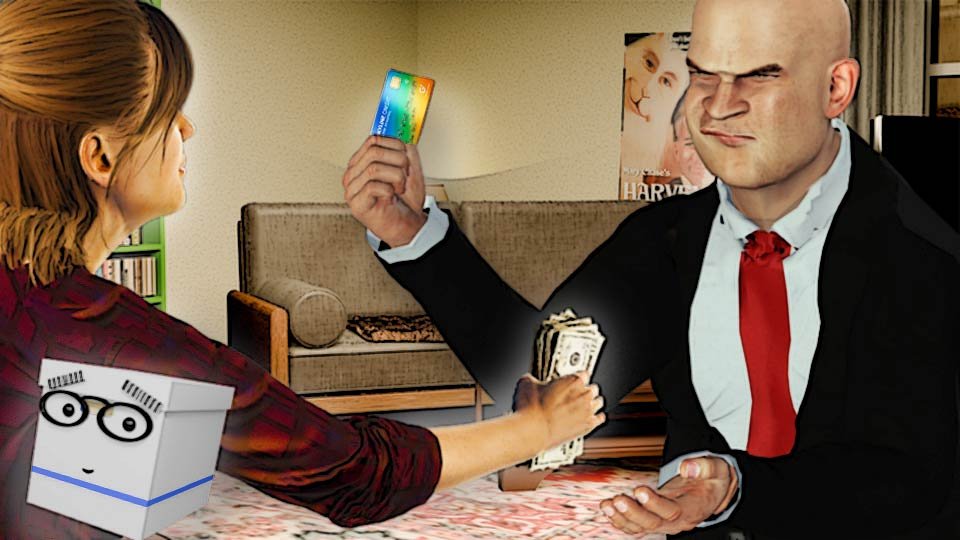
Picture two strangers who show up at your door on the same afternoon, both wanting to borrow $300, both with an honest face and a suspiciously specific repayment plan.

The first guy hands you a driver’s license, shakes your hand, and promises to pay you back $27.50 a month for the next twelve months — $330 total, meaning you walk away $30 richer for helping him out. Nice guy. You believe him. You have, however, no actual leverage beyond his word and a mild sense that he seemed trustworthy.

The second guy wants to buy your couch, also for $300, and offers the exact same deal — $27.50 a month for a year. Except he takes the couch home with him today, right now, sofa cushions and all, on nothing but that same promise to pay.

Here’s the entire difference in one sentence: if guy number two stops paying, you know exactly where your couch is, and you’re legally entitled to go get it back. If guy number one stops paying, you’ve got a phone number, a memory of a firm handshake, and absolutely nothing else.

That’s secured versus unsecured credit in a nutshell. A secured line is backed by real, repossessable property — the couch, a car, a house. An unsecured line is backed by nothing but your word that you’ll pay it back, which is exactly why lenders charge more interest for it and check your credit history more carefully before handing it over. Collateral isn’t a technicality. It’s the entire reason one of these guys sleeps easier than the other.

🔓 Unsecured: The “Normal” Credit Card

An unsecured credit card is what most people picture when they think of a “credit card” — no deposit required, the credit limit is based purely on the bank’s assessment of your creditworthiness.

The catch: banks and credit card companies typically require an existing credit history before they’ll approve you for one in the first place — which is exactly the wall Alexa ran into.

The second catch: because they’re lending you money on nothing but your word, banks and credit card companies usually charge a higher interest rate on that line of credit than they would on a secured one.

🔒 Secured: The Same Card, With a Deposit Attached

A secured credit card requires a refundable security deposit upfront — commonly matching your credit limit, so a $300 deposit gets you a $300 limit.

That deposit is the bank’s insurance policy against someone with no track record yet — not a punishment, just how a bank manages risk with an unknown quantity.

It’s the same idea as the couch. If you don’t pay, the bank keeps your $300 — the equivalent of you collecting the couch.

🪜 Why Secured Cards Are Genuinely the Smart Starting Move

A secured card reports to the credit bureaus exactly the same way an unsecured one does — on-time payments build real credit history either way.

It’s specifically designed as a stepping stone: use it responsibly for a while, and many issuers will actually convert it to an unsecured card automatically, refunding your original deposit once they do.

The downside: you have to come up with $300 first.

Now, you’re not paying a $300 fee that just vanishes. You’ll get that money back eventually, and in the meantime it’s sitting there as your actual credit limit, doing its job.

And it’s available to you on your new credit card – you’ll most likely have at least a $300 credit limit. Use the card to buy your groceries and stuff, just paying off the card at the end of the month.

But you do need to have that $300 up front.

💵 What Happens to the Deposit

As long as the account stays in good standing, the deposit isn’t a fee — it’s held, and returned to you either when the card converts to unsecured or when you close the account with no outstanding balance.

It’s genuinely your money the entire time, just serving as collateral rather than sitting in a regular savings account.

🎯 The Actual Decision

If you have zero credit history, a secured card is very often the realistic starting point, not a lesser option — plenty of people with excellent credit today started on exactly this kind of card.

If you already have some credit history through another route (a co-signed account, a student loan, being an authorized user on a parent’s card), you may already qualify for unsecured directly.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Filling Out Your First Credit Card Application: What They’re Actually Asking

Applying for a first credit card feels like it should come with an instruction manual. It doesn’t, so here’s one.

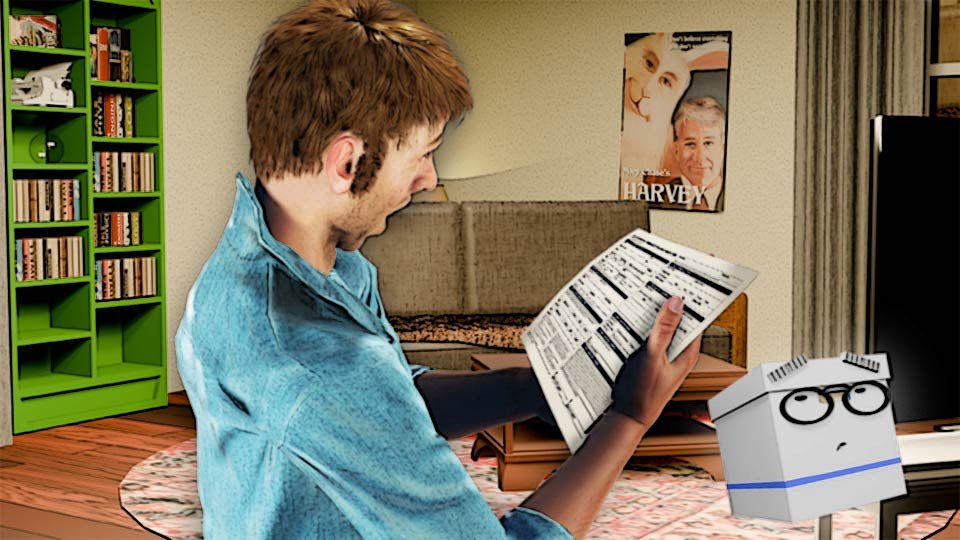
Marty sat down with an actual paper application, pencil in hand, and stared at Section 2: Financial Details like it had just asked him to disclose state secrets. Annual income. Employer. Years employed. Monthly rent.

It felt like the kind of form you’d need a briefcase full of documents to complete.

He did not own a briefcase. He owned a pencil and a mounting sense of dread. Neither turned out to be necessary, though the pencil helped.

🪪 Applicant Information — What It Actually Wants

Name, address, phone number, date of birth, and your Social Security number. That last one is usually the part that makes people pause, hovering the pencil, wondering if handing it over on a form is a mistake.

It isn’t.

The credit card company, called “the issuer,” needs it for two specific reasons: confirming you’re actually who you say you are, and pulling your credit report.

That credit repor is the whole reason this section exists at all. Without it, they have no file to check and nothing to approve you against.

💵 Financial Details — The Question That Feels Like a Trap

Annual income, employer name, how long you’ve worked there, and your monthly rent or mortgage payment.

This is the section that makes an application feel like an audit, but it’s really just one calculation in disguise: how much money is coming in, versus how much is already going out.

That ratio is called debt-to-income, and it’s the main thing an issuer uses to decide both whether to approve you and what starting credit limit makes sense. It’s not a judgment on your life choices. It’s just math they need before they hand you a number.

📄 Do You Need Your Tax Returns for This?

No — and this is worth saying plainly, because it’s the exact thing that makes people freeze up before they’ve even started.

For a standard personal credit card, income is self-reported. You write the number down.

You don’t attach a W-2, a pay stub, or a tax return to prove it.

The issuer may occasionally verify income after approval, especially for a high limit (a card that has, maybe, $5,000 or more available), but that’s the exception, not the standard process.

Marty didn’t need a briefcase. He needed the number, from memory, and honesty.

🔁 Balance Transfer Options — You Can Skip This One

This section asks about moving an existing balance from another credit card onto this new one, usually to take advantage of a lower promotional interest rate on the new card.

If this is genuinely your first credit card, you don’t have an existing balance anywhere to transfer. Leave the whole box blank and just move on. It isn’t relevant to you yet, and nothing about your application suffers for skipping it.

🎨 Card Design Preferences — The Only Part With No Wrong Answer

Which design you want the physical card to look like.

That’s it.

No financial mechanics hiding underneath this one, no calculation, no consequence. This is the one section on the entire form where Marty could relax, and possibly the only part of the whole process anyone designed to actually be fun.

✍️ Signature and Consent — What You’re Actually Agreeing To

Signing authorizes two things: that the information you provided is accurate, and that the issuer can pull your credit report to make a decision.

That credit pull is called a hard inquiry. For most applicants, it causes a small, temporary dip in an existing score, although you won’t — but have an existing score to dip.

With no credit history yet, this inquiry isn’t shaving points off anything. It’s the first entry in a file that’s currently empty, the actual starting gun on the score he doesn’t have yet.

Either way, it’s a completely normal, expected part of applying for any credit, not a red flag or a mistake. Signing isn’t the scary part of the form. It’s just the part where you confirm everything above it was true.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52006

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Building Credit From Zero: The Actual First Steps

No credit history isn’t bad credit — it’s just an empty file. Here’s why that empty file matters, and how to actually start filling it in.

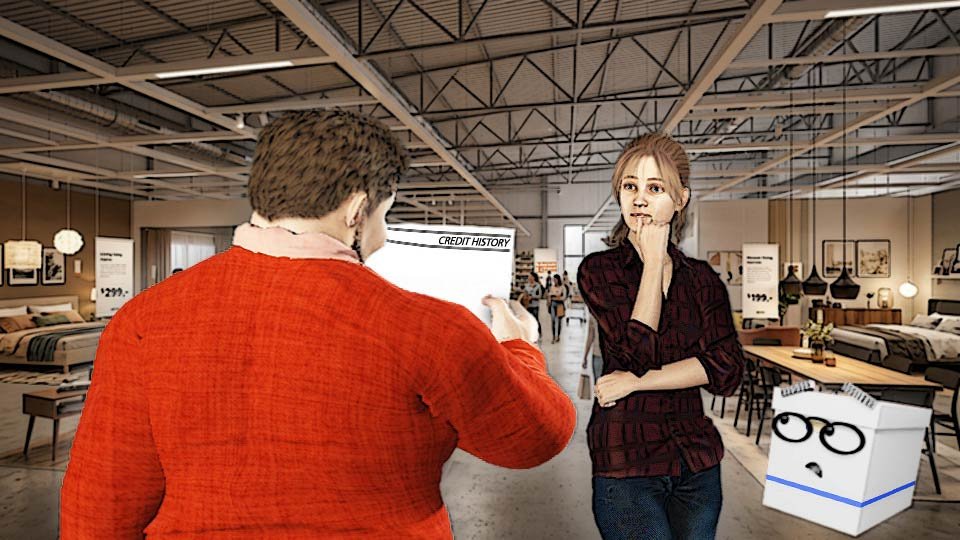
Alexa stood in a furniture superstore, picking out her first real couch, feeling genuinely like an adult for possibly the first time in her life. Then the salesman pulled up the financing application, watched her credit page load in front of him, and watched it stay completely, perfectly blank.

He looked at it. He looked at her.

“And, we’re paying in cash today?” he asked, in the tone of a man recalculating his entire afternoon.

She was not, in fact, planning on paying cash today.

She spent the drive home trying to figure out whether “no credit” was the same problem as “bad credit,” since both seemed to produce the exact same polite, faintly pitying rejection.

❓ Wait, Why Does This Even Matter?

Here’s the part nobody explains before you’re standing in a showroom getting quietly judged by a salesman: a credit score isn’t really about whether you’re a good person, or even whether you’re good with money in any broad sense.

It’s a lender’s best guess at one specific question — if they hand you money, how likely are you to pay it back. That number then follows you into a surprising number of rooms that have nothing to do with loans at all.

  • Buying a car, obviously.
  • But also renting an apartment — plenty of landlords pull a credit check before they’ll hand you keys.
  • Getting a cell phone plan without a hefty deposit.
  • Financing that couch, or a laptop, or literally anything at a checkout counter that offers “pay over time.”
  • In some states, even your car insurance premium.
  • Eventually, a mortgage, where a good score can genuinely save you tens of thousands of dollars in interest over the life of the loan.

None of these institutions knows you personally. The score is the introduction they’re working from instead.

An empty credit file doesn’t say “this person is risky.” It says “we have literally no information to work with,” which, to a nervous lender, ends up looking almost the same in practice. The fix isn’t proving you’re trustworthy through sheer force of personality. It’s giving the file something to actually say.

⚖️ No Credit Is Not the Same as Bad Credit

Bad credit means a history of missed payments or other negative marks — a track record, just not a good one.

No credit means there’s no track record at all yet, positive or negative. Lenders treat them similarly in practice, since both look risky from their side, but for completely different reasons.

Bad credit needs repair, which takes real time and real discipline to undo.

No credit just needs a starting point, which is a much easier problem to solve — you’re not fixing a mistake, you’re just making a first entry.

🔒 Starting Point One: A Secured Credit Card

Covered in its own post, but worth repeating here as step one: a secured card reports to the credit bureaus exactly like a regular card does.

It’s specifically designed for people in exactly Alexa’s situation — you put down a deposit that becomes your credit limit, use the card normally, and the on-time payments start building a file where there wasn’t one before.

👥 Starting Point Two: Becoming an Authorized User

If a parent or someone else you genuinely trust has a credit card in good standing, they can add you as an authorized user.

Their account’s positive history can then start showing up on your credit report too, even though you’re not the one primarily responsible for the bill.

It’s a genuinely fast way to build some initial history — provided the primary cardholder’s habits are actually good ones. Being added to someone’s account who pays late or carries a huge balance doesn’t help you. It just hands you their problem with your name attached to it.

💳 Starting Point Three: A Credit-Builder Loan

Some banks and credit unions offer a loan specifically designed for this exact purpose. You “borrow” a small amount that actually sits in a locked savings account the entire time. You make fixed payments on it. The money gets released to you once it’s fully paid off.

The payments themselves report to the credit bureaus the whole way through, building history through a process that’s about as low-risk as borrowing gets, since you’re essentially paying yourself back with extra steps and a paper trail.

🧾 What Actually Matters Once You Have Any Credit at All

On-time payments, every single time, without exception — this is the single biggest factor in the whole system.

Keeping your utilization low, meaning you’re not maxing out whatever limit you’ve got. Owing, say, $4,800 on a credit card with a $5,000 limit is considered very high utilization. Owing, say, $400 on the same card would be low utilization.

And simply letting time pass. Length of credit history is a real, weighted factor in the formula, and there’s no shortcut around it except starting as early as reasonably makes sense, which is exactly what Alexa is doing now, slightly later than she’d have liked, in a furniture store parking lot.

⏳ How Long This Actually Takes

A usable, decent score can build within about six months to a year of responsible activity. A genuinely strong score takes longer than that, since length of history is baked directly into the formula and can’t be rushed no matter how perfectly you behave. There’s no legitimate fast track, no trick, no secret cheat code a finance influencer is hiding from you.

Just a first step, taken as early as it reasonably can be — which, as it happens, is available to Alexa the moment she leaves that showroom.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
RSVP: What It Actually Means and Why Ignoring It Is Rude

RSVP shows up on nearly every invitation and almost nobody knows what the letters actually stand for, let alone why ignoring it is such a problem.

Alexa has seen the letters “RSVP” on essentially every invitation she’s ever received in her entire life. She’s always understood it as a vague, generalized suggestion to “let them know maybe.” She has genuinely never once known it was actually a specific French phrase making a fairly direct request — one she has, by her own count, ignored roughly a dozen times without a flicker of guilt. That’s about to change.

🇫🇷 What the Letters Actually Stand For

RSVP is an abbreviation of the French phrase “répondez s’il vous plaît” — literally, “please respond.” It’s not a vague nudge or an optional nicety. It’s a direct, explicit request for a definite yes or no answer, dressed up in a language most English speakers only half-recognize and have collectively agreed to never actually translate in their heads.

If the four letters said “PLEASE RESPOND” in plain English instead, a lot fewer people would feel comfortable ignoring them.

Same request. Fancier packaging.

😬 Why Not Responding Is Genuinely Inconsiderate, Not Just Distracted

A host planning an event is making real decisions based on how many people actually show up. How much food to prepare. How many chairs to set out. Sometimes a per-person cost they’re personally covering out of their own pocket, especially for something like a catered wedding or a restaurant reservation with a set menu.

Not responding doesn’t just leave a host wondering in some abstract sense — it can genuinely cost them real money, and create real logistical stress, even though it rarely feels that consequential from the guest’s side of the equation.

You forgetting to reply for two weeks is, to you, a minor oversight. To the host, it’s an unfilled seat they can’t plan around.

📅 The Deadline Actually Matters, Not Just the Response

An RSVP date isn’t arbitrary, and it isn’t the host being fussy.

It’s usually tied directly to when they need to finalize a headcount with a caterer, a venue, or a rental company — real deadlines imposed on the host by other businesses, which then get passed down to you as your deadline.

Responding after that date puts a host in an uncomfortable spot: either scramble to accommodate a late addition with a vendor who’s already locked in a number, or have to say no to you.

Neither option is fun for them, and both were avoidable.

✅ What a Complete RSVP Actually Includes

A clear yes or no.

Not “maybe,” not “probably,” not silence that the host is left to interpret.

Respond by the requested date, through whatever method was actually requested — a reply card mailed back, a phone call, a specific RSVP website or app link included in the invitation.

If the host asks you to respond a particular way, that’s not a suggestion either; showing up to the event and verbally confirming in person doesn’t count if they needed the headcount two weeks earlier.

If the invitation asks for a specific headcount — especially in a plus-one situation — include that clearly and by name if you can, rather than leaving the host to guess or chase you down for a follow-up text.

“Yes, I’ll be there” is only half an answer if they also need to know whether you’re bringing someone.

🔁 What to Do If Your Answer Changes Later

If you RSVP yes and then genuinely can’t attend — or the reverse, you said no and something opens up — letting the host know as soon as you know is the actual courteous move, not waiting until the event itself to sort it out.

Plans changing isn’t rude on its own. Everyone’s life shifts sometimes. Leaving a host to find out at the door, or to notice an empty seat they paid for, is the part that’s actually inconsiderate.

❓ A Few Terms Worth Knowing While You’re At It

“Regrets only” means the opposite of a standard RSVP: you only need to respond if you’re NOT coming. Silence is treated as a yes. It’s used for lower-stakes gatherings where the host expects most people to attend and doesn’t want to chase down a hundred separate confirmations. “

RSVP by [date]” is exactly what it says — a hard deadline, not a suggestion of when responses start being welcome.

And a formal invitation that lists specific names on the envelope, without “and guest” anywhere on it, means exactly those people are invited, nobody else — asking to bring someone not listed puts the host in the position of having to say no to your face, which is worth sparing them if you can.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What to Bring When You’re a Dinner Guest

Showing up empty-handed to a dinner feels fine until everyone else is holding something and you’re not. Here’s what’s actually expected.

Marty showed up to a dinner party at a friend’s new apartment with nothing but his usual charming self and a healthy appetite. He clocked it the moment he walked in: every other guest was holding a bottle of wine, a dessert, or something small and wrapped. A silent dress code, apparently, and he’d missed the memo entirely. He has since read this post. You don’t want to learn it his way.

🍷 The Default, Safe Answer: A Bottle of Wine

Wine remains the most common, safest go-to for a dinner party, largely because it works whether or not it actually gets opened that night. A host isn’t obligated to serve whatever you bring — it’s genuinely not rude for them to set it aside for another occasion instead. Bringing wine isn’t really about supplying tonight’s drink. It’s about arriving with something in hand.

If you don’t know wine, you don’t need to become an expert to get this right. A mid-range bottle, somewhere in the $15–$20 range, from an actual wine shop rather than a gas station, covers you fine.

If you genuinely have no idea what to grab, telling the person behind the counter “something for a dinner party, nothing too fancy” gets you a solid answer in about ten seconds. Red is the safer default if you know nothing else about the meal — it pairs more forgivingly across a wider range of dishes than white does, though if you happen to know the meal is fish or something light, white is the better call.

When genuinely unsure, red wins the coin flip.

🚫 What Actually Cancels the “Bring Something” Rule

If the host explicitly says “please don’t bring anything, I’ve got it all covered,” that’s usually a genuine, sincere request, not just politeness. Showing up with something anyway isn’t wrong, but it’s also not expected the way it is by default.

Listening to what a host actually says matters more than defaulting to a rigid rule regardless of what they told you.

🍽️ When It’s a Potluck Instead of a Dinner Party

A genuine potluck is a different animal entirely. Bringing a specific dish is the whole point, not an optional courtesy on top of it.

If unsure which category an invitation falls into, it’s a completely normal, non-awkward question to just directly ask the host.

If it is a potluck, a few things make you a genuinely easy guest to have. Ask if there’s a category already covered — nobody needs five potato salads and zero desserts, and a quick “what’s still needed?” solves that instantly.

Bring something that travels well and doesn’t need the host’s oven or stovetop at the last minute; a dish that needs to be reheated, plated, or finished in someone else’s kitchen adds a chore to their night, not a gift.

And bring something you’ve actually made before, ideally more than once — a potluck is a genuinely bad place to debut a recipe for the first time and discover it doesn’t travel, doesn’t reheat, or just didn’t turn out.

🌸 Non-Consumable Options, If You’d Rather Not Bring a Drink

Flowers, a small plant, or a nice candle all work as alternatives to wine, especially for a host who doesn’t drink or where a food-related gift feels like it might compete with the meal itself.

None of these require nearly the thought people put into agonizing over the “perfect” bottle. A pre-arranged bouquet from any grocery store, handed over at the door, does the job completely.

🍰 If You’re Bringing Food, Ask First

Unless it’s explicitly a potluck, checking with the host before bringing a dish avoids two problems at once: accidentally duplicating something they’ve already planned, and bringing something that clashes with a meal they’ve carefully put together.

It’s also worth asking about any dietary restrictions among the other guests before you show up with something everyone but one person can actually eat. A quick “want me to bring anything specific?” solves all of this cleanly, in one text, before you’ve bought anything at all.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54003

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How to File Taxes (When You’ve Never Done It Before)

Filing taxes for the first time feels like a foreign language wrapped around a deadline. Here’s what your actual options are, and how to pick one.

Alexa knows, in a vague and slightly panicked way, that she’s supposed to “do her taxes” sometime before April 15. She does not know what that sentence actually means as an action. Does she mail something? Is there a website? Does a man in an office do it for her while she sits very still? She has a W-2 sitting in a drawer that she’s pretty sure is important, and a level of dread usually reserved for jury duty.

Let’s fix that, one piece at a time.

📋 What “Filing Taxes” Actually Means

Here’s the plain-English version, no drawer-based dread required: filing taxes means telling the IRS how much you earned last year, and letting the math work out whether you paid the right amount along the way.

Your employer already withheld an estimated chunk of tax from every paycheck all year.

Filing is just the part where you find out if that estimate was too high, too low, or right on the nose.

Too high, and you get a refund — the government hands back the extra you overpaid. Too low, and you owe the difference. Either way, this is the appointment where the actual number gets settled.

There are several ways to accomplish that reckoning and arrange for either the refund or the tax payment. Let’s look at each one.

🗺️ Wait, Federal AND State? Nobody Mentioned That

Here’s the part that ambushes almost everyone the first time: “filing your taxes” isn’t one errand. It’s two. Federal taxes go to the IRS. State taxes go to your own state’s department of revenue, a completely separate government office with its own form, its own rules, and its own deadline (usually the same day, but not guaranteed). Nine states skip income tax entirely — Texas and Florida among them — so if you live in one of those, congratulations, you’ve got one fewer errand than everyone else. Everybody in the other forty-one states has two.

This is also exactly where “free tax filing” quietly turns into a bit of a bait and switch.

IRS Free File — the actual federal free-filing program, available if your income falls under roughly $84,000 to $89,000 — covers your federal return at no cost.

State coverage depends entirely on which partner software you pick. Some throw in a free state return. Most don’t. TurboTax and H&R Block both run this exact playbook: free federal return to get you in the door, then a state filing fee once you’re already halfway through and invested in finishing.

If avoiding that fee actually matters to you, a few real options exist.

  • FreeTaxUSA files federal for free regardless of income, and charges a flat, genuinely small fee for state — nowhere near the $60-plus the big-name software tends to charge.
  • VITA, the free in-person IRS volunteer program, covers both federal and state for people under a certain income level.
  • Plenty of states also run their own free e-file portal directly through their own department of revenue, worth a quick check before assuming you have to pay a software company at all.
  • And if you’re in the military, MilTax covers federal plus several state returns free, no income limit attached.

None of this is required reading if you’re fine paying the state fee and moving on with your life. But knowing it’s a choice, and not just how things are, is worth having before you’re staring at a checkout screen wondering why “free” suddenly has a price tag.

🖥️ Option 1: IRS Free File

The IRS partners with several tax software companies to offer completely free federal filing, as long as your income falls under a set threshold (it adjusts most years, so it’s worth checking the current number rather than trusting an old one).

It walks you through the same interview-style questions as the paid software, just without the price tag at the end. If your tax situation is simple — one job, one W-2, nothing exotic — this is often the easiest place to start.

💻 Option 2: Commercial Tax Software

TurboTax, H&R Block’s online product, and a handful of others all work roughly the same way: you answer plain-English questions, type in numbers straight off your W-2, and the software quietly does the actual math and form-filling in the background.

It’s built for someone who’s never done this before, which, no offense, is exactly Alexa’s entire situation. It usually costs something once your return gets past the simplest tier, but for most people it’s a genuinely manageable, low-drama way to get through the process solo.

🧑‍💼 Option 3: An Actual Human Tax Preparer

A CPA or an enrolled agent (a tax professional specifically licensed to represent you in front of the IRS) can do the whole thing for you, in person or remotely, and answer questions in real time instead of leaving you to Google them at 11 p.m. It costs more than software.

It’s genuinely worth it if your situation has any real complexity to it — freelance income, multiple jobs, a big life change like buying a home or getting married. If your tax return is basically one W-2 and nothing else, this is probably more firepower than you need.

🤝 Option 4: Free, In-Person Help (VITA)

The IRS also runs a program called VITA — Volunteer Income Tax Assistance — offering free, in-person help from IRS-certified volunteers, for people under a certain income level.

If cost is the main thing standing between you and a preparer, this is worth looking into before assuming a preparer is out of reach entirely.

📄 What You Actually Need Before Starting, No Matter Which Option You Pick

Each of these documents either document your income last year, or your identity. Leaving one out of your filing will delay the processing of your return.

  • Every W-2 from every job you had last year — yes, even the one you quit in March.
  • Any 1099 forms, if you did freelance or gig work anywhere.
  • Your Social Security number.
  • Last year’s tax return, if you filed one, since it speeds up a lot of the software’s auto-fill.
  • And your bank account information, if you want a refund deposited directly instead of waiting on a paper check.

⏰ The Deadline That Actually Matters

Federal taxes are due April 15 most years. An extension is available if you need more time to file the paperwork — but it’s important to know that an extension to file is not an extension to pay. If you owe money, that’s still due on the original deadline, extension or not.

✅ How to Actually Decide Which One Fits You

One job, one W-2, nothing complicated? Free File or commercial software will handle it in under an hour.

Freelance income, multiple jobs, or a major life change this year? A human preparer earns their fee.

Tight on money and the situation’s simple? VITA exists exactly for this.

There’s no prize for picking the hardest option — just pick the one that matches how complicated your year actually was, and get it done.

🙅 FYI: The Guy Down the Hall Is Not a Tax Professional

Every apartment building has one. A neighbor, a coworker, a friend’s cousin who “basically does taxes” and is happy to walk you through it over coffee, for free, out of pure generosity. That generosity is real. The advice underneath it is a coin flip.

Tax law changes most years — sometimes small tweaks, sometimes real ones — and “what worked for my return” doesn’t automatically mean “what’s correct for yours.” Your friend down the hall doesn’t know your specific income sources, your specific state, or whether the trick that saved him money last year even still applies this year. He’s not being dishonest. He’s just confidently repeating something that was true once, for a completely different tax situation than the one sitting in front of you.

None of this means never listen to a friend who mentions something useful — a tip about VITA, a heads-up that a state has its own free e-file portal, that’s the good kind of word-of-mouth. The line is between “here’s a resource you might not know about” and “let me just do your taxes for you real quick.” The first one is a favor. The second one is a liability neither of you actually wants, however good the intentions.

🔗 Related Reads

  • Estimated Quarterly Taxes: Who Actually Needs to Pay Them
  • What Happens If You File Late
  • How Tax Refunds Actually Work (It’s Not Free Money)

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56011

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved