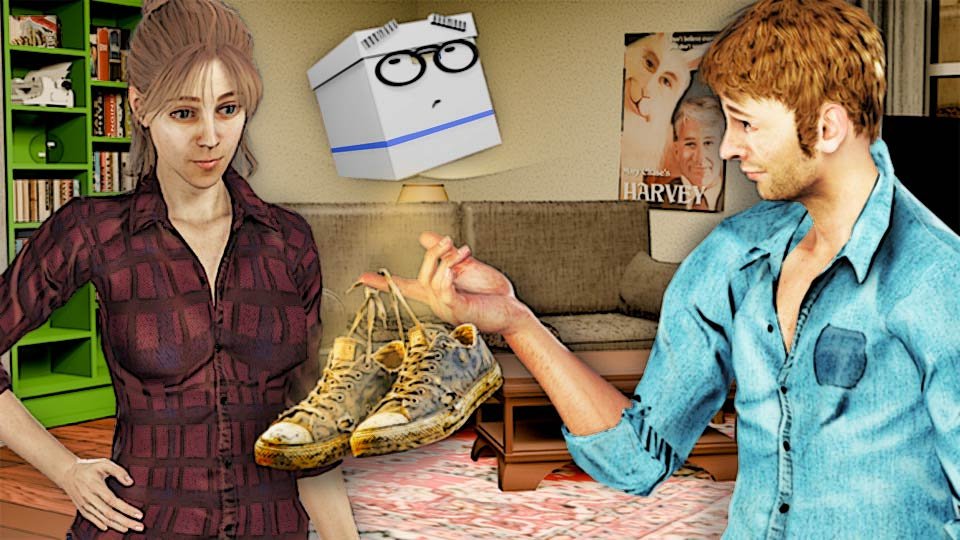
Marty is holding up a pair of sneakers that have been through several genuine hardships — mud, at least one questionable puddle decision, a sole worn down to something closer to a suggestion than a tread pattern — and asking, with total sincerity, whether the extended warranty he bought on them two years ago covers this.
Alexa’s face is doing a great deal of work in this conversation, none of it verbal, all of it communicating some version of “absolutely, unequivocally not, and I cannot believe I have to explain why.”
Marty bought that same kind of confused four-second yes at plenty of other checkout counters too, on a laptop, a TV, a blender, without ever quite working out what he was actually paying for. Let’s actually work it out.
💰 What You’re Actually Buying
An extended warranty, sometimes called a protection plan, extends coverage beyond the manufacturer’s original warranty period, usually for a specific extra fee tacked onto the purchase.
It’s essentially a bet: you’re paying money now on the chance that something breaks later, which is genuinely the same structure as an insurance policy, just scaled down to one single object instead of a broader category of risk.
And like any warranty, it almost always still only covers a genuine defect or malfunction — not, say, two years of mud, puddles, and enthusiastic wear.
Marty’s sneakers didn’t malfunction. They did their job, repeatedly, until they simply wore out, which is a completely different category of “broken” than any warranty, extended or otherwise, was ever built to cover.
📊 Why They’re Priced the Way They Are
Extended warranties are generally quite profitable for retailers, which is exactly why they get pushed so consistently at checkout, by an employee who is frequently required to ask whether you’d like one before they can even finish ringing you up.
The price charged is usually well above the statistical likelihood and average repair cost of the item actually needing covered work.
That’s not a conspiracy theory — it’s just how the math works out in the retailer’s favor across enough transactions. Somebody’s paying for that profit margin, and it’s the aggregate of everyone who bought the plan and never used it.
✅ When It Genuinely Might Make Sense
Expensive electronics with a known history of specific failure points — a particular laptop model with a documented hinge problem, for instance.
Items that get heavy or rough use as a matter of course.
Or, and this one’s worth being honest with yourself about, if you already know you’re genuinely bad about being careful with fragile things. This is a real, personal risk assessment, not a blanket yes or no answer that applies to every purchase equally.
\And if replacing the item outright would be a genuine financial hardship — not an annoyance, an actual hardship — some peace of mind may be worth the cost even when the pure statistics lean against it.
❌ When It Usually Doesn’t
Inexpensive items, where the extended warranty cost approaches a meaningful fraction of the item’s own price — a $15 warranty on a $40 kitchen gadget is a much worse deal, proportionally, than a $50 warranty on a $2,000 laptop.
Products with a strong general reliability reputation. And anyone who could comfortably self-insure, meaning simply set aside the cost of the warranty itself in a savings account and use that money if something eventually breaks.
Do that consistently across enough purchases, and you come out ahead of buying the warranty every single time, because you keep the money on all the purchases that never broke at all.
💳 The Overlap Nobody Checks: Your Credit Card
Many credit cards already include purchase protection or extended warranty benefits automatically, at no extra cost, for things bought with that card — often adding a full extra year onto the manufacturer’s original warranty, or covering theft and accidental damage for a limited window after purchase.
This is genuinely worth checking in your card’s benefits guide before paying separately for coverage you might already have sitting there, unused, attached to a card you’ve had for years.
🧮 A Simple Gut-Check Before Saying Yes
Two questions, asked honestly, standing right there at the register: what’s the actual cost to repair or replace this item without coverage, and how likely does a failure genuinely feel within the extended period — not how likely does the cashier’s pitch make it sound.
If the warranty cost is a small fraction of either number, it’s a much easier yes.
If it’s creeping up toward a meaningful chunk of the item’s own value, that’s the moment to pause, the same four seconds Marty didn’t take, and actually think it through instead of nodding along.
🔗 Related Reads
- What a Warranty Actually Promises (and What It Doesn’t)
- Extended Auto Warranties: The Sales Pitch vs. the Fine Print
- Appliance Warranties: What’s Typically Covered and For How Long
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
57009
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved