Do You Even Need to File? The Minimum Income Question

Getting a W-2 for a grand total of four dollars and fifty-eight cents raises a legitimate question: does anyone actually have to file a return over that?

Alexa’s career at Bramblewick’s Boutique lasted exactly one shift, ending partway through the second hour when a mannequin she was repositioning took the opportunity to fall directly into a display of scented candles, several of which did not survive. She was asked, with great politeness, not to come back.

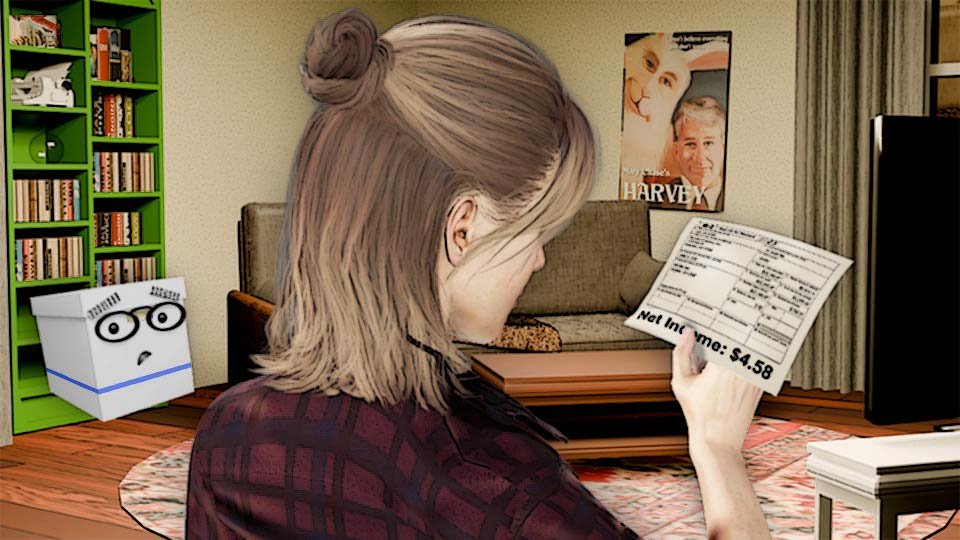
Months later, a W-2 arrived in the mail anyway, because apparently even one catastrophic hour of employment generates paperwork, and it listed her total earnings from Bramblewick’s with the same clinical precision the IRS applies to everyone: Net Income, $4.58.

She stared at it for a genuinely long time, less because of the amount and more because of the question it raised — does a person now have to become A Taxpayer, with all the seriousness that implies, over four dollars and fifty-eight cents?

Doc’s answer, delivered without even looking up: almost certainly not, but the actual rule is worth knowing anyway, because it’s not as simple as “small number, ignore it.”

💵 The Actual Rule: It’s About Gross Income, Not How Official You Feel

The IRS sets a minimum gross income threshold each year — tied to that year’s standard deduction, which is a flat amount the IRS lets everyone subtract from their income before any tax applies.

Below that minimum income amount, a single filer generally isn’t required to file a federal return at all.

For a single filer under 65 in a recent tax year, that number has been sitting somewhere in the neighborhood of $14,000 to $15,000. That figure isn’t solid: it gets adjusted for inflation every year, so the exact number for whatever year you’re actually filing is worth a quick check on IRS.gov rather than trusting a number from an old post, this one included.

The concept, though, doesn’t change: below that threshold, filing generally isn’t required. $4.58 isn’t close to it. $4.58 isn’t close to the threshold for a country with a substantially smaller economy.

🧮 Yes, All Your W-2s Get Added Together

The threshold applies to your total gross income across every job for the year, not job by job.

If Bramblewick’s had been Alexa’s only income all year, $4.58 obviously isn’t a filing situation. But if she’d also had a real, full-time job earning real money, that $4.58 gets added to the pile — it doesn’t magically stay separate just because it came from a different employer, or just because the job itself ended in a candle-related incident. It’s a small distinction that matters more the more jobs are actually in the picture.

💸 The Twist: Filing Below the Threshold Can Still Get You Money Back

Here’s the part that actually matters even at $4.58: check Box 2 on the W-2, labeled “Federal income tax withheld.” If an employer withheld even a small amount of federal tax from a paycheck — which can happen automatically based on how a W-4 was filled out, regardless of how tiny the job turned out to be — that money doesn’t come back on its own.

Filing a return, even one that wasn’t required, is the only way to actually claim a refund of tax that was already withheld. Nobody’s suggesting a full tax return over pocket change, but it’s worth the thirty-second check: withheld money sitting in Box 2 is owed back to you, and it stays exactly where it is, unclaimed, until someone files for it.

🧑‍💻 Self-Employment Income Plays by a Different, Much Lower Rule

This entire threshold conversation applies to W-2 wage income.

Self-employment or freelance income — the kind reported on a 1099 instead — works differently and kicks in at a much lower bar: generally, $400 or more in net self-employment earnings for the year. That amount creates a filing requirement on its own, regardless of the regular income threshold, because that’s also the mechanism that triggers self-employment tax.

It’s a completely different conversation from a $4.58 W-2, but worth knowing which category any given dollar actually falls into before assuming the same rule covers both.

✅ The Actual Takeaway

A single W-2 for $4.58 is nowhere near the income threshold that requires filing a return — that part isn’t actually in question. What is worth thirty seconds: check Box 2 for any federal tax withheld, since that’s the one situation where filing anyway pays literally.

Remember that multiple jobs get added together toward the threshold, and that self-employment income runs on its own, much lower rule entirely.

Alexa’s tax filing status, for the record, remained exactly what it was before the W-2 showed up: not required, and not particularly interested in scented candles either.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56003

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
1099 vs. W-2: What Changes When You’re a Contractor

Getting paid as a contractor instead of an employee changes a lot more about your taxes than just which form shows up in January.

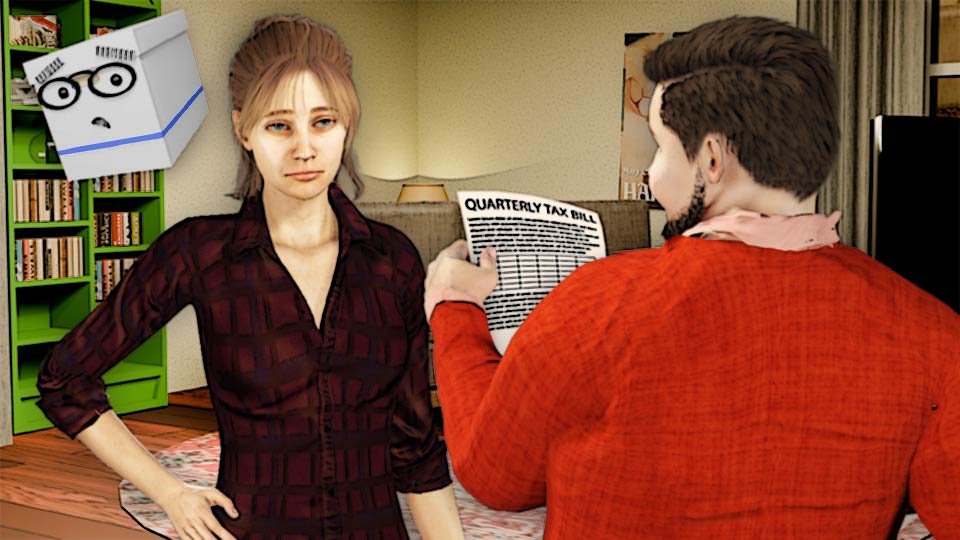
Alexa took on a freelance web design project for a local business — a real client, a signed agreement, a few thousand dollars — got paid the full amount with nothing subtracted from it, and felt briefly thrilled at seeing a bigger number land in her account than she’d have gotten from a regular paycheck.

This isn’t about her weekend selling cookies at the street fair; nobody’s sending a tax form over a card table and a cash box. A 1099 shows up when a single client pays you $2,000 or more in a year — a real, ongoing arrangement, not a one-off sale. Months after that freelance check cleared, Alexa got a genuinely unpleasant surprise about exactly how much of that money she still actually owed.

📄 The Core Difference: Who’s Withholding What

A W-2 employee has taxes automatically withheld from every paycheck by their employer — federal, state, Social Security, Medicare, all handled before the money even reaches you.

A 1099 contractor gets paid the full amount, with nothing withheld at all — the entire tax responsibility sits with you, not an employer, which is exactly the gap that catches new freelancers off guard.

💰 Self-Employment Tax: The Big One Nobody Warns You About

As a W-2 employee, your employer pays half of your Social Security and Medicare taxes, and you pay the other half automatically through withholding.

As a 1099 contractor, you’re responsible for both halves yourself — called self-employment tax, and it adds up to a genuinely significant chunk (currently around 15.3%) on top of regular income tax.

📅 Why You Likely Owe Quarterly, Not Just Once a Year

Since nothing’s being withheld throughout the year, the IRS generally expects contractors to pay estimated taxes quarterly rather than one lump sum at filing time — covered in its own dedicated post, but worth knowing upfront that “just pay it all at tax time” can trigger its own separate penalty.

🧾 The 1099 Form Itself: What It Actually Is

A 1099 (specifically 1099-NEC for most freelance and contract work) is the form a client sends you, similar in spirit to a W-2.

It summarizes what they paid you over the year — but with nothing already withheld, unlike its W-2 counterpart. It’s genuinely helpful when you’re doing your taxes, as it reflects what the client reported to the IRS.

💼 The One Genuine Upside: More Deductions Available

Contractors can deduct legitimate business expenses — a home office, equipment, certain software, mileage — in ways a regular W-2 employee generally can’t.

It’s the same laptop and the same work either way; the difference is that contractor income runs through a Schedule C, where the IRS lets business costs get subtracted before anything is taxed, and current law simply doesn’t extend that same deduction to a W-2 employee’s unreimbursed work expenses.

It doesn’t erase the self-employment tax burden, but it’s a real, worthwhile offset worth understanding and tracking carefully throughout the year, not scrambled together in April.

🧮 The Practical Habit Worth Building From Day One

Setting aside a real percentage of every contractor payment — commonly recommended around 25-30% — into a separate savings account the moment it arrives, specifically earmarked for taxes, prevents the exact surprise Alexa ran into.

Treat that portion as never having been fully yours to spend in the first place.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What’s a W-4, and Why Is It Different From a W-2?

One of them you fill out. One of them you receive. They sound alike and do completely different jobs, months apart.

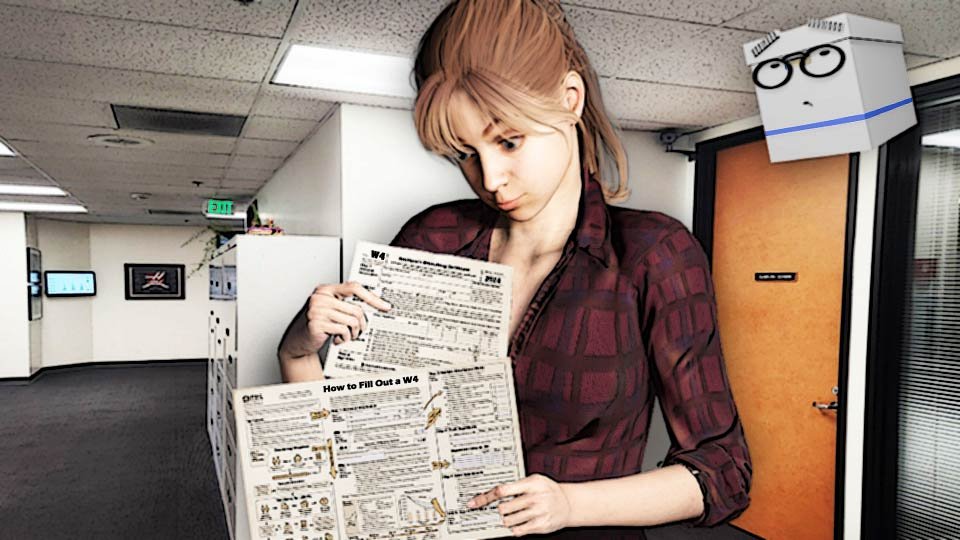
Weeks before Alexa ever stared at that confusingly small paycheck, she was sitting in an HR office on her first day, handed a stack of new-hire paperwork and a pen, filling out a form called a W-4 in roughly ninety seconds flat, mostly by checking whatever box seemed default-ish and moving on to the next page.

Nobody explained what it actually did. She just assumed it was one of those forms, indistinguishable from the parking permit application and the handbook acknowledgment. It was not one of those forms. It was the reason her paycheck looked the way it did.

📝 What a W-4 Actually Is

A W-4 is the form you fill out for a new employer that tells them how much federal income tax to withhold from each of your paychecks.

You typically fill it out once, on day one of a job, and it stays in effect until you submit a new one.

Think of it as a set of instructions you’re handing your employer: “based on my situation, here’s roughly how much tax to hold back from each check, so I’m not stuck owing a huge amount — or overpaying by a huge amount — next April.”

⚔️ The Actual Difference: A W-4 Is Input, a W-2 Is Output

Here’s the distinction that gets muddled constantly, because the names are one digit apart:

  • A W-4 is something you fill out and submit, at the start, before any of your paychecks even exist yet.
  • A W-2 is something your employer sends you, after the fact, every January, summarizing everything that actually happened the prior year — total wages earned, total tax already withheld. One sets expectations going in.

The other reports results coming out. They’re not two versions of the same form. They’re opposite ends of the same twelve months.

✍️ What’s Actually On a W-4

A few key sections:

  • your filing status (single, married, and so on)
  • an optional adjustment if you or a spouse work multiple jobs
  • a section for dependents if you have any (this can reduce how much gets withheld, since it estimates certain tax credits in advance)
  • a line for any extra flat amount you’d like withheld beyond the standard calculation, if you specifically want a bigger cushion.

Most first-time filers with one job and no dependents can fill out the first section and skip most of the rest — it’s built to scale down in complexity the simpler your situation actually is.

🔄 Yes, You Can Change It Later

A W-4 isn’t a permanent, one-time decision carved into the job itself. You can submit a new one to your employer any time your situation changes — a second job, a marriage, a kid, or simply realizing last year’s refund was way bigger or smaller than you expected and wanting to adjust for next year.

Most payroll or HR systems let you update it in a couple of minutes, no drama required.

🧮 Why Getting It Slightly Wrong Isn’t a Real Emergency

If a W-4 withholds too little, your paychecks feel a bit bigger throughout the year, and you owe more when you file.

If it withholds too much, your paychecks feel a bit smaller, and you get a larger refund back later.

Either direction is an imbalance, not a mistake with consequences — the money isn’t lost either way, just timed differently. It’s worth getting reasonably close to accurate, but a W-4 filled out in a ninety-second blur on day one, like Alexa’s, isn’t something to lose sleep over.

It’s something you can simply go fix.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Should You Actually Keep Those Shoebox Receipts?

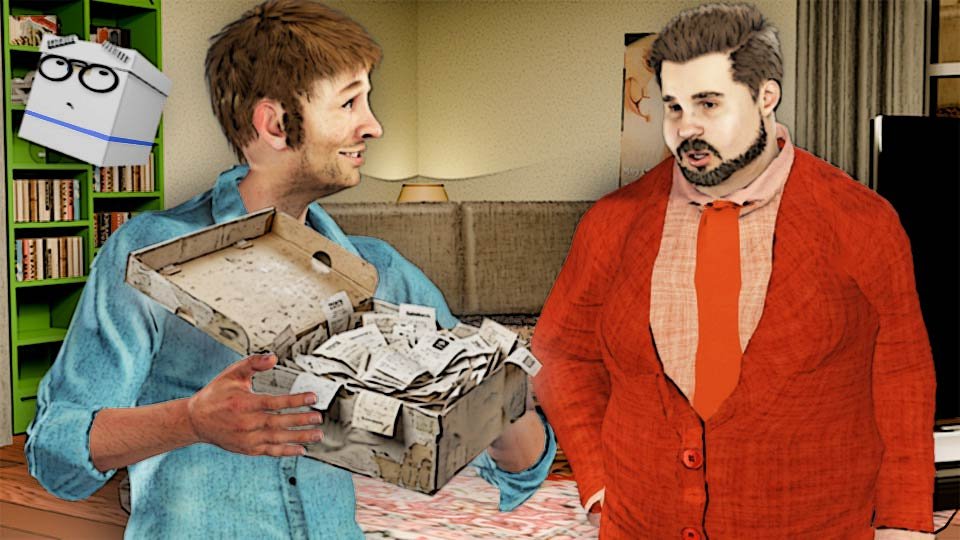
That shoebox of grocery receipts feels responsible. For most tax filers, it’s mostly just a shoebox.

Marty has a shoebox. Inside the shoebox is roughly eight months of grocery receipts, a gas station receipt from a trip he doesn’t remember taking, and a receipt for a haircut, all saved with the grim determination of a man who once heard the phrase “keep your receipts for taxes” and has been quietly panicking about it ever since. He has no idea which of these, if any, actually matter come April. The honest answer is going to disappoint the shoebox.

🧾 What a Simple W-2 Filer Actually Needs

If you have one job, get a regular paycheck, and take the standard deduction — which is the overwhelming majority of first-time filers — the list of documents you actually need is short.

Your W-2, which your employer sends you every January, summarizing everything already withheld.

A 1099-INT, if a bank account earned you interest (covered in its own post, since it surprises almost everyone the first time it shows up).

And that’s close to the entire list. Not a shoebox. A folder, maybe two documents thick.

🛒️ Why the Grocery Receipts Genuinely Don’t Matter Here

Grocery receipts, gas receipts, a haircut receipt — none of these are tax-deductible for a standard, W-2, take-the-standard-deduction filer.

Those are personal living expenses, not business expenses, and the IRS draws a clean line between the two. The confusion almost always comes from somewhere else: someone hears “keep your receipts” in the context of running a business, freelancing, or itemizing deductions, and the advice gets repeated without the context attached.

Marty absorbed the instruction. He never got the fine print explaining who it was actually for.

⚖️ When Receipts Actually Do Matter

A few real situations where keeping receipts genuinely counts: self-employment or freelance income, where business expenses can be deducted against what you earned.

Itemizing deductions instead of taking the standard one — something that only makes sense once your deductible expenses (mortgage interest, large medical bills, charitable donations) add up to more than the standard deduction would give you automatically, which is a higher bar than most people expect.

Or a home office used specifically and exclusively for a side business. None of these describe someone with one job and a shoebox of grocery receipts.

🗃️ What’s Actually Worth Filing Away, Even If It’s Boring

Your W-2 and any 1099s, obviously. Records of any large life event with a tax angle — buying a home, a big charitable donation, a significant medical expense.

And it’s worth keeping a copy of whatever you actually file each year for at least three years afterward, since that’s generally how far back the IRS can look if a question ever comes up.

None of that requires a shoebox. It requires one folder, refreshed once a year.

✅ The Actual Takeaway

Being responsible with your paperwork is a good instinct. It’s just pointed at the wrong pile right now.

The shoebox can be retired, or at least demoted to “where I keep receipts in case I need to return something,” which is a perfectly good use for a shoebox. It was just never doing much for you at tax time.

🛠️ Gear Worth Having

Sooez 13-Pocket Accordion File Organizer — one folder, one pocket per deduction category, filled in gradually all year — the exact opposite of scrambling through a shoebox of receipts every April.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56005

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Why Your First Paycheck Was Smaller Than You Thought

You did the math on your hourly rate and it doesn’t match what actually landed in your account. Here’s exactly where the difference went.

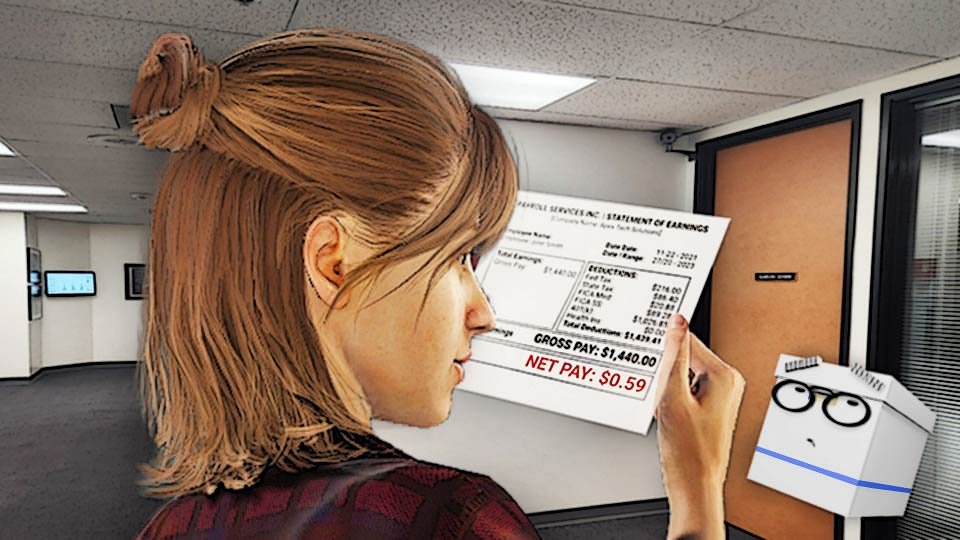
Alexa did the math before her first paycheck even arrived. $18 an hour, roughly 80 hours over two weeks, that’s $1,440, simple multiplication, she’d checked it twice.

The number that actually showed up in her account was $1,140. She stared at her phone for a solid minute, genuinely wondering if her employer had made a mistake, or possibly forgotten how multiplication works.

Neither. That missing $300 didn’t vanish. It went to exactly six specific places, all at once, all with their own names, none of which anyone had ever explained to her.

💸 The Two Numbers That Don’t Match: Gross vs. Net

Gross pay is the number you did the math on — hours times your rate, or your stated salary divided out per paycheck. It’s the full, pre-deduction amount your work actually earned.

Net pay, sometimes called “take-home pay,” is what’s left after everything gets subtracted out, and it’s the number that actually lands in your bank account.

Every single deduction on a pay stub is the gap between those two numbers, itemized. Nobody’s shortchanging you. The paycheck is just reporting both numbers, and only one of them was ever going to be spendable.

🏛️ FICA: The One Everybody Pays, No Exceptions

FICA stands for the Federal Insurance Contributions Act, and it funds two specific federal programs: Social Security and Medicare.

It’s 7.65% of your gross pay, combined — 6.2% to Social Security, 1.45% to Medicare — taken automatically from essentially every paycheck, at every job, regardless of income level or how much you like the idea.

This isn’t optional, isn’t a mistake, and isn’t specific to your employer. It’s federal law, applied the same way to nearly every paycheck in the country.

📋 Federal (and Sometimes State) Withholding

This is the government collecting an estimate of the income tax you’ll owe for the year, a little at a time, instead of asking you for one enormous payment next April.

The amount withheld is based on what you filled out on a form called a W-4 when you were hired — covered in its own post, since it’s worth understanding on its own — which tells your employer roughly how much to hold back from each check.

If you live in a state with its own income tax, a separate state withholding gets taken out too, right alongside the federal amount.

🧾 Other Things That Might Be Missing Too

Depending on your specific job, a few other deductions might be quietly doing their part: a health insurance premium, if you’ve opted into a plan through work.

A retirement contribution, like a 401(k), if you signed up for one.

These aren’t hidden fees — they’re things you actually chose, usually during onboarding paperwork that felt like a blur at the time, which is exactly why they’re worth double-checking on your first real pay stub rather than assuming you remember every box you checked.

🧮 A Quick Walkthrough With Real Numbers

Take that $1,440 gross paycheck. FICA takes roughly $110 (7.65%). Federal withholding might take another $140 or so, depending on the W-4 on file and how much was actually earned. State withholding, if applicable, takes a smaller additional slice.

Add it up, and a net paycheck landing somewhere around $1,140 to $1,200 isn’t a mistake at all — it’s the completely normal, expected result of gross pay meeting the standard set of federal deductions everyone runs into.

✅ The Actual Takeaway

The gap between gross and net isn’t a red flag, a clerical error, or your employer quietly skimming off the top. It’s the predictable sum of a handful of specific, named deductions, every one of which shows up right there on the pay stub if you actually read it line by line.

Once you know what each line is for, the smaller number stops feeling like a mystery and just becomes the number you were always actually going to take home.

🔗 Related Reads

  • Reading Your W-2 Without Panicking
  • How Tax Refunds Actually Work (It’s Not Free Money)
  • How to File Your Taxes

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56008

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How to File Taxes (When You’ve Never Done It Before)

Filing taxes for the first time feels like a foreign language wrapped around a deadline. Here’s what your actual options are, and how to pick one.

Alexa knows, in a vague and slightly panicked way, that she’s supposed to “do her taxes” sometime before April 15. She does not know what that sentence actually means as an action. Does she mail something? Is there a website? Does a man in an office do it for her while she sits very still? She has a W-2 sitting in a drawer that she’s pretty sure is important, and a level of dread usually reserved for jury duty.

Let’s fix that, one piece at a time.

📋 What “Filing Taxes” Actually Means

Here’s the plain-English version, no drawer-based dread required: filing taxes means telling the IRS how much you earned last year, and letting the math work out whether you paid the right amount along the way.

Your employer already withheld an estimated chunk of tax from every paycheck all year.

Filing is just the part where you find out if that estimate was too high, too low, or right on the nose.

Too high, and you get a refund — the government hands back the extra you overpaid. Too low, and you owe the difference. Either way, this is the appointment where the actual number gets settled.

There are several ways to accomplish that reckoning and arrange for either the refund or the tax payment. Let’s look at each one.

🗺️ Wait, Federal AND State? Nobody Mentioned That

Here’s the part that ambushes almost everyone the first time: “filing your taxes” isn’t one errand. It’s two. Federal taxes go to the IRS. State taxes go to your own state’s department of revenue, a completely separate government office with its own form, its own rules, and its own deadline (usually the same day, but not guaranteed). Nine states skip income tax entirely — Texas and Florida among them — so if you live in one of those, congratulations, you’ve got one fewer errand than everyone else. Everybody in the other forty-one states has two.

This is also exactly where “free tax filing” quietly turns into a bit of a bait and switch.

IRS Free File — the actual federal free-filing program, available if your income falls under roughly $84,000 to $89,000 — covers your federal return at no cost.

State coverage depends entirely on which partner software you pick. Some throw in a free state return. Most don’t. TurboTax and H&R Block both run this exact playbook: free federal return to get you in the door, then a state filing fee once you’re already halfway through and invested in finishing.

If avoiding that fee actually matters to you, a few real options exist.

  • FreeTaxUSA files federal for free regardless of income, and charges a flat, genuinely small fee for state — nowhere near the $60-plus the big-name software tends to charge.
  • VITA, the free in-person IRS volunteer program, covers both federal and state for people under a certain income level.
  • Plenty of states also run their own free e-file portal directly through their own department of revenue, worth a quick check before assuming you have to pay a software company at all.
  • And if you’re in the military, MilTax covers federal plus several state returns free, no income limit attached.

None of this is required reading if you’re fine paying the state fee and moving on with your life. But knowing it’s a choice, and not just how things are, is worth having before you’re staring at a checkout screen wondering why “free” suddenly has a price tag.

🖥️ Option 1: IRS Free File

The IRS partners with several tax software companies to offer completely free federal filing, as long as your income falls under a set threshold (it adjusts most years, so it’s worth checking the current number rather than trusting an old one).

It walks you through the same interview-style questions as the paid software, just without the price tag at the end. If your tax situation is simple — one job, one W-2, nothing exotic — this is often the easiest place to start.

💻 Option 2: Commercial Tax Software

TurboTax, H&R Block’s online product, and a handful of others all work roughly the same way: you answer plain-English questions, type in numbers straight off your W-2, and the software quietly does the actual math and form-filling in the background.

It’s built for someone who’s never done this before, which, no offense, is exactly Alexa’s entire situation. It usually costs something once your return gets past the simplest tier, but for most people it’s a genuinely manageable, low-drama way to get through the process solo.

🧑‍💼 Option 3: An Actual Human Tax Preparer

A CPA or an enrolled agent (a tax professional specifically licensed to represent you in front of the IRS) can do the whole thing for you, in person or remotely, and answer questions in real time instead of leaving you to Google them at 11 p.m. It costs more than software.

It’s genuinely worth it if your situation has any real complexity to it — freelance income, multiple jobs, a big life change like buying a home or getting married. If your tax return is basically one W-2 and nothing else, this is probably more firepower than you need.

🤝 Option 4: Free, In-Person Help (VITA)

The IRS also runs a program called VITA — Volunteer Income Tax Assistance — offering free, in-person help from IRS-certified volunteers, for people under a certain income level.

If cost is the main thing standing between you and a preparer, this is worth looking into before assuming a preparer is out of reach entirely.

📄 What You Actually Need Before Starting, No Matter Which Option You Pick

Each of these documents either document your income last year, or your identity. Leaving one out of your filing will delay the processing of your return.

  • Every W-2 from every job you had last year — yes, even the one you quit in March.
  • Any 1099 forms, if you did freelance or gig work anywhere.
  • Your Social Security number.
  • Last year’s tax return, if you filed one, since it speeds up a lot of the software’s auto-fill.
  • And your bank account information, if you want a refund deposited directly instead of waiting on a paper check.

⏰ The Deadline That Actually Matters

Federal taxes are due April 15 most years. An extension is available if you need more time to file the paperwork — but it’s important to know that an extension to file is not an extension to pay. If you owe money, that’s still due on the original deadline, extension or not.

✅ How to Actually Decide Which One Fits You

One job, one W-2, nothing complicated? Free File or commercial software will handle it in under an hour.

Freelance income, multiple jobs, or a major life change this year? A human preparer earns their fee.

Tight on money and the situation’s simple? VITA exists exactly for this.

There’s no prize for picking the hardest option — just pick the one that matches how complicated your year actually was, and get it done.

🙅 FYI: The Guy Down the Hall Is Not a Tax Professional

Every apartment building has one. A neighbor, a coworker, a friend’s cousin who “basically does taxes” and is happy to walk you through it over coffee, for free, out of pure generosity. That generosity is real. The advice underneath it is a coin flip.

Tax law changes most years — sometimes small tweaks, sometimes real ones — and “what worked for my return” doesn’t automatically mean “what’s correct for yours.” Your friend down the hall doesn’t know your specific income sources, your specific state, or whether the trick that saved him money last year even still applies this year. He’s not being dishonest. He’s just confidently repeating something that was true once, for a completely different tax situation than the one sitting in front of you.

None of this means never listen to a friend who mentions something useful — a tip about VITA, a heads-up that a state has its own free e-file portal, that’s the good kind of word-of-mouth. The line is between “here’s a resource you might not know about” and “let me just do your taxes for you real quick.” The first one is a favor. The second one is a liability neither of you actually wants, however good the intentions.

🔗 Related Reads

  • Estimated Quarterly Taxes: Who Actually Needs to Pay Them
  • What Happens If You File Late
  • How Tax Refunds Actually Work (It’s Not Free Money)

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56011

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved