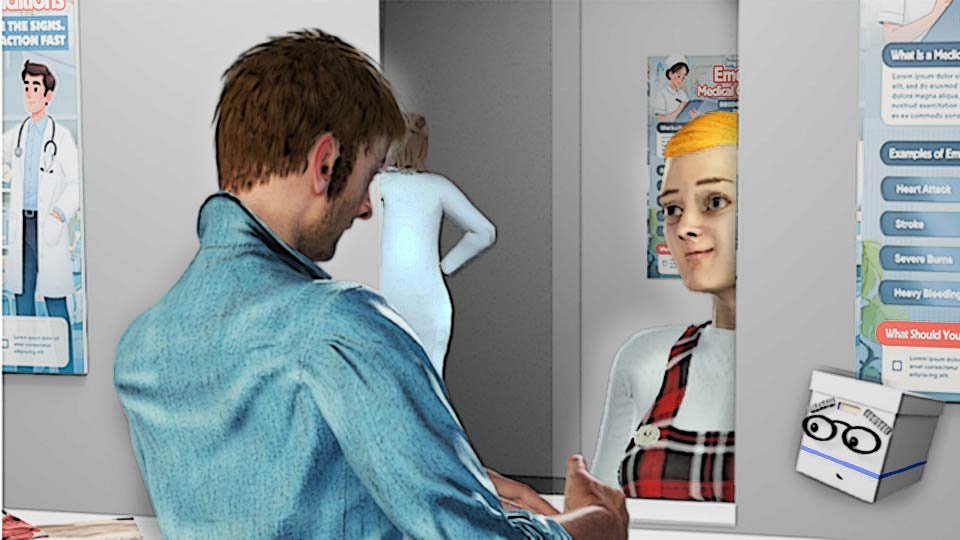
Marty is standing at an urgent care reception window, alone, for the first time in his life, holding his insurance card out like it’s a magic key that should unlock the whole visit for free.
The receptionist, who is also making eyes at him in a way he has not fully registered because he is currently panicking about money, says the number “$25” out loud.
Marty blinks. He has insurance. He pays for it every month. Why does he also owe money right now, standing here, before anyone’s even looked at the ankle he’s fairly sure he sprained? The honest answer is that he’s about to meet three different insurance words, only one of which applies to this exact moment, and nobody ever sat him down to explain the difference.
💵 The Copay: The One That Applies to Marty, Right Now
A copay is a flat, fixed fee you pay at the time of a visit — $25, $40, whatever your specific plan sets for that type of visit — regardless of anything else going on with your insurance.
It doesn’t care whether you’ve met your deductible.
It doesn’t care whether this is your first doctor visit of the year or your tenth.
It’s simply the toll for walking through the door for this specific kind of appointment, due today, at the window, before you’re called back.
That’s exactly why the receptionist is asking Marty for $25 right now, insurance card already on file and everything — the copay isn’t a sign that something’s wrong with his coverage. It’s just how his plan is built.
🏥 The Deductible: The Bigger Number Working in the Background
A deductible is the amount you have to pay out of your own pocket, across the whole year, before your insurance starts covering a bigger share of your bills.
Think of it as a threshold that has to be crossed once, not a fee charged every visit.
A $1,500 deductible means you’re paying close to full price for covered care until your out-of-pocket total hits $1,500 for the year — after that, your insurance starts picking up much more of the tab.
Copays sometimes count toward that total and sometimes don’t, depending on the specific plan, which is worth checking rather than assuming either way.
📊 Coinsurance: The Percentage Split That Shows Up After the Deductible
Coinsurance is a percentage split between you and your insurance company, and it only kicks in after your deductible has actually been met.
A common setup is 80/20 — insurance pays 80% of a covered bill, you pay the remaining 20%.
So, say the procedure is $2,500. You pay $1,500 to meet the deductible. After that, your insurance pays 80% of the remaining $1,000, which leaves you owing $200 instead of the full amount. On that procedure, your insurance picked up $800 you would otherwise have had to pay.
Coinsurance is the reason two people with “good insurance” can still owe wildly different amounts for the same procedure — it depends entirely on where each of them stands against their own deductible that year.
🧩 Why All Three Can Apply to the Same Plan
Here’s the part that actually trips people up, Marty included.
These three are separate mechanisms that can all exist on one single insurance plan, kicking in at different moments. The copay is due today, at this visit, full stop.
The deductible is a running yearly total, quietly tracking every dollar you’ve paid out of pocket so far.
Coinsurance only shows up once that deductible’s been crossed, splitting whatever comes next by percentage instead of a flat fee.
A single visit might only ever touch one of the three — which is exactly Marty’s situation right now, standing at a window, owing a flat $25 and nothing more complicated than that.
❓ What to Actually Do If You Don’t Have the $25 on You
Say so.
Genuinely, that’s the whole move.
Front desk staff hear “can you bill me for the copay” on a regular basis, and most offices have a completely normal process for it — they’ll bill you directly, or let you pay after the visit rather than before it.
It’s not an embarrassing conversation, no matter how much a nervous twenty-something at a reception window might imagine otherwise, distracted receptionist notwithstanding.
🔗 Related Reads
- What a Deductible Actually Means
- What “In-Network” Actually Means and Why It Matters
- Reading Your Policy’s Declarations Page
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
51007
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved