Marty’s insurance agent rattled off three words. Liability. Collision. Comprehensive. Maybe some combination of all three.
She said it with the breezy confidence of someone who’d explained this a thousand times before. She moved on before Marty could admit something important. He genuinely could not tell those three words apart. He picked one at random.
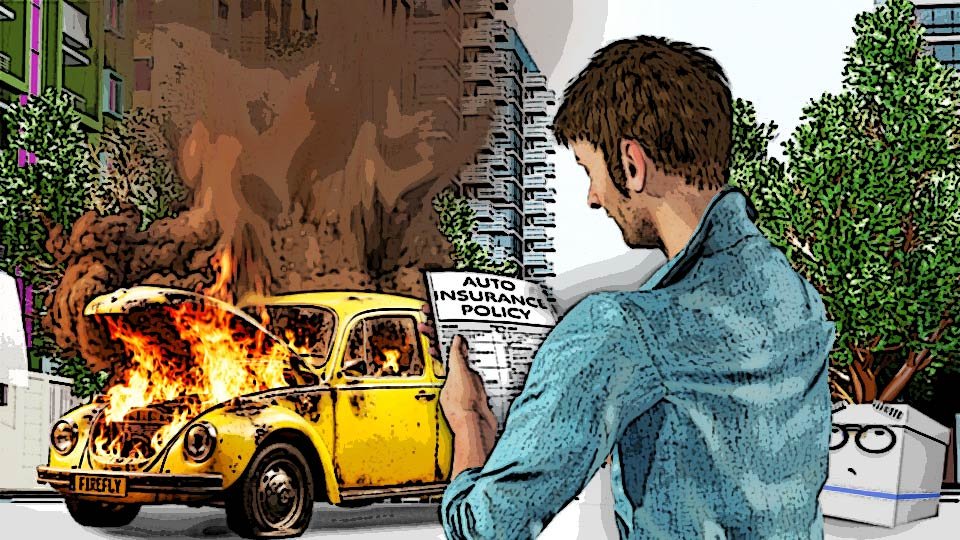
He is now standing on a sidewalk watching his car burn, holding a folder of paperwork, quietly hoping he picked the right one.
⚖️ Liability: Covers the Other Person, Not You
Liability coverage pays for damage or injury you cause to someone else. Their car. Their property. Their medical bills.
It only applies if you’re at fault in the accident.
Here’s the part that trips people up: it does not pay for your own car’s damage at all. Not a dollar of it. This is also the one coverage nearly every state legally requires you to carry, at some minimum level, just to be allowed to drive.
💥 Collision: Covers Your Car, In a Collision
Collision coverage pays to fix your own vehicle after it hits something. Another car. A guardrail. A tree.
It doesn’t matter who was actually at fault. This is the coverage that answers one specific question: who pays to fix my car after I hit something.
☔ Comprehensive: Covers Everything Else That Can Happen to a Car
Comprehensive covers damage to your car from causes other than a collision. Theft. Vandalism. Fire — yes, like Marty’s, currently, on the sidewalk.
A tree branch falling on it. Hail. Hitting a deer. It’s genuinely the broadest of the three. Think of it as covering the whole category of “things that happen to a car that isn’t even driving at the time.”
🧩 Why People Say “Full Coverage”
“Full coverage” isn’t an official policy type. You can’t call an agent and ask for it by that exact name.
It’s just informal shorthand for carrying all three — liability, collision, and comprehensive — together. That combination covers the widest range of situations. The name is a description, not a product.
🚗 Why a Car’s Value Actually Matters to This Decision
Collision and comprehensive both come with their own deductibles. They both come with their own monthly costs, on top of liability. That cost is worth weighing against what your actual car is worth.
Carrying full collision and comprehensive on a car worth $1,500 total means something specific: you could be paying meaningful monthly premiums to protect a car that wouldn’t cost much to simply replace outright.
Marty’s Beetle, the one that burned up right before his eyes, might have been exactly this kind of car. We’ll never know now.
🔗 Related Reads
- What a Deductible Actually Means
- What to Do Immediately After an Accident, Insurance-Wise
- Why Your Premium Goes Up (Even When You Haven’t Filed a Claim)
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
51006
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved