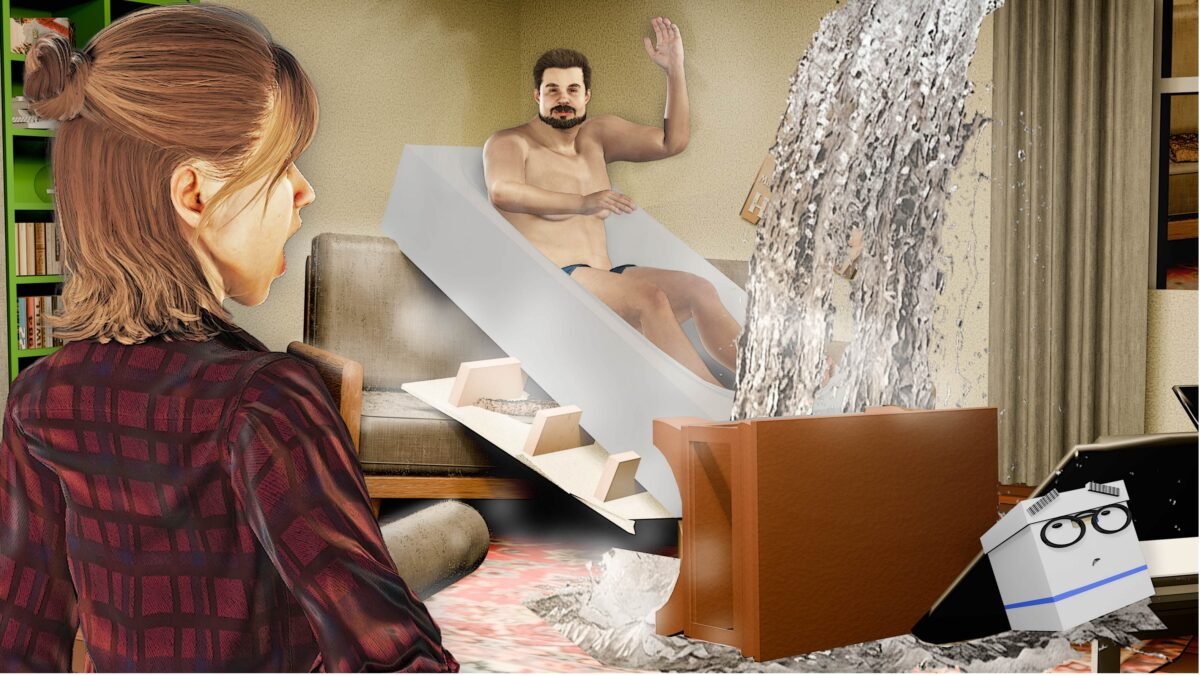
Alexa’s ceiling produced a bathtub. Not metaphorically — an actual bathtub, at an angle, with her upstairs neighbor Carl riding it down like a waterslide, shirtless, waving, apparently under the impression that this qualified as dropping by to apologize.
His bathtub had overflowed for reasons he described as “a whole thing,” and now her ceiling had a hole in it roughly bathtub-shaped, her rug was soaked through, and she was on the phone with her insurance company, panicking, while the calm, unbothered voice on the other end used the word “claim” roughly nine times in ninety seconds without ever quite explaining what that actually meant or what happened next.
Carl, meanwhile, was still standing in her living room in swim trunks. Let’s sort out the insurance part first.
📞 Step One: You Report It
A claim starts with you telling your insurance company something happened — by phone, app, or website, depending on the company.
You’ll describe what occurred (a neighbor’s bathtub flooded through your ceiling, for instance, an example chosen entirely at random), roughly when it happened, and roughly what was damaged or lost.
This first call isn’t the whole process. It’s just opening the door to it, the very first domino, not the resolution.
🔢 You Get a Claim Number — Write This Down Immediately
Every claim gets assigned a specific reference number, and every single future conversation about it — every phone call, every follow-up, every time you get transferred to someone new — will start with someone asking you for that number.
Write it down the second you get it, somewhere you won’t lose it. A claim number is the difference between a thirty-second follow-up call and starting the entire soaked-rug, shirtless-neighbor explanation over again from scratch with a total stranger.
🕵️ Step Two: An Adjuster Gets Involved
An insurance adjuster is the person whose actual job is investigating the claim — reviewing whatever documentation you provide, sometimes inspecting the damage in person, sometimes working entirely from photos, and ultimately determining how much the insurance company should actually pay out.
Think of them as the translator standing between “something bad happened to my ceiling” and an actual dollar figure the policy is willing to cover. They didn’t witness Carl’s descent. They only know what you show them.
📸 Why Your Own Documentation Matters So Much Here
Photos of the damage — the hole in the ceiling, the water stain spreading across the rug, the actual bathtub sitting at an angle in the middle of the living room, if it’s still there. Carl doesn’t necessarily figure into these pictures.
Receipts for anything damaged or ruined. A written timeline of what happened and when, while it’s still fresh, not reconstructed from memory two weeks later. All of this genuinely speeds up and strengthens a claim.
An adjuster working from clear photos and a clear timeline moves faster, and more accurately, than one working only from a panicked phone call and a secondhand description of a man in swim trunks.
💰 Step Three: The Settlement
Once the adjuster finishes reviewing everything, the insurance company offers a settlement — the actual amount they’ll pay, with your deductible already subtracted from it.
This isn’t automatically a final, take-it-or-leave-it number handed down from on high. You’re allowed to negotiate or push back if the offer genuinely seems to undervalue what was lost or damaged, the same way you’d question any bill that looked wrong.
⏱️ How Long This Actually Takes
Simple, well-documented claims can resolve in days to a couple of weeks.
More complex ones — significant damage, disputes over what actually caused it, disagreements over value — can take considerably longer.
There’s no single universal timeline that applies to every claim equally, which is exactly why holding onto that claim number for follow-up calls matters as much as it does; a claim that’s taking a while isn’t necessarily a claim that’s gone wrong.
🚫 If a Claim Gets Denied, That’s Not Automatically the End
Claims do get denied — sometimes for legitimate policy reasons, sometimes because of a genuine mistake, missing documentation, or paperwork that got filed incorrectly somewhere along the way.
Most insurers have a formal appeals process built for exactly this. It’s worth actually reading the denial reason carefully rather than assuming it’s final, and pursuing it if the reasoning genuinely seems wrong.
A denial is a checkpoint, not necessarily the last word.
🔗 Related Reads
- Renters Insurance: What It Covers and What It Doesn’t
- What a Deductible Actually Means
- What to Do Immediately After an Accident, Insurance-Wise
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
51008
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved