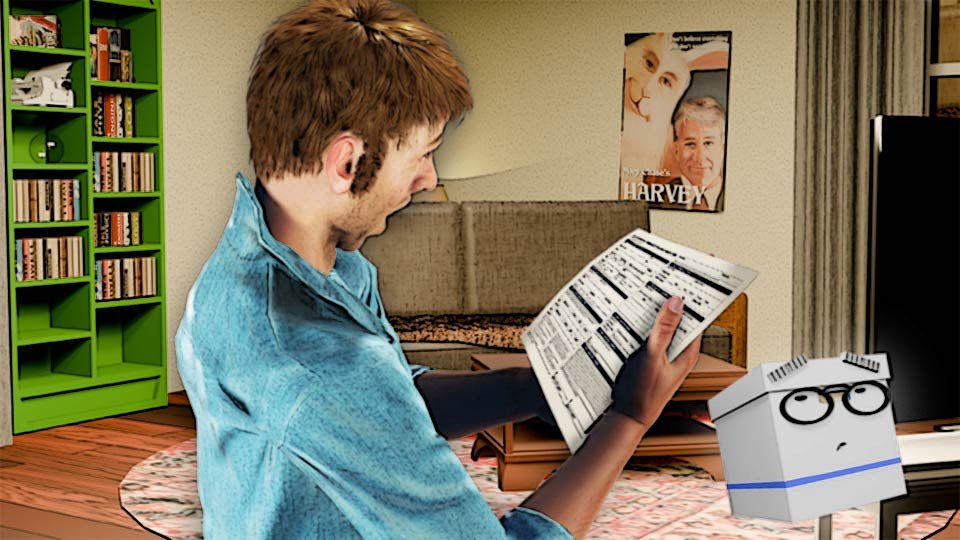
Marty sat down with an actual paper application, pencil in hand, and stared at Section 2: Financial Details like it had just asked him to disclose state secrets. Annual income. Employer. Years employed. Monthly rent.
It felt like the kind of form you’d need a briefcase full of documents to complete.
He did not own a briefcase. He owned a pencil and a mounting sense of dread. Neither turned out to be necessary, though the pencil helped.
🪪 Applicant Information — What It Actually Wants
Name, address, phone number, date of birth, and your Social Security number. That last one is usually the part that makes people pause, hovering the pencil, wondering if handing it over on a form is a mistake.
It isn’t.
The credit card company, called “the issuer,” needs it for two specific reasons: confirming you’re actually who you say you are, and pulling your credit report.
That credit repor is the whole reason this section exists at all. Without it, they have no file to check and nothing to approve you against.
💵 Financial Details — The Question That Feels Like a Trap
Annual income, employer name, how long you’ve worked there, and your monthly rent or mortgage payment.
This is the section that makes an application feel like an audit, but it’s really just one calculation in disguise: how much money is coming in, versus how much is already going out.
That ratio is called debt-to-income, and it’s the main thing an issuer uses to decide both whether to approve you and what starting credit limit makes sense. It’s not a judgment on your life choices. It’s just math they need before they hand you a number.
📄 Do You Need Your Tax Returns for This?
No — and this is worth saying plainly, because it’s the exact thing that makes people freeze up before they’ve even started.
For a standard personal credit card, income is self-reported. You write the number down.
You don’t attach a W-2, a pay stub, or a tax return to prove it.
The issuer may occasionally verify income after approval, especially for a high limit (a card that has, maybe, $5,000 or more available), but that’s the exception, not the standard process.
Marty didn’t need a briefcase. He needed the number, from memory, and honesty.
🔁 Balance Transfer Options — You Can Skip This One
This section asks about moving an existing balance from another credit card onto this new one, usually to take advantage of a lower promotional interest rate on the new card.
If this is genuinely your first credit card, you don’t have an existing balance anywhere to transfer. Leave the whole box blank and just move on. It isn’t relevant to you yet, and nothing about your application suffers for skipping it.
🎨 Card Design Preferences — The Only Part With No Wrong Answer
Which design you want the physical card to look like.
That’s it.
No financial mechanics hiding underneath this one, no calculation, no consequence. This is the one section on the entire form where Marty could relax, and possibly the only part of the whole process anyone designed to actually be fun.
✍️ Signature and Consent — What You’re Actually Agreeing To
Signing authorizes two things: that the information you provided is accurate, and that the issuer can pull your credit report to make a decision.
That credit pull is called a hard inquiry. For most applicants, it causes a small, temporary dip in an existing score, although you won’t — but have an existing score to dip.
With no credit history yet, this inquiry isn’t shaving points off anything. It’s the first entry in a file that’s currently empty, the actual starting gun on the score he doesn’t have yet.
Either way, it’s a completely normal, expected part of applying for any credit, not a red flag or a mistake. Signing isn’t the scary part of the form. It’s just the part where you confirm everything above it was true.
🔗 Related Reads
- Secured vs. Unsecured Credit Cards: Which One You Actually Need
- Building Credit From Zero: The Actual First Steps
- What APR Actually Means (and Why It’s Not the Whole Story)
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
52006
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved