Alexa applied for a regular credit card, got denied for having “insufficient credit history,” and felt the specific, circular frustration of being told she needed credit history to get credit, with no apparent door leading in. There’s a door. It’s just a slightly different one than she was knocking on.
🛋️ Secured vs. Unsecured: What’s the Difference?
Picture two strangers who show up at your door on the same afternoon, both wanting to borrow $300, both with an honest face and a suspiciously specific repayment plan.
The first guy hands you a driver’s license, shakes your hand, and promises to pay you back $27.50 a month for the next twelve months — $330 total, meaning you walk away $30 richer for helping him out. Nice guy. You believe him. You have, however, no actual leverage beyond his word and a mild sense that he seemed trustworthy.
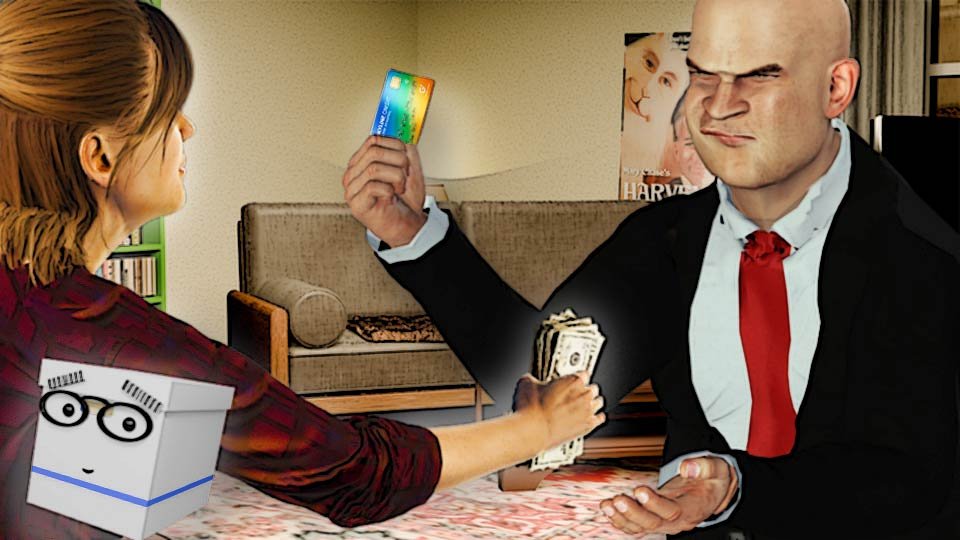
The second guy wants to buy your couch, also for $300, and offers the exact same deal — $27.50 a month for a year. Except he takes the couch home with him today, right now, sofa cushions and all, on nothing but that same promise to pay.
Here’s the entire difference in one sentence: if guy number two stops paying, you know exactly where your couch is, and you’re legally entitled to go get it back. If guy number one stops paying, you’ve got a phone number, a memory of a firm handshake, and absolutely nothing else.
That’s secured versus unsecured credit in a nutshell. A secured line is backed by real, repossessable property — the couch, a car, a house. An unsecured line is backed by nothing but your word that you’ll pay it back, which is exactly why lenders charge more interest for it and check your credit history more carefully before handing it over. Collateral isn’t a technicality. It’s the entire reason one of these guys sleeps easier than the other.
🔓 Unsecured: The “Normal” Credit Card
An unsecured credit card is what most people picture when they think of a “credit card” — no deposit required, the credit limit is based purely on the bank’s assessment of your creditworthiness.
The catch: banks and credit card companies typically require an existing credit history before they’ll approve you for one in the first place — which is exactly the wall Alexa ran into.
The second catch: because they’re lending you money on nothing but your word, banks and credit card companies usually charge a higher interest rate on that line of credit than they would on a secured one.
🔒 Secured: The Same Card, With a Deposit Attached
A secured credit card requires a refundable security deposit upfront — commonly matching your credit limit, so a $300 deposit gets you a $300 limit.
That deposit is the bank’s insurance policy against someone with no track record yet — not a punishment, just how a bank manages risk with an unknown quantity.
It’s the same idea as the couch. If you don’t pay, the bank keeps your $300 — the equivalent of you collecting the couch.
🪜 Why Secured Cards Are Genuinely the Smart Starting Move
A secured card reports to the credit bureaus exactly the same way an unsecured one does — on-time payments build real credit history either way.
It’s specifically designed as a stepping stone: use it responsibly for a while, and many issuers will actually convert it to an unsecured card automatically, refunding your original deposit once they do.
The downside: you have to come up with $300 first.
Now, you’re not paying a $300 fee that just vanishes. You’ll get that money back eventually, and in the meantime it’s sitting there as your actual credit limit, doing its job.
And it’s available to you on your new credit card – you’ll most likely have at least a $300 credit limit. Use the card to buy your groceries and stuff, just paying off the card at the end of the month.
But you do need to have that $300 up front.
💵 What Happens to the Deposit
As long as the account stays in good standing, the deposit isn’t a fee — it’s held, and returned to you either when the card converts to unsecured or when you close the account with no outstanding balance.
It’s genuinely your money the entire time, just serving as collateral rather than sitting in a regular savings account.
🎯 The Actual Decision
If you have zero credit history, a secured card is very often the realistic starting point, not a lesser option — plenty of people with excellent credit today started on exactly this kind of card.
If you already have some credit history through another route (a co-signed account, a student loan, being an authorized user on a parent’s card), you may already qualify for unsecured directly.
🔗 Related Reads
- Building Credit From Zero: The Actual First Steps
- Applying for Your First Credit Card: What Actually Matters
- What a Credit Score Actually Measures
ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.
52004
©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved