Understanding Your Employee Handbook (Without Reading the Whole Thing)

Nobody actually reads the entire employee handbook cover to cover. Here’s what’s genuinely worth knowing, and where to find it fast when it matters.

Alexa was handed a seventy-page employee handbook on her first day. She signed the acknowledgment form confirming she’d “read and understood” the entire thing about ninety seconds after receiving it.

Now, mathematically, she’d have had to read roughly one page every 1.3 seconds with full comprehension.

She has never opened it again since. If you’re picturing a woman speed-reading a legal document like it’s a flipbook, you understand the joke and also, unfortunately, the industry standard.

😅 The Honest Truth: Nobody Reads the Whole Thing Cover to Cover

Here’s the secret nobody says out loud: a seventy-page handbook was never actually built to be read front to back like a novel.

It’s a reference document — something you’re meant to search when a specific question comes up, not something you’re expected to have memorized before lunch on day one.

So what does that signature on the acknowledgment form actually mean, if not “I absorbed all seventy pages”?

Mostly, it’s the company confirming you received access to the document and were told it exists, not that you’ve internalized it. Nobody’s actually fooled by the ninety-second read. It’s a formality, not a comprehension test.

🏖️ The Sections Genuinely Worth Actually Reading Now

Three categories are worth an actual, real read on day one, not a someday-when-I-need-it read:

PTO and sick leave policy — specifically how it accrues (do you earn it gradually or get a lump sum up front), how to actually request it, and whether there are any blackout periods where time off isn’t approved.

Workplace concern or harassment complaint reporting process — who you’d actually go to, and how that process works, before you’re in a situation where you need it in a hurry.

Remote work or flexible schedule policy, if it’s relevant to your role — the specific rules around it are worth knowing precisely, not roughly, since “probably fine” is a bad standard to operate on.

These three come up often enough, and matter enough when they do, that they’ve earned a real read instead of a look-it-up-later.

🔍 The Sections Worth Knowing Exist, Even If You Don’t Read Them Yet

Code of conduct, dress code, technology and email usage policy, and disciplinary procedures all fall into a different bucket: you don’t need every clause memorized on day one, but it’s genuinely worth knowing roughly where each of these lives in the document.

That way, if a specific question ever comes up — can I use my work laptop for personal email, what actually counts as a dress code violation — you know exactly where to go look instead of digging through seventy pages cold.

📄 Handbook vs. Contract: An Important, Easy-to-Miss Distinction

Most employee handbooks include a line stating, in some form, that the handbook is not a binding contract and that the company can change any policy in it at any time.

That’s an important distinction, easy to miss buried in the fine print: the policies inside are genuinely useful day-to-day guidance, but they don’t carry the same legal weight as your actual signed employment contract or offer letter.

If the two ever conflict, the offer letter is the document that matters more.

🔎 How to Actually Use It Going Forward

Treat the handbook like a reference manual, not required reading.

When a specific question comes up — how many sick days do I actually have left, what’s the real process for reporting an issue — that’s the moment to go look it up, using the search function if it’s a digital copy, rather than trying to hold all seventy pages in memory from day one just in case.

That’s what it’s there for.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

58001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Reading an Offer Letter Before You Say Yes

A verbal “yes” feels official. It legally isn’t. Here’s what actually binds you — and what to check before you sign anything.

Alexa got the call, heard a number she liked, and said an excited, immediate yes right there on the phone — the kind of yes that comes with a little fist pump nobody on the other end could see.

It wasn’t until days later, holding the actual written offer letter, already having told her parents, her roommate, and possibly a stranger at the coffee shop, that she read the real details of the job she’d apparently already committed her whole personality to.

📞 Why the Verbal Offer Isn’t the Real Document

A verbal offer is real and it’s meaningful — nobody’s lying to you on that call. But it’s also not the enforceable version. Legally, an offer of employment generally doesn’t become binding until it’s in writing and signed; a phone call is an expression of intent, not a contract. The HR person on the phone isn’t wrong, exactly — they’re just not the document that actually governs the job.

Which means it’s genuinely fine, even smart, to say “I’m thrilled, I’d love to see everything in writing before I give my final answer” instead of treating the call itself as the moment you’re locked in. The written offer letter is the company’s actual side of the deal — read it like it matters, because legally, it’s the part that does.

💰 Salary: The Actual Number, and How It Actually Arrives

Confirm the exact base salary, and whether it’s written as an annual figure or an hourly rate — those read very differently on paper and it’s worth doing the math yourself rather than assuming. Check how often you’re actually paid: weekly, biweekly, or monthly all mean a very different-looking bank balance on any given week, even at the identical annual number.

Also confirm your employment classification: exempt or non-exempt. Non-exempt means you’re paid hourly and legally entitled to overtime pay for hours worked beyond 40 in a week; exempt usually means a fixed salary with no overtime pay, regardless of how many hours the job actually takes. It’s a genuinely important distinction, and it’s usually spelled out in a single line you could easily skim past.

Whatever the letter says, check it against what you were actually told over the phone or in the interview. Misunderstandings between a verbal number and the final written one aren’t rare, and nobody enjoys discovering the gap on their first payday.

📅 Start Date and Employment Type

Make sure the letter specifies an actual, calendar-date start date — not a vague “sometime in the next few weeks,” which isn’t something you can plan a move, a lease, or a two-weeks’-notice around.

Also confirm whether you’re being offered as full-time, part-time, or a contractor — a distinction that sounds like paperwork but genuinely changes your entire tax situation and whether you’re eligible for benefits at all (worth a full read in its own right, since it’s a bigger topic than one line in an offer letter can cover). Don’t assume the version you discussed out loud is the version that made it onto the page.

🏥 Benefits: What’s Actually Promised in Writing

Health insurance eligibility, and when it actually kicks in — some companies have a waiting period of a month or more after your start date before coverage begins, which matters a lot if you’re timing anything medical around a job change.

Retirement plan details, including whether the company matches any of your own contributions.

Paid time off policy, including whether it’s a lump sum granted up front or something that accrues gradually over the year.

Check that all of it roughly matches what was discussed verbally. The offer letter is the version you’ll actually be able to point back to later, so it’s worth getting right now rather than just assuming it’s correct.

📝 The Fine Print Worth Actually Reading

A few terms that often show up here, sometimes as a separate attachment, and are worth understanding rather than skimming past in the excitement of an accepted offer:

At-will employment means either you or the company can end the job at any time, for almost any legal reason, with no advance notice required on either side — it’s the standard arrangement in most states, not a red flag on its own, just worth knowing it’s there.

A non-compete restricts you from taking a job with a competing company for some period of time after you leave. A non-disclosure agreement (NDA) restricts you from sharing confidential company information, during your employment and often after. Both are common and often standard — the goal isn’t to be alarmed by them, it’s to actually know what you signed instead of finding out later.

❓ What to Do If Something’s Unclear or Different Than Expected

Asking a direct, simple question before you sign — “I want to confirm this reflects what we discussed about X” — is a completely normal, professional move, not an awkward one.

It’s far easier to clarify or adjust something before your signature is on the page than to raise a discrepancy after you’ve already accepted. Companies expect these questions. Asking one doesn’t cost you the job — it’s just due diligence, the same kind you’d want from them.

🛠️ Gear Worth Having

Post-it Flags Multi-Pack — flag salary, start date, and benefits terms on a printed copy so you can compare it line by line against what was actually discussed verbally.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

58003

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Budget Billing: How It Works and Whether It’s Worth It

Budget billing promises the same bill every month, all year long. Here’s what’s actually happening behind that flat number.

Alexa’s utility company offered something called “budget billing,” promising the same predictable payment every single month regardless of season, which sounded, on its face, like a magic trick.

Wait, how exactly does a company that bills based on actual usage also promise you a flat number, month after month, forever?

📊 The Actual Mechanism

Budget billing (sometimes called “level pay” or “average billing”) estimates your annual usage based on past history, divides it into equal monthly payments, and bills you that flat amount every month.

That’s regardless of whether that specific month’s actual usage was higher or lower.

You’re not paying less overall; you’re paying the same amount spread more evenly across the year instead of swinging with the seasons.

⚖️ It’s Not Free Money — It’s Smoothing, Not Saving

Now, budget billing doesn’t reduce your total annual cost at all.

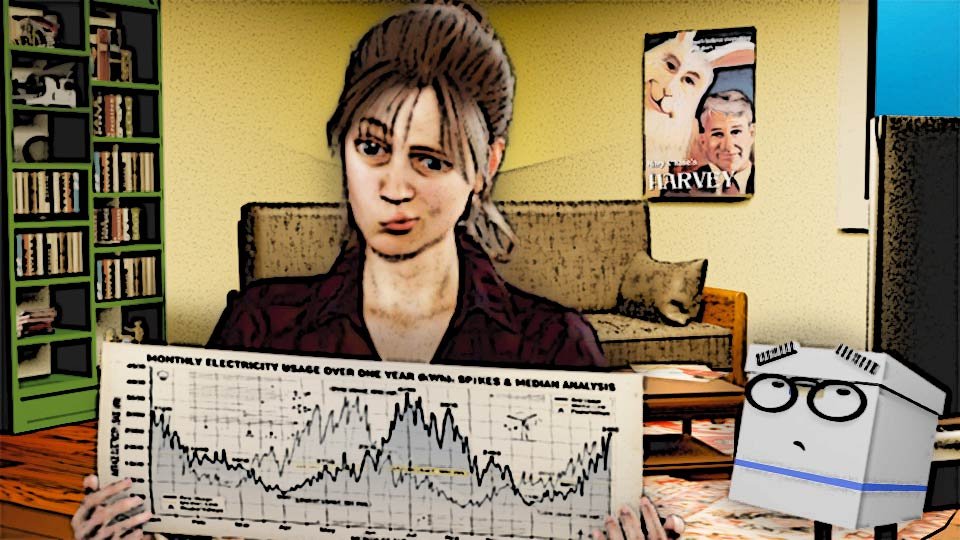
If you run the AC for the whole summer you’ll see a super high charge under normal billing. Conversely, you’ll switch it off in the winter, and your bill will be much, much lower.

Budget billing charges you the same, flat rate, winter or summer. You pay a less than regular billing in the summer, but you pay more in the winter. You’re paying an average that works out to roughly the same total either way.

Budget billing just changes when you pay it, not how much.

🔄 The “True-Up”: Where the Math Gets Reconciled

Most budget billing plans include a periodic true-up, commonly once a year, comparing what you actually paid against what you actually used.

If you paid more than you used, you might get a credit; if you paid less, you may owe the difference in one larger catch-up payment.

That’s worth knowing this reconciliation exists, so it isn’t a surprise when it eventually arrives.

✅ Who This Genuinely Helps

This is great program for anyone who finds a predictable, steady monthly number easier to budget around than a bill that swings significantly by season.

It’s genuinely useful for smoothing out the practical difficulty of a June bill that’s triple a January payment.

The yearly total ends up about the same either way, but it eliminates potential cash-flow crunches when the higher summertime bills come due.

⚠️ The One Real Risk Worth Knowing

If your actual usage habits change significantly, like taking on a new roommate, or running the AC through a much hotter summer than usual, you might find a a larger-than-expected true-up bill down the line.

Your monthly utility bill will show you actual usage compared to the budget billing amount, so you can actually keep tabs on what to expect when the true-up time comes.

🔗 Related Reads

  • Why Your Utility Bill Changes So Much Month to Month
  • Setting Up Autopay Without Losing Track of What You’re Paying
  • What Happens If You Miss a Utility Payment

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

53007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Setting Up Autopay Without Losing Track of What You’re Paying

Autopay quietly solves the late-fee problem and quietly creates a new one: forgetting what you’re even paying for anymore.

Marty set up autopay on every single bill he had within the same triumphant week, felt an immediate and genuine sense of relief at never having to think about a due date again. Nice going, Marty!

Then, roughly four months later, realized he never knew exactly how much was in his checking account because so many things were automatically pulling from it.

When he went to look at his list of autopay items is when he realized he’d never made one.

✅ Why Autopay Is Genuinely Worth Setting Up

Autopay removes the single most common cause of a late fee — simply forgetting — by handling payment automatically on the due date every time.

For routine, predictable bills, like your rent and flat-fee payments like the Internet garbage bills, it’s a genuinely low-risk, high-value habit that protects both your credit and your wallet from an easy, human mistake.

🕳️ The Real Tradeoff: Losing the Monthly Check-In

Manually paying a bill, however annoying, forces a small moment of actually looking at the amount each month.

Autopay removes that friction — which is the whole point.

But it also removes your connection to that payment. You lose that natural moment where you’d notice a bill has quietly crept up, or that you’re still paying for something you don’t even use anymore.

📋 The Fix: A Master List, Checked Occasionally

Keeping that connection with, and therefore control of, your bill-paying system is actually quite important. And, it’s not impossible.

Simply maintain one simple running list of everything on autopay: what it is, roughly how much it should be, and which account it pulls from. That’s it.

Glance at it every couple of months and check it against your actual bank statement. This bill should have been paid on that date, and it should have been roughly this month. Just a five-minute check – here’s this, here’s that, okay, all good.

This preserves nearly all of autopay’s convenience while keeping the one habit (actually knowing what you’re paying for) that automation quietly erodes.

If you mentally set a trigger event, like the arrival of the statement, it becomes automatic in your brain. When you read the statement, check the autopays.

💰 Scheduling to Avoid the Overdraft Risk

When you set up your autopays, make sure you spread them out across the month.

Multiple autopay charges hitting around the same date, especially if your account balance is tight, could actually trigger an overdraft situation.

Shoot for scheduling your autopays a couple of weeks away from big items, like your rent. Don’t schedule an autopay for the 28th of the month, thinking that’s as far from the rent as you can get. The 28th is just a few days ahead of the next month’s rent!

🔔 Alerts: The Middle Ground

Most banks and billers let you turn on a notification specifically for autopay charges — a text or email the moment one processes.

This gets you most of autopay’s convenience while still creating a small, real-time paper trail, rather than autopay running invisibly in the background indefinitely.

Although it seems like an annoying text when you get it, it could turn out to be quite important, giving you a chance to shift things around before a crisis occurs.

🛠️ Gear Worth Having

Bill Payment Tracker Journal — one physical place listing everything on autopay, so “what exactly am I paying for” has an actual answer instead of a shrug.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

53009

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Direct Deposit: Setting It Up and What Can Go Wrong

Direct deposit feels like magic once it’s working. Setting it up wrong is the reason a paycheck sometimes just doesn’t show up.

Marty started a new job, filled out the direct deposit form in what felt like thirty confident seconds, and then spent his entire first payday anxiously refreshing his banking app, watching a paycheck that was supposedly already sent simply refuse to appear.

💸 What Direct Deposit Actually Is

Direct deposit is your employer (or anyone else paying you regularly) sending money straight into your bank account electronically, instead of handing you a physical check to deposit yourself.

No trip to the bank, no waiting for a check to clear — just money that shows up on payday, automatically, once it’s set up correctly.

🧾 The Form Nobody Explains Before Handing It To You

A direct deposit form asks for your bank’s routing number (identifying which bank you use) and your specific account number (identifying which account, specifically, at that bank). Two different numbers doing two different jobs.

Many employers will also just ask for a voided check instead, since a check already has both numbers printed on it in the right place.

To void a check, just write “VOID” across it in large letters. Unlike regular checks, a “voided” check can never be used as an actual payment, only as a reference for those numbers.

🔀 Checking vs. Savings — Pick On Purpose

The form will ask which account to deposit into.

Most people choose checking, since that’s the account built for regular activity.

Some employers let you split a paycheck between multiple accounts automatically, which is a genuinely handy way to send a small slice straight into savings before you ever see it and get tempted to spend it.

⏱️ Why the First Payday Is Often Late or Missing Entirely

Setting up direct deposit is super quick, but seeing your paycheck show up in your account isn’t instant

Most companies typically take one full pay cycle to actually activate. That means your very first paycheck might get handed to you in an envelope.

After that, however, the money will simply appear in your account as if out of the blue.

❌ The Mistakes That Actually Cause Real Delays

These are some simple, and somewhat common, mistakes people make:

  • A transposed digit in the account or routing number
  • using an old account that’s since been closed
  • accidentally selecting savings on a form that doesn’t support direct payroll deposits into it

All fixable with a quick correction and a resubmitted form, but all worth double-checking before submitting rather than after your paycheck goes missing.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

50005

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How to Write a Check (Yes, Really)

Checks feel like a relic from another era, right up until the one moment you actually need to write one and have no idea how.

Alexa’s landlord doesn’t accept anything except a paper check for rent, a piece of information that arrived roughly one hour before rent was due, alongside the deeply unwelcome discovery that Alexa had genuinely never written a check in her entire life and had no idea where to even begin.

📝 Why This Skill Refuses to Fully Die

Plenty of landlords, small businesses, and even some larger institutions still only accept checks, often for reasons ranging from tradition to genuinely lower processing fees on their end.

Rare enough that most people never learn it properly, common enough that eventually, usually with no warning, you’ll need to.

🖋️ Step 1 – Always Use Ink

Never write a check in pencil — and while you’re at it, skip the erasable pen too. Pencil can be smudged away or altered without a trace, and “erasable” ink is really just ink with a rubber-friendly formula, which means it can be lifted right off the paper the same way. Neither one leaves proof that what you originally wrote is what you actually meant to write.

Ink — regular, boring, permanent ballpoint ink — bonds to the paper instead of sitting on top of it. If someone tries to alter the amount or the payee after the fact, it leaves a visible mark instead of a clean edit. It’s not about penmanship. It’s about making sure the check that gets cashed says the same thing it said when it left your hand.

Blue or black is standard; either works fine, so use whichever’s already in the drawer.

🔢 The Date Line

Top right corner. Just today’s date, written normally.

Nothing tricky here — this is the easy part, and a fine place to build a little confidence before the rest.

👤 “Pay to the Order Of”

This is simply asking who the check is for — the exact name of the person or company getting paid.

Write it exactly as they’d want to deposit it; if your landlord’s company is called “Briarwood Properties LLC,” that’s what goes here, not just “landlord” or a nickname.

🔢 The Dollar Box

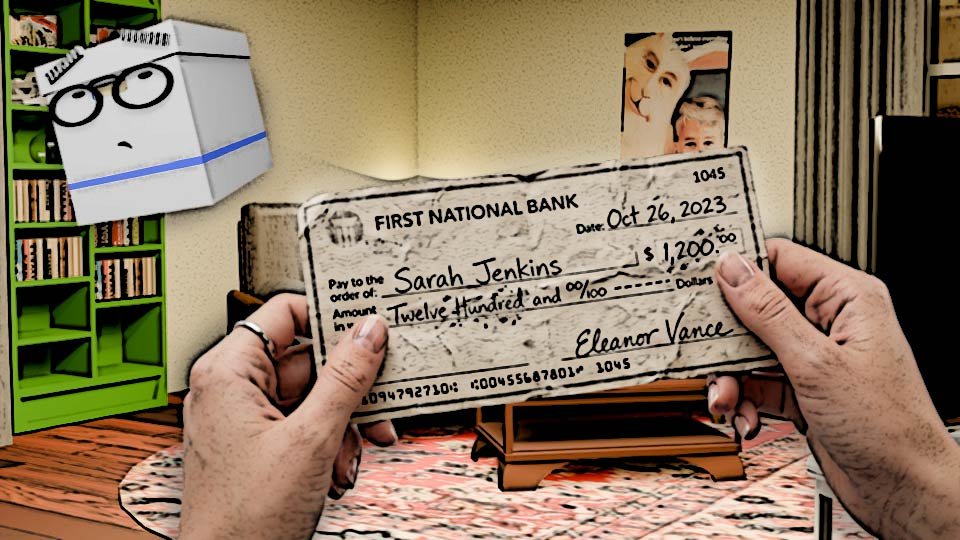
A small box, usually on the right, where you write the amount in numbers — $1,200.00, for example.

Write it close to the dollar sign with no extra space, since that empty space is exactly where a check could be altered by someone with bad intentions.

✍️ The Dollar Line (Yes, You Have to Write It Out in Words Too)

Directly below the “Pay to the Order Of” line, write the same amount out in words: “One thousand two hundred and 00/100.”

This exists specifically as a test for fraud — if the numbers and the words ever disagree, banks are trained to trust the words, so writing this clearly actually matters.

Draw a line through any remaining blank space on this line too, same anti-tampering logic as the dollar box.

📋 The Memo Line

Optional, bottom left, just a short note for your own records — “August rent” or similar. The bank doesn’t care what’s here; it’s entirely for you and whoever’s reading their own bank statement later.

✒️ Your Signature

Bottom right. This is the line that actually authorizes the payment — an unsigned check is just an elaborate, useless piece of paper.

📒 Recording It Somewhere, So Future You Isn’t Confused

Before handing the check over, jot down the amount, the date, and who it went to — either in a physical check register or just a notes app.

Checks can take days to actually process, and without a record, it’s easy to forget you already spent that money and accidentally count it twice in your head.

🛠️ Gear Worth Having

CASMONAL A5 Checkbook Register — the actual physical record of every check you write, so you’re never guessing what’s already spoken for.

uni-ball 207 Signo Fraud Prevention Gel Pens — ink specifically formulated to resist check washing — the exact kind of thing that makes a real difference on a document meant to move real money.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

50004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved