Filling Out Your First Credit Card Application: What They’re Actually Asking

Applying for a first credit card feels like it should come with an instruction manual. It doesn’t, so here’s one.

Marty sat down with an actual paper application, pencil in hand, and stared at Section 2: Financial Details like it had just asked him to disclose state secrets. Annual income. Employer. Years employed. Monthly rent.

It felt like the kind of form you’d need a briefcase full of documents to complete.

He did not own a briefcase. He owned a pencil and a mounting sense of dread. Neither turned out to be necessary, though the pencil helped.

🪪 Applicant Information — What It Actually Wants

Name, address, phone number, date of birth, and your Social Security number. That last one is usually the part that makes people pause, hovering the pencil, wondering if handing it over on a form is a mistake.

It isn’t.

The credit card company, called “the issuer,” needs it for two specific reasons: confirming you’re actually who you say you are, and pulling your credit report.

That credit report is the whole reason this section exists at all. Without it, they have no file to check and nothing to approve you against.

💵 Financial Details — The Question That Feels Like a Trap

Annual income, employer name, how long you’ve worked there, and your monthly rent or mortgage payment.

This is the section that makes an application feel like an audit, but it’s really just one calculation in disguise: how much money is coming in, versus how much is already going out.

That ratio is called debt-to-income, and it’s the main thing an issuer uses to decide both whether to approve you and what starting credit limit makes sense. It’s not a judgment on your life choices. It’s just math they need before they hand you a number.

📄 Do You Need Your Tax Returns for This?

No — and this is worth saying plainly, because it’s the exact thing that makes people freeze up before they’ve even started.

For a standard personal credit card, income is self-reported. You write the number down.

You don’t attach a W-2, a pay stub, or a tax return to prove it.

The issuer may occasionally verify income after approval, especially for a high limit (a card that has, maybe, $5,000 or more available), but that’s the exception, not the standard process.

Marty didn’t need a briefcase. He needed the number, from memory, and honesty.

🔁 Balance Transfer Options — You Can Skip This One

This section asks about moving an existing balance from another credit card onto this new one, usually to take advantage of a lower promotional interest rate on the new card.

If this is genuinely your first credit card, you don’t have an existing balance anywhere to transfer. Leave the whole box blank and just move on. It isn’t relevant to you yet, and nothing about your application suffers for skipping it.

🎨 Card Design Preferences — The Only Part With No Wrong Answer

Which design you want the physical card to look like.

That’s it.

No financial mechanics hiding underneath this one, no calculation, no consequence. This is the one section on the entire form where Marty could relax, and possibly the only part of the whole process anyone designed to actually be fun.

✍️ Signature and Consent — What You’re Actually Agreeing To

Signing authorizes two things: that the information you provided is accurate, and that the issuer can pull your credit report to make a decision.

That credit pull is called a hard inquiry. For most applicants, it causes a small, temporary dip in an existing score, although for Marty it won’t, since he has no existing score to dip

With no credit history yet, this inquiry isn’t shaving points off anything. It’s the first entry in a file that’s currently empty, the actual starting gun on the score he doesn’t have yet.

Either way, it’s a completely normal, expected part of applying for any credit, not a red flag or a mistake. Signing isn’t the scary part of the form. It’s just the part where you confirm everything above it was true.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52006

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Building Credit From Zero: The Actual First Steps

No credit history isn’t bad credit — it’s just an empty file. Here’s why that empty file matters, and how to actually start filling it in.

Alexa stood in a furniture superstore, picking out her first real couch, feeling genuinely like an adult for possibly the first time in her life. Then the salesman pulled up the financing application, watched her credit page load in front of him, and watched it stay completely, perfectly blank.

He looked at it. He looked at her.

“And, we’re paying in cash today?” he asked, in the tone of a man recalculating his entire afternoon.

She was not, in fact, planning on paying cash today.

She spent the drive home trying to figure out whether “no credit” was the same problem as “bad credit,” since both seemed to produce the exact same polite, faintly pitying rejection.

❓ Wait, Why Does This Even Matter?

Here’s the part nobody explains before you’re standing in a showroom getting quietly judged by a salesman: a credit score isn’t really about whether you’re a good person, or even whether you’re good with money in any broad sense.

It’s a lender’s best guess at one specific question — if they hand you money, how likely are you to pay it back. That number then follows you into a surprising number of rooms that have nothing to do with loans at all.

  • Buying a car, obviously.
  • But also renting an apartment — plenty of landlords pull a credit check before they’ll hand you keys.
  • Getting a cell phone plan without a hefty deposit.
  • Financing that couch, or a laptop, or literally anything at a checkout counter that offers “pay over time.”
  • In some states, even your car insurance premium.
  • Eventually, a mortgage, where a good score can genuinely save you tens of thousands of dollars in interest over the life of the loan.

None of these institutions knows you personally. The score is the introduction they’re working from instead.

An empty credit file doesn’t say “this person is risky.” It says “we have literally no information to work with,” which, to a nervous lender, ends up looking almost the same in practice. The fix isn’t proving you’re trustworthy through sheer force of personality. It’s giving the file something to actually say.

⚖️ No Credit Is Not the Same as Bad Credit

Bad credit means a history of missed payments or other negative marks — a track record, just not a good one.

No credit means there’s no track record at all yet, positive or negative. Lenders treat them similarly in practice, since both look risky from their side, but for completely different reasons.

Bad credit needs repair, which takes real time and real discipline to undo.

No credit just needs a starting point, which is a much easier problem to solve — you’re not fixing a mistake, you’re just making a first entry.

🔒 Starting Point One: A Secured Credit Card

Covered in its own post, but worth repeating here as step one: a secured card reports to the credit bureaus exactly like a regular card does.

It’s specifically designed for people in exactly Alexa’s situation — you put down a deposit that becomes your credit limit, use the card normally, and the on-time payments start building a file where there wasn’t one before.

👥 Starting Point Two: Becoming an Authorized User

If a parent or someone else you genuinely trust has a credit card in good standing, they can add you as an authorized user.

Their account’s positive history can then start showing up on your credit report too, even though you’re not the one primarily responsible for the bill.

It’s a genuinely fast way to build some initial history — provided the primary cardholder’s habits are actually good ones. Being added to someone’s account who pays late or carries a huge balance doesn’t help you. It just hands you their problem with your name attached to it.

💳 Starting Point Three: A Credit-Builder Loan

Some banks and credit unions offer a loan specifically designed for this exact purpose. You “borrow” a small amount that actually sits in a locked savings account the entire time. You make fixed payments on it. The money gets released to you once it’s fully paid off.

The payments themselves report to the credit bureaus the whole way through, building history through a process that’s about as low-risk as borrowing gets, since you’re essentially paying yourself back with extra steps and a paper trail.

🧾 What Actually Matters Once You Have Any Credit at All

On-time payments, every single time, without exception — this is the single biggest factor in the whole system.

Keeping your utilization low, meaning you’re not maxing out whatever limit you’ve got. Owing, say, $4,800 on a credit card with a $5,000 limit is considered very high utilization. Owing, say, $400 on the same card would be low utilization.

And simply letting time pass. Length of credit history is a real, weighted factor in the formula, and there’s no shortcut around it except starting as early as reasonably makes sense, which is exactly what Alexa is doing now, slightly later than she’d have liked, in a furniture store parking lot.

⏳ How Long This Actually Takes

A usable, decent score can build within about six months to a year of responsible activity. A genuinely strong score takes longer than that, since length of history is baked directly into the formula and can’t be rushed no matter how perfectly you behave. There’s no legitimate fast track, no trick, no secret cheat code a finance influencer is hiding from you.

Just a first step, taken as early as it reasonably can be — which, as it happens, is available to Alexa the moment she leaves that showroom.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
RSVP: What It Actually Means and Why Ignoring It Is Rude

RSVP shows up on nearly every invitation and almost nobody knows what the letters actually stand for, let alone why ignoring it is such a problem.

Alexa has seen the letters “RSVP” on essentially every invitation she’s ever received in her entire life. She’s always understood it as a vague, generalized suggestion to “let them know maybe.” She has genuinely never once known it was actually a specific French phrase making a fairly direct request — one she has, by her own count, ignored roughly a dozen times without a flicker of guilt. That’s about to change.

🇫🇷 What the Letters Actually Stand For

RSVP is an abbreviation of the French phrase “répondez s’il vous plaît” — literally, “please respond.” It’s not a vague nudge or an optional nicety. It’s a direct, explicit request for a definite yes or no answer, dressed up in a language most English speakers only half-recognize and have collectively agreed to never actually translate in their heads.

If the four letters said “PLEASE RESPOND” in plain English instead, a lot fewer people would feel comfortable ignoring them.

Same request. Fancier packaging.

😬 Why Not Responding Is Genuinely Inconsiderate, Not Just Distracted

A host planning an event is making real decisions based on how many people actually show up. How much food to prepare. How many chairs to set out. Sometimes a per-person cost they’re personally covering out of their own pocket, especially for something like a catered wedding or a restaurant reservation with a set menu.

Not responding doesn’t just leave a host wondering in some abstract sense — it can genuinely cost them real money, and create real logistical stress, even though it rarely feels that consequential from the guest’s side of the equation.

You forgetting to reply for two weeks is, to you, a minor oversight. To the host, it’s an unfilled seat they can’t plan around.

📅 The Deadline Actually Matters, Not Just the Response

An RSVP date isn’t arbitrary, and it isn’t the host being fussy.

It’s usually tied directly to when they need to finalize a headcount with a caterer, a venue, or a rental company — real deadlines imposed on the host by other businesses, which then get passed down to you as your deadline.

Responding after that date puts a host in an uncomfortable spot: either scramble to accommodate a late addition with a vendor who’s already locked in a number, or have to say no to you.

Neither option is fun for them, and both were avoidable.

✅ What a Complete RSVP Actually Includes

A clear yes or no.

Not “maybe,” not “probably,” not silence that the host is left to interpret.

Respond by the requested date, through whatever method was actually requested — a reply card mailed back, a phone call, a specific RSVP website or app link included in the invitation.

If the host asks you to respond a particular way, that’s not a suggestion either; showing up to the event and verbally confirming in person doesn’t count if they needed the headcount two weeks earlier.

If the invitation asks for a specific headcount — especially in a plus-one situation — include that clearly and by name if you can, rather than leaving the host to guess or chase you down for a follow-up text.

“Yes, I’ll be there” is only half an answer if they also need to know whether you’re bringing someone.

🔁 What to Do If Your Answer Changes Later

If you RSVP yes and then genuinely can’t attend — or the reverse, you said no and something opens up — letting the host know as soon as you know is the actual courteous move, not waiting until the event itself to sort it out.

Plans changing isn’t rude on its own. Everyone’s life shifts sometimes. Leaving a host to find out at the door, or to notice an empty seat they paid for, is the part that’s actually inconsiderate.

❓ A Few Terms Worth Knowing While You’re At It

“Regrets only” means the opposite of a standard RSVP: you only need to respond if you’re NOT coming. Silence is treated as a yes. It’s used for lower-stakes gatherings where the host expects most people to attend and doesn’t want to chase down a hundred separate confirmations. “

RSVP by [date]” is exactly what it says — a hard deadline, not a suggestion of when responses start being welcome.

And a formal invitation that lists specific names on the envelope, without “and guest” anywhere on it, means exactly those people are invited, nobody else — asking to bring someone not listed puts the host in the position of having to say no to your face, which is worth sparing them if you can.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What to Bring When You’re a Dinner Guest

Showing up empty-handed to a dinner feels fine until everyone else is holding something and you’re not. Here’s what’s actually expected.

Marty showed up to a dinner party at a friend’s new apartment with nothing but his usual charming self and a healthy appetite. He clocked it the moment he walked in: every other guest was holding a bottle of wine, a dessert, or something small and wrapped. A silent dress code, apparently, and he’d missed the memo entirely. He has since read this post. You don’t want to learn it his way.

🍷 The Default, Safe Answer: A Bottle of Wine

Wine remains the most common, safest go-to for a dinner party, largely because it works whether or not it actually gets opened that night. A host isn’t obligated to serve whatever you bring — it’s genuinely not rude for them to set it aside for another occasion instead. Bringing wine isn’t really about supplying tonight’s drink. It’s about arriving with something in hand.

If you don’t know wine, you don’t need to become an expert to get this right. A mid-range bottle, somewhere in the $15–$20 range, from an actual wine shop rather than a gas station, covers you fine.

If you genuinely have no idea what to grab, telling the person behind the counter “something for a dinner party, nothing too fancy” gets you a solid answer in about ten seconds. Red is the safer default if you know nothing else about the meal — it pairs more forgivingly across a wider range of dishes than white does, though if you happen to know the meal is fish or something light, white is the better call.

When genuinely unsure, red wins the coin flip.

🚫 What Actually Cancels the “Bring Something” Rule

If the host explicitly says “please don’t bring anything, I’ve got it all covered,” that’s usually a genuine, sincere request, not just politeness. Showing up with something anyway isn’t wrong, but it’s also not expected the way it is by default.

Listening to what a host actually says matters more than defaulting to a rigid rule regardless of what they told you.

🍽️ When It’s a Potluck Instead of a Dinner Party

A genuine potluck is a different animal entirely. Bringing a specific dish is the whole point, not an optional courtesy on top of it.

If unsure which category an invitation falls into, it’s a completely normal, non-awkward question to just directly ask the host.

If it is a potluck, a few things make you a genuinely easy guest to have. Ask if there’s a category already covered — nobody needs five potato salads and zero desserts, and a quick “what’s still needed?” solves that instantly.

Bring something that travels well and doesn’t need the host’s oven or stovetop at the last minute; a dish that needs to be reheated, plated, or finished in someone else’s kitchen adds a chore to their night, not a gift.

And bring something you’ve actually made before, ideally more than once — a potluck is a genuinely bad place to debut a recipe for the first time and discover it doesn’t travel, doesn’t reheat, or just didn’t turn out.

🌸 Non-Consumable Options, If You’d Rather Not Bring a Drink

Flowers, a small plant, or a nice candle all work as alternatives to wine, especially for a host who doesn’t drink or where a food-related gift feels like it might compete with the meal itself.

None of these require nearly the thought people put into agonizing over the “perfect” bottle. A pre-arranged bouquet from any grocery store, handed over at the door, does the job completely.

🍰 If You’re Bringing Food, Ask First

Unless it’s explicitly a potluck, checking with the host before bringing a dish avoids two problems at once: accidentally duplicating something they’ve already planned, and bringing something that clashes with a meal they’ve carefully put together.

It’s also worth asking about any dietary restrictions among the other guests before you show up with something everyone but one person can actually eat. A quick “want me to bring anything specific?” solves all of this cleanly, in one text, before you’ve bought anything at all.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54003

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How to File Taxes (When You’ve Never Done It Before)

Filing taxes for the first time feels like a foreign language wrapped around a deadline. Here’s what your actual options are, and how to pick one.

Alexa knows, in a vague and slightly panicked way, that she’s supposed to “do her taxes” sometime before April 15. She does not know what that sentence actually means as an action. Does she mail something? Is there a website? Does a man in an office do it for her while she sits very still? She has a W-2 sitting in a drawer that she’s pretty sure is important, and a level of dread usually reserved for jury duty.

Let’s fix that, one piece at a time.

📋 What “Filing Taxes” Actually Means

Here’s the plain-English version, no drawer-based dread required: filing taxes means telling the IRS how much you earned last year, and letting the math work out whether you paid the right amount along the way.

Your employer already withheld an estimated chunk of tax from every paycheck all year.

Filing is just the part where you find out if that estimate was too high, too low, or right on the nose.

Too high, and you get a refund — the government hands back the extra you overpaid. Too low, and you owe the difference. Either way, this is the appointment where the actual number gets settled.

There are several ways to accomplish that reckoning and arrange for either the refund or the tax payment. Let’s look at each one.

🗺️ Wait, Federal AND State? Nobody Mentioned That

Here’s the part that ambushes almost everyone the first time: “filing your taxes” isn’t one errand. It’s two. Federal taxes go to the IRS. State taxes go to your own state’s department of revenue, a completely separate government office with its own form, its own rules, and its own deadline (usually the same day, but not guaranteed). Nine states skip income tax entirely — Texas and Florida among them — so if you live in one of those, congratulations, you’ve got one fewer errand than everyone else. Everybody in the other forty-one states has two.

This is also exactly where “free tax filing” quietly turns into a bit of a bait and switch.

IRS Free File — the actual federal free-filing program, available if your income falls under roughly $84,000 to $89,000 — covers your federal return at no cost.

State coverage depends entirely on which partner software you pick. Some throw in a free state return. Most don’t. TurboTax and H&R Block both run this exact playbook: free federal return to get you in the door, then a state filing fee once you’re already halfway through and invested in finishing.

If avoiding that fee actually matters to you, a few real options exist.

  • FreeTaxUSA files federal for free regardless of income, and charges a flat, genuinely small fee for state — nowhere near the $60-plus the big-name software tends to charge.
  • VITA, the free in-person IRS volunteer program, covers both federal and state for people under a certain income level.
  • Plenty of states also run their own free e-file portal directly through their own department of revenue, worth a quick check before assuming you have to pay a software company at all.
  • And if you’re in the military, MilTax covers federal plus several state returns free, no income limit attached.

None of this is required reading if you’re fine paying the state fee and moving on with your life. But knowing it’s a choice, and not just how things are, is worth having before you’re staring at a checkout screen wondering why “free” suddenly has a price tag.

🖥️ Option 1: IRS Free File

The IRS partners with several tax software companies to offer completely free federal filing, as long as your income falls under a set threshold (it adjusts most years, so it’s worth checking the current number rather than trusting an old one).

It walks you through the same interview-style questions as the paid software, just without the price tag at the end. If your tax situation is simple — one job, one W-2, nothing exotic — this is often the easiest place to start.

💻 Option 2: Commercial Tax Software

TurboTax, H&R Block’s online product, and a handful of others all work roughly the same way: you answer plain-English questions, type in numbers straight off your W-2, and the software quietly does the actual math and form-filling in the background.

It’s built for someone who’s never done this before, which, no offense, is exactly Alexa’s entire situation. It usually costs something once your return gets past the simplest tier, but for most people it’s a genuinely manageable, low-drama way to get through the process solo.

🧑‍💼 Option 3: An Actual Human Tax Preparer

A CPA or an enrolled agent (a tax professional specifically licensed to represent you in front of the IRS) can do the whole thing for you, in person or remotely, and answer questions in real time instead of leaving you to Google them at 11 p.m. It costs more than software.

It’s genuinely worth it if your situation has any real complexity to it — freelance income, multiple jobs, a big life change like buying a home or getting married. If your tax return is basically one W-2 and nothing else, this is probably more firepower than you need.

🤝 Option 4: Free, In-Person Help (VITA)

The IRS also runs a program called VITA — Volunteer Income Tax Assistance — offering free, in-person help from IRS-certified volunteers, for people under a certain income level.

If cost is the main thing standing between you and a preparer, this is worth looking into before assuming a preparer is out of reach entirely.

📄 What You Actually Need Before Starting, No Matter Which Option You Pick

Each of these documents either document your income last year, or your identity. Leaving one out of your filing will delay the processing of your return.

  • Every W-2 from every job you had last year — yes, even the one you quit in March.
  • Any 1099 forms, if you did freelance or gig work anywhere.
  • Your Social Security number.
  • Last year’s tax return, if you filed one, since it speeds up a lot of the software’s auto-fill.
  • And your bank account information, if you want a refund deposited directly instead of waiting on a paper check.

⏰ The Deadline That Actually Matters

Federal taxes are due April 15 most years. An extension is available if you need more time to file the paperwork — but it’s important to know that an extension to file is not an extension to pay. If you owe money, that’s still due on the original deadline, extension or not.

✅ How to Actually Decide Which One Fits You

One job, one W-2, nothing complicated? Free File or commercial software will handle it in under an hour.

Freelance income, multiple jobs, or a major life change this year? A human preparer earns their fee.

Tight on money and the situation’s simple? VITA exists exactly for this.

There’s no prize for picking the hardest option — just pick the one that matches how complicated your year actually was, and get it done.

🙅 FYI: The Guy Down the Hall Is Not a Tax Professional

Every apartment building has one. A neighbor, a coworker, a friend’s cousin who “basically does taxes” and is happy to walk you through it over coffee, for free, out of pure generosity. That generosity is real. The advice underneath it is a coin flip.

Tax law changes most years — sometimes small tweaks, sometimes real ones — and “what worked for my return” doesn’t automatically mean “what’s correct for yours.” Your friend down the hall doesn’t know your specific income sources, your specific state, or whether the trick that saved him money last year even still applies this year. He’s not being dishonest. He’s just confidently repeating something that was true once, for a completely different tax situation than the one sitting in front of you.

None of this means never listen to a friend who mentions something useful — a tip about VITA, a heads-up that a state has its own free e-file portal, that’s the good kind of word-of-mouth. The line is between “here’s a resource you might not know about” and “let me just do your taxes for you real quick.” The first one is a favor. The second one is a liability neither of you actually wants, however good the intentions.

🔗 Related Reads

  • Estimated Quarterly Taxes: Who Actually Needs to Pay Them
  • What Happens If You File Late
  • How Tax Refunds Actually Work (It’s Not Free Money)

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56011

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How to Actually Address an Envelope (Return Address, Recipient, Stamp)

An envelope has a very specific place for everything, and almost nobody ever taught you where. Here’s the actual layout.

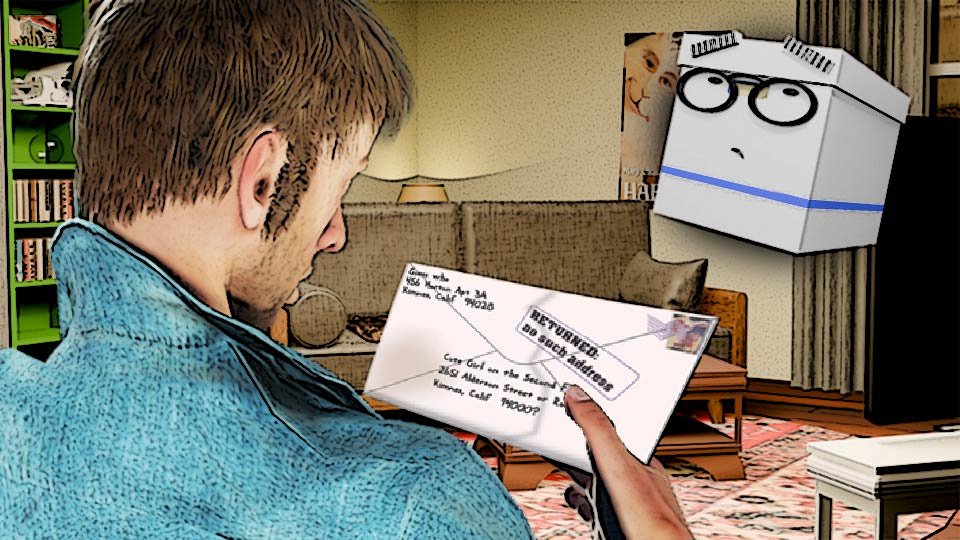
Marty needed to mail an actual physical letter for the first time in what felt like a decade, held a blank envelope in his hands, and realized with genuine alarm that he had no idea which corner anything went in — a task he was fairly sure he’d learned once, in childhood, and had since let quietly evaporate.

📬 The Recipient’s Address: Front and Center

The person you’re sending the letter to goes in the middle of the envelope, roughly centered, written across three lines: their name on the first line, street address on the second, and city, state, and ZIP code on the third.

This is the biggest, most prominent text on the whole envelope, and for good reason — it’s the only part the postal system actually needs to deliver it.

Make sure the bottom line of address (city, state, and zip) are at least an inch above the bottom of the envelope. This is the space the post office uses to apply a delivery barcode.

↖️ Your Return Address: Top Left Corner

Your own address goes small, in the top left corner — same three-line format as the recipient’s address, just your own information instead.

This isn’t required for delivery, but it’s essential if the letter can’t be delivered for some reason, since it’s how the post office gets it back to you instead of it vanishing forever.

You can handwrite your address, use one of the stickers that will invariably get sent to you by someone seeking donations, or use a rubber stamp. It doesn’t matter, as long as it stays in the upper left corner of the envelope.

🎫 The Stamp: Top Right Corner, Always

The stamp goes in the top right corner, full stop — this one’s non-negotiable, unlike some of the softer conventions elsewhere in this post.

A letter without postage simply doesn’t go anywhere, and a stamp in the wrong spot can genuinely confuse automated sorting equipment.

💰 How Many Stamps You Actually Need

A standard letter, standard size, one ounce or under, needs exactly one Forever stamp (a stamp that never expires or loses value, regardless of future postage price increases).

Anything heavier, oddly shaped, or oversized may need additional postage — worth a quick weigh or a trip to the post office counter if a letter feels notably heavier than a couple of sheets of paper.

A rule of thumb: if it makes you wonder if one stamp is enough, add another stamp.

✍️ A Few Formatting Details Worth Getting Right

Write clearly, ideally in dark ink.

The U.S. Postal Service actually prefers all capital letters with no punctuation for the address lines (their sorting machines read this format most reliably), though standard formatting works fine too — this is a nice-to-know, not a strict requirement for a personal letter.

Calligraphy is nice, but don’t use it to address the envelope – it can confuse the postal service’s scanning equipment.

📬 Why the Details Actually Matter

Here’s the part nobody explains: none of that address gets read by an actual human being who cares about penmanship. It gets read by a scanner. A fast one. The postal service runs enormous machines that photograph your envelope and pull the address apart, line by line, looking in very specific spots for very specific information.

The recipient’s name goes on one line. The street address goes on the next. City, state, and ZIP go on the line after that. The scanner isn’t reading your envelope like a paragraph — it’s reading it like a form, and it expects each piece of information to show up exactly where a form would put it.

Get the order right, and your letter gets sorted automatically in about the time it takes you to read this sentence. Get it wrong — swap two lines, scribble the ZIP code somewhere creative — and the machine can’t make sense of it.

That’s when a letter gets kicked out for a human to sort by hand, which is slower, or misrouted entirely, which is worse. Or, if you supplied a return address, it comes back to you.

All of which is to say: this isn’t etiquette for etiquette’s sake. It’s just, unglamorously, how to talk to a machine that’s about to decide where your letter ends up.

🛠️ Gear Worth Having

ExcelMark Personalized Return Address Stamp — stamp your return address in two seconds instead of hand-writing it every single time — genuinely worth it the moment you’re sending more than one or two letters a year.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Auto Insurance: What Liability, Collision, and Comprehensive Each Cover

Liability, collision, and comprehensive sound like three flavors of the same thing. They actually cover three completely different scenarios.

Marty’s insurance agent rattled off three words. Liability. Collision. Comprehensive. Maybe some combination of all three.

She said it with the breezy confidence of someone who’d explained this a thousand times before. She moved on before Marty could admit something important. He genuinely could not tell those three words apart. He picked one at random.

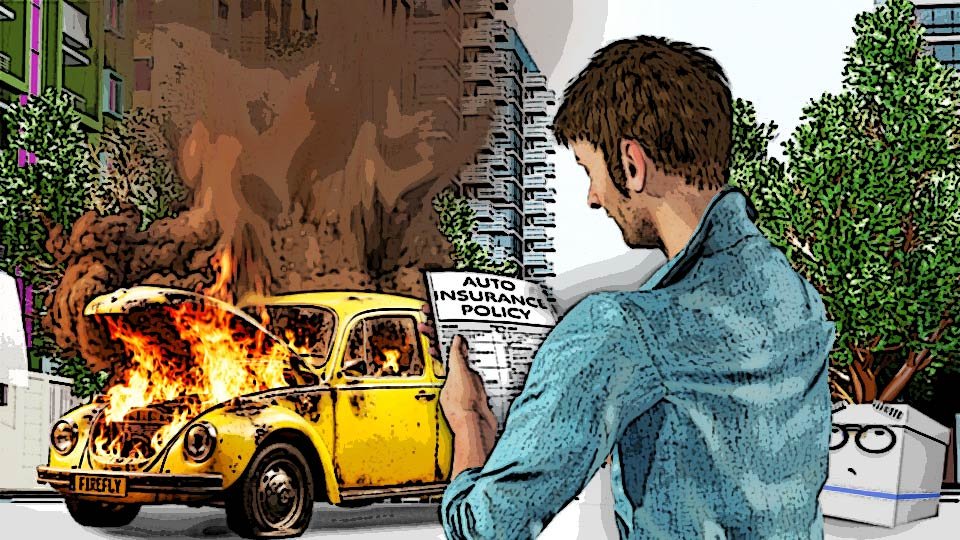
He is now standing on a sidewalk watching his car burn, holding a folder of paperwork, quietly hoping he picked the right one.

⚖️ Liability: Covers the Other Person, Not You

Liability coverage pays for damage or injury you cause to someone else. Their car. Their property. Their medical bills.

It only applies if you’re at fault in the accident.

Here’s the part that trips people up: it does not pay for your own car’s damage at all. Not a dollar of it. This is also the one coverage nearly every state legally requires you to carry, at some minimum level, just to be allowed to drive.

💥 Collision: Covers Your Car, In a Collision

Collision coverage pays to fix your own vehicle after it hits something. Another car. A guardrail. A tree.

It doesn’t matter who was actually at fault. This is the coverage that answers one specific question: who pays to fix my car after I hit something.

☔ Comprehensive: Covers Everything Else That Can Happen to a Car

Comprehensive covers damage to your car from causes other than a collision. Theft. Vandalism. Fire — yes, like Marty’s, currently, on the sidewalk.

A tree branch falling on it. Hail. Hitting a deer. It’s genuinely the broadest of the three. Think of it as covering the whole category of “things that happen to a car that isn’t even driving at the time.”

🧩 Why People Say “Full Coverage”

“Full coverage” isn’t an official policy type. You can’t call an agent and ask for it by that exact name.

It’s just informal shorthand for carrying all three — liability, collision, and comprehensive — together. That combination covers the widest range of situations. The name is a description, not a product.

🚗 Why a Car’s Value Actually Matters to This Decision

Collision and comprehensive both come with their own deductibles. They both come with their own monthly costs, on top of liability. That cost is worth weighing against what your actual car is worth.

Carrying full collision and comprehensive on a car worth $1,500 total means something specific: you could be paying meaningful monthly premiums to protect a car that wouldn’t cost much to simply replace outright.

Marty’s Beetle, the one that burned up right before his eyes, might have been exactly this kind of car. We’ll never know now.

🔗 Related Reads

  • What a Deductible Actually Means
  • What to Do Immediately After an Accident, Insurance-Wise
  • Why Your Premium Goes Up (Even When You Haven’t Filed a Claim)

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

51006

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What a Non-Compete Actually Restricts

A non-compete clause sounds like it could quietly derail your entire future career. The actual, enforceable scope is often much narrower than the wording implies.

Marty got handed a non-compete agreement along with his other new-hire paperwork. He skimmed it. The language sounded like it might ban him from ever working in his field again.

Anywhere. For the rest of his life.

Everyone else in the room was signing theirs without blinking, so he signed his too. He still doesn’t actually know what he agreed to. Neither did we, really, until we looked into it. Let’s fix that.

📜 What a Non-Compete Is Actually Trying to Do

A non-compete restricts you from working for a direct competitor after you leave a company. It also restricts you from starting a competing business yourself. Both restrictions only last for a specific period of time, not forever. The goal isn’t to trap you in your industry.

The goal is protecting something specific, like trade secrets or client relationships the company built. A well-written non-compete is narrow on purpose.

🗺️ The Three Dimensions That Actually Define Its Scope

Every non-compete has three moving parts, and the scary feeling comes from not knowing which ones apply to you.

Duration is the first one. That’s how long the restriction lasts after you leave. Commonly six months. Sometimes up to two years.

Geography is the second one. That’s the physical area the restriction actually covers. Sometimes it’s one city. Sometimes it’s one state. Occasionally, and this is where it gets unreasonable, it’s a suspiciously huge region.

Scope is the third one. That’s what specific work, or which specific competitors, are actually off-limits.

A non-compete’s real bite comes from these three numbers. Not from the scary-sounding paragraph surrounding them.

⚖️ Why Enforceability Varies Enormously by State

Some states enforce non-competes fairly readily. Other states barely enforce them at all. California is the biggest example — it essentially refuses to enforce non-competes for most employees, no matter what the signed paper says.

This is a genuinely huge variable. The exact same clause, word for word, can be fully binding in one state and functionally worthless in another.

🚫 What Non-Competes Generally Can’t Do

Some non-competes overreach on purpose, hoping nobody checks. No real time limit. No real geographic limit. An attempt to ban you from your entire industry, indefinitely, everywhere.

Courts don’t like that. Even in states that generally uphold these agreements, wildly overbroad terms often get struck down, because they go far beyond protecting any actual, specific business interest.

🔍 Non-Compete vs. Non-Disclosure: Genuinely Different Documents

A non-disclosure agreement, an NDA, restricts you from sharing confidential company information.

That’s it. That’s the whole job.

It doesn’t stop you from working anywhere afterward. A non-compete and an NDA often show up in the same stack of new-hire paperwork, back to back, which is exactly why people mentally mash them into one document. They’re not the same document. They’re solving two completely different problems.

💼 What to Actually Do Before Signing One

Read the actual duration. Read the actual geography. Read the actual scope. If any of the three feels unusually broad for your actual role — and Marty, this means you too — it’s genuinely fine to ask questions before signing.

For a significant position, having an employment attorney review it is a normal, professional step. Not an adversarial one. Not a red flag to your new employer.

Just due diligence, the same as reading anything else you’re about to sign.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

58007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What “At-Will Employment” Actually Means

“At-will employment” is buried in nearly every offer letter, sounds vaguely ominous, and actually cuts both ways more than people realize.

Alexa found the phrase in her offer letter, tucked between two paragraphs she’d already skimmed: “This is an at-will employment relationship.”

She read it twice. It sounded like something a lawyer had written specifically to worry her. So let’s do this properly. Sit down. We’re going to walk through exactly what that sentence means, one piece at a time, and none of it is as ominous as it sounds.

⚖️ The Actual, Two-Way Definition

At-will employment means the employer can end the working relationship at any time. It also means they can do it for any legal reason, or no reason at all. No advance notice is required. That’s the part that sounds one-sided, and it’s the part that scared Alexa.

Here’s what she missed on the first read: it goes both directions.

You’re equally free to leave whenever you choose. You don’t need a specific justification either. It’s not a leash. It’s a door that swings open from both sides.

🇺🇸 How Standard This Actually Is in the U.S.

At-will employment isn’t a red flag buried specifically in your offer letter. It’s the default arrangement in nearly every U.S. state. Montana is the one notable exception.

So this isn’t your company being unusually aggressive. It’s just the standard legal backdrop underneath almost every job in the country.

🚫 What It Doesn’t Override

At-will status has real limits, even though the phrase sounds absolute. It doesn’t permit illegal firing.

Termination based on discrimination against a protected class is still illegal. Retaliation for reporting illegal activity is still illegal.

Violating a specific contract term you actually have in writing is still illegal too.

“At any time, for any reason” has a legal floor underneath it, even when the phrase itself doesn’t mention one.

📄 What Actually Changes This Default

A specific employment contract with defined terms can override at-will status entirely.

This is common for higher-level executives. It’s also common in some union positions and specific industries. In those cases, the contract’s actual terms govern termination, not the at-will default.

Most entry-level and mid-career jobs don’t have one of these contracts. They operate under the plain at-will default, full stop.

That’s not unusual. That’s just most jobs, including, statistically, yours.

🚪 Why It’s Worth Understanding Rather Than Fearing

At-will status is genuinely a two-way street.

It protects your ability to leave just as much as it protects the company’s ability to let you go.

Understanding it accurately does two things at once. It removes some unnecessary anxiety about a phrase that sounded scarier than it is. And it leaves you with a realistic, accurate picture of the actual relationship you’re walking into — which, it turns out, was the goal of this whole conversation.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

58005

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Negotiating a Job Offer Without Feeling Like a Jerk

Negotiating a job offer feels like it might blow the whole thing up. In practice, it’s an expected, normal part of the process almost everyone quietly does.

Alexa read her offer letter three times, felt a wave of relief so enormous it was practically load-bearing, and then made the mistake of scrolling one paragraph further — to the number.

It wasn’t a bad number. It just wasn’t the number she’d hoped for.

And the thought of actually saying something about it, out loud, to the actual company, made her stomach do the thing where it feels like it’s trying to leave the building without her.

Negotiating felt less like a normal business conversation and more like the kind of move that might make the whole offer quietly evaporate, as if gratitude and greed were somehow the same emotion wearing different outfits.

😌 The Honest Reassurance Worth Hearing First

Here’s the thing Alexa didn’t know yet, standing there rereading the same paragraph for the fourth time: negotiating isn’t a bold, risky move that companies quietly resent.

It’s an expected, completely normal part of the hiring process — so expected, in fact, that most companies build a little room into their first offer specifically because they anticipate someone will ask. A reasonable employer isn’t offended by the question. They were kind of waiting for it.

That doesn’t make the nerves disappear. It just means the nerves are responding to a threat that mostly isn’t real.

🎯 What’s Actually Negotiable, Beyond Just Salary

Base salary is the obvious target, and it’s where most people’s brains go first — but it’s not the only lever in the room, and fixating on it alone can mean missing better, easier wins elsewhere.

Start date, a signing bonus, extra vacation days, remote work flexibility, or a professional development budget are all genuinely negotiable in plenty of situations.

Sometimes a company that’s genuinely firm on salary has real room to move on start date or PTO instead, simply because those come out of a different budget. Worth thinking about the whole package before deciding where to push.

🗣️ How to Actually Say It, Without Overthinking the Wording

Stating your concern is usually the part that stalls people out completely — not the decision to negotiate, but the fear of somehow phrasing it wrong.

The good news is that it doesn’t take a script, a rehearsed pitch, or a confrontational tone. Something simple and direct works fine: “I’m genuinely excited about this offer. Based on my research and experience, I was hoping we could discuss the base salary — is there flexibility there?”

That’s it. Warm, clear, and it does the one thing that actually matters: it names what you want without demanding it, and it leaves the door open for a real conversation instead of a standoff.

📊 Why Research Makes the Ask Feel Genuinely Reasonable

Part of what made Alexa’s stomach lurch was that her ask felt like it was coming from nowhere — just a feeling that she deserved more, with nothing behind it.

That’s exactly what research fixes. Knowing the typical salary range for the role, in your specific location, through one of the sites built for exactly this kind of research, turns a vague “can I have more?” into a specific, defensible “based on market rate for this role, I was hoping for X.”

A number grounded in real data doesn’t feel like an opinion you’re defending. It feels like a fact you’re reporting.

⏳ Why Timing Matters

Negotiate after you’ve received a formal, written offer — not during the earlier interview stages, when the company hasn’t fully decided on you yet.

Your leverage is at its highest the moment they’ve already picked you specifically and are hoping you say yes.

Asking too early, before an offer even exists, can come across as presumptuous. Asking after a real offer is just standard practice, on a timeline everyone already expects.

🙅 What Happens If They Say No

Here’s the scenario Alexa was actually most afraid of, underneath everything else: what if she asks, and they simply say no?

In practice, a reasonable employer just says the offer is firm. That’s it. It’s a genuinely normal outcome, not a sign the whole opportunity has curdled or that anyone’s mad at her.

At that point, she’d be exactly where she started — deciding whether the original offer works for her — except now with one more piece of information than she had before asking. Nothing lost. Possibly something gained. That’s the actual math of it, once the nerves get out of the way.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

58006

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved