Why Your First Paycheck Was Smaller Than You Thought

You did the math on your hourly rate and it doesn’t match what actually landed in your account. Here’s exactly where the difference went.

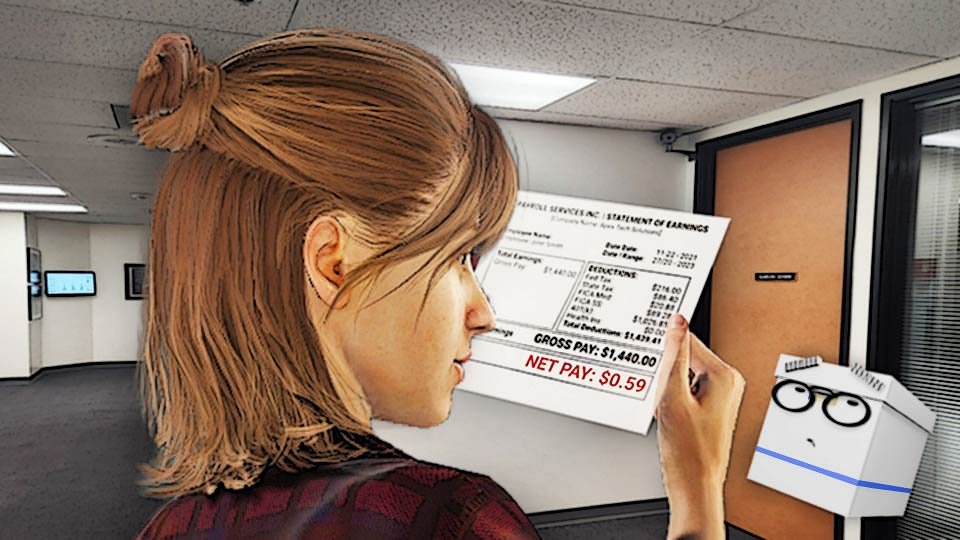
Alexa did the math before her first paycheck even arrived. $18 an hour, roughly 80 hours over two weeks, that’s $1,440, simple multiplication, she’d checked it twice.

The number that actually showed up in her account was $1,140. She stared at her phone for a solid minute, genuinely wondering if her employer had made a mistake, or possibly forgotten how multiplication works.

Neither. That missing $300 didn’t vanish. It went to exactly six specific places, all at once, all with their own names, none of which anyone had ever explained to her.

💸 The Two Numbers That Don’t Match: Gross vs. Net

Gross pay is the number you did the math on — hours times your rate, or your stated salary divided out per paycheck. It’s the full, pre-deduction amount your work actually earned.

Net pay, sometimes called “take-home pay,” is what’s left after everything gets subtracted out, and it’s the number that actually lands in your bank account.

Every single deduction on a pay stub is the gap between those two numbers, itemized. Nobody’s shortchanging you. The paycheck is just reporting both numbers, and only one of them was ever going to be spendable.

🏛️ FICA: The One Everybody Pays, No Exceptions

FICA stands for the Federal Insurance Contributions Act, and it funds two specific federal programs: Social Security and Medicare.

It’s 7.65% of your gross pay, combined — 6.2% to Social Security, 1.45% to Medicare — taken automatically from essentially every paycheck, at every job, regardless of income level or how much you like the idea.

This isn’t optional, isn’t a mistake, and isn’t specific to your employer. It’s federal law, applied the same way to nearly every paycheck in the country.

📋 Federal (and Sometimes State) Withholding

This is the government collecting an estimate of the income tax you’ll owe for the year, a little at a time, instead of asking you for one enormous payment next April.

The amount withheld is based on what you filled out on a form called a W-4 when you were hired — covered in its own post, since it’s worth understanding on its own — which tells your employer roughly how much to hold back from each check.

If you live in a state with its own income tax, a separate state withholding gets taken out too, right alongside the federal amount.

🧾 Other Things That Might Be Missing Too

Depending on your specific job, a few other deductions might be quietly doing their part: a health insurance premium, if you’ve opted into a plan through work.

A retirement contribution, like a 401(k), if you signed up for one.

These aren’t hidden fees — they’re things you actually chose, usually during onboarding paperwork that felt like a blur at the time, which is exactly why they’re worth double-checking on your first real pay stub rather than assuming you remember every box you checked.

🧮 A Quick Walkthrough With Real Numbers

Take that $1,440 gross paycheck. FICA takes roughly $110 (7.65%). Federal withholding might take another $140 or so, depending on the W-4 on file and how much was actually earned. State withholding, if applicable, takes a smaller additional slice.

Add it up, and a net paycheck landing somewhere around $1,140 to $1,200 isn’t a mistake at all — it’s the completely normal, expected result of gross pay meeting the standard set of federal deductions everyone runs into.

✅ The Actual Takeaway

The gap between gross and net isn’t a red flag, a clerical error, or your employer quietly skimming off the top. It’s the predictable sum of a handful of specific, named deductions, every one of which shows up right there on the pay stub if you actually read it line by line.

Once you know what each line is for, the smaller number stops feeling like a mystery and just becomes the number you were always actually going to take home.

🔗 Related Reads

  • Reading Your W-2 Without Panicking
  • How Tax Refunds Actually Work (It’s Not Free Money)
  • How to File Your Taxes

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

56008

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
How a Claim Actually Works, Start to Finish

Filing an insurance claim for the first time feels like sending a message into a void. Here’s what’s actually happening on the other end.

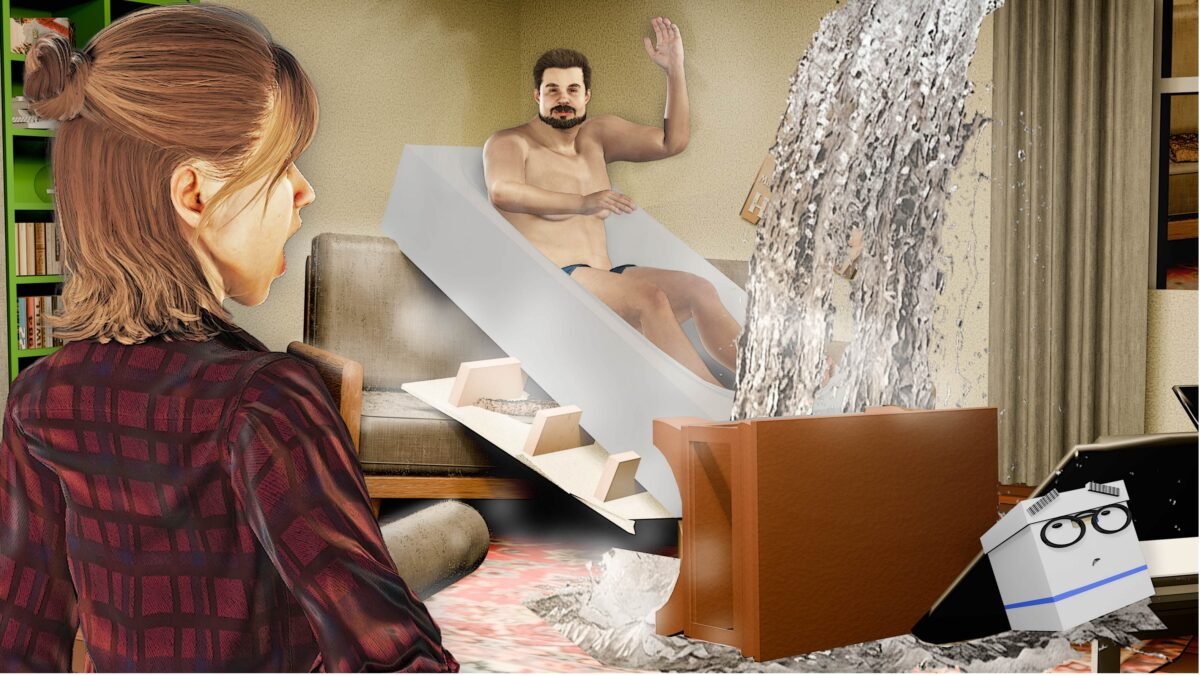
Alexa’s ceiling produced a bathtub. Not metaphorically — an actual bathtub, at an angle, with her upstairs neighbor Carl riding it down like a waterslide, shirtless, waving, apparently under the impression that this qualified as dropping by to apologize.

His bathtub had overflowed for reasons he described as “a whole thing,” and now her ceiling had a hole in it roughly bathtub-shaped, her rug was soaked through, and she was on the phone with her insurance company, panicking, while the calm, unbothered voice on the other end used the word “claim” roughly nine times in ninety seconds without ever quite explaining what that actually meant or what happened next.

Carl, meanwhile, was still standing in her living room in swim trunks. Let’s sort out the insurance part first.

📞 Step One: You Report It

A claim starts with you telling your insurance company something happened — by phone, app, or website, depending on the company.

You’ll describe what occurred (a neighbor’s bathtub flooded through your ceiling, for instance, an example chosen entirely at random), roughly when it happened, and roughly what was damaged or lost.

This first call isn’t the whole process. It’s just opening the door to it, the very first domino, not the resolution.

🔢 You Get a Claim Number — Write This Down Immediately

Every claim gets assigned a specific reference number, and every single future conversation about it — every phone call, every follow-up, every time you get transferred to someone new — will start with someone asking you for that number.

Write it down the second you get it, somewhere you won’t lose it. A claim number is the difference between a thirty-second follow-up call and starting the entire soaked-rug, shirtless-neighbor explanation over again from scratch with a total stranger.

🕵️ Step Two: An Adjuster Gets Involved

An insurance adjuster is the person whose actual job is investigating the claim — reviewing whatever documentation you provide, sometimes inspecting the damage in person, sometimes working entirely from photos, and ultimately determining how much the insurance company should actually pay out.

Think of them as the translator standing between “something bad happened to my ceiling” and an actual dollar figure the policy is willing to cover. They didn’t witness Carl’s descent. They only know what you show them.

📸 Why Your Own Documentation Matters So Much Here

Photos of the damage — the hole in the ceiling, the water stain spreading across the rug, the actual bathtub sitting at an angle in the middle of the living room, if it’s still there. Carl doesn’t necessarily figure into these pictures.

Receipts for anything damaged or ruined. A written timeline of what happened and when, while it’s still fresh, not reconstructed from memory two weeks later. All of this genuinely speeds up and strengthens a claim.

An adjuster working from clear photos and a clear timeline moves faster, and more accurately, than one working only from a panicked phone call and a secondhand description of a man in swim trunks.

💰 Step Three: The Settlement

Once the adjuster finishes reviewing everything, the insurance company offers a settlement — the actual amount they’ll pay, with your deductible already subtracted from it.

This isn’t automatically a final, take-it-or-leave-it number handed down from on high. You’re allowed to negotiate or push back if the offer genuinely seems to undervalue what was lost or damaged, the same way you’d question any bill that looked wrong.

⏱️ How Long This Actually Takes

Simple, well-documented claims can resolve in days to a couple of weeks.

More complex ones — significant damage, disputes over what actually caused it, disagreements over value — can take considerably longer.

There’s no single universal timeline that applies to every claim equally, which is exactly why holding onto that claim number for follow-up calls matters as much as it does; a claim that’s taking a while isn’t necessarily a claim that’s gone wrong.

🚫 If a Claim Gets Denied, That’s Not Automatically the End

Claims do get denied — sometimes for legitimate policy reasons, sometimes because of a genuine mistake, missing documentation, or paperwork that got filed incorrectly somewhere along the way.

Most insurers have a formal appeals process built for exactly this. It’s worth actually reading the denial reason carefully rather than assuming it’s final, and pursuing it if the reasoning genuinely seems wrong.

A denial is a checkpoint, not necessarily the last word.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

51008

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Health Insurance: Deductible vs. Copay vs. Coinsurance, Explained

“I have insurance, why do I owe anything?” Here’s what a copay, a deductible, and coinsurance actually are, and why they’re not the same question.

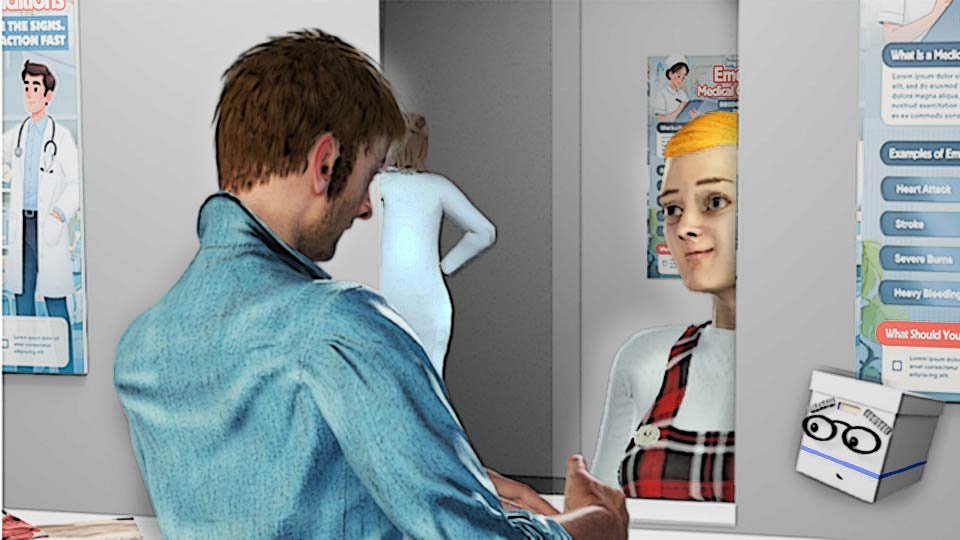
Marty is standing at an urgent care reception window, alone, for the first time in his life, holding his insurance card out like it’s a magic key that should unlock the whole visit for free.

The receptionist, who is also making eyes at him in a way he has not fully registered because he is currently panicking about money, says the number “$25” out loud.

Marty blinks. He has insurance. He pays for it every month. Why does he also owe money right now, standing here, before anyone’s even looked at the ankle he’s fairly sure he sprained? The honest answer is that he’s about to meet three different insurance words, only one of which applies to this exact moment, and nobody ever sat him down to explain the difference.

💵 The Copay: The One That Applies to Marty, Right Now

A copay is a flat, fixed fee you pay at the time of a visit — $25, $40, whatever your specific plan sets for that type of visit — regardless of anything else going on with your insurance.

It doesn’t care whether you’ve met your deductible.

It doesn’t care whether this is your first doctor visit of the year or your tenth.

It’s simply the toll for walking through the door for this specific kind of appointment, due today, at the window, before you’re called back.

That’s exactly why the receptionist is asking Marty for $25 right now, insurance card already on file and everything — the copay isn’t a sign that something’s wrong with his coverage. It’s just how his plan is built.

🏥 The Deductible: The Bigger Number Working in the Background

A deductible is the amount you have to pay out of your own pocket, across the whole year, before your insurance starts covering a bigger share of your bills.

Think of it as a threshold that has to be crossed once, not a fee charged every visit.

A $1,500 deductible means you’re paying close to full price for covered care until your out-of-pocket total hits $1,500 for the year — after that, your insurance starts picking up much more of the tab.

Copays sometimes count toward that total and sometimes don’t, depending on the specific plan, which is worth checking rather than assuming either way.

📊 Coinsurance: The Percentage Split That Shows Up After the Deductible

Coinsurance is a percentage split between you and your insurance company, and it only kicks in after your deductible has actually been met.

A common setup is 80/20 — insurance pays 80% of a covered bill, you pay the remaining 20%.

So, say the procedure is $2,500. You pay $1,500 to meet the deductible. After that, your insurance pays 80% of the remaining $1,000, which leaves you owing $200 instead of the full amount. On that procedure, your insurance picked up $800 you would otherwise have had to pay.

Coinsurance is the reason two people with “good insurance” can still owe wildly different amounts for the same procedure — it depends entirely on where each of them stands against their own deductible that year.

🧩 Why All Three Can Apply to the Same Plan

Here’s the part that actually trips people up, Marty included.

These three are separate mechanisms that can all exist on one single insurance plan, kicking in at different moments. The copay is due today, at this visit, full stop.

The deductible is a running yearly total, quietly tracking every dollar you’ve paid out of pocket so far.

Coinsurance only shows up once that deductible’s been crossed, splitting whatever comes next by percentage instead of a flat fee.

A single visit might only ever touch one of the three — which is exactly Marty’s situation right now, standing at a window, owing a flat $25 and nothing more complicated than that.

❓ What to Actually Do If You Don’t Have the $25 on You

Say so.

Genuinely, that’s the whole move.

Front desk staff hear “can you bill me for the copay” on a regular basis, and most offices have a completely normal process for it — they’ll bill you directly, or let you pay after the visit rather than before it.

It’s not an embarrassing conversation, no matter how much a nervous twenty-something at a reception window might imagine otherwise, distracted receptionist notwithstanding.

🔗 Related Reads

  • What a Deductible Actually Means
  • What “In-Network” Actually Means and Why It Matters
  • Reading Your Policy’s Declarations Page

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

51007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Extended Warranties: Worth It, or a Waste of Money?

The cashier asks about the extended warranty for nearly everything now. Here’s an actual framework for when to say yes.

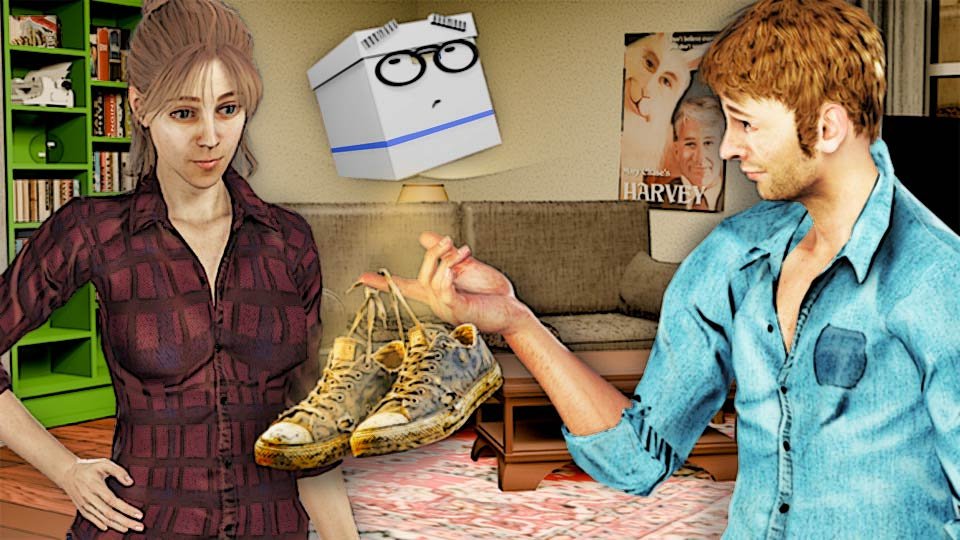
Marty is holding up a pair of sneakers that have been through several genuine hardships — mud, at least one questionable puddle decision, a sole worn down to something closer to a suggestion than a tread pattern — and asking, with total sincerity, whether the extended warranty he bought on them two years ago covers this.

Alexa’s face is doing a great deal of work in this conversation, none of it verbal, all of it communicating some version of “absolutely, unequivocally not, and I cannot believe I have to explain why.”

Marty bought that same kind of confused four-second yes at plenty of other checkout counters too, on a laptop, a TV, a blender, without ever quite working out what he was actually paying for. Let’s actually work it out.

💰 What You’re Actually Buying

An extended warranty, sometimes called a protection plan, extends coverage beyond the manufacturer’s original warranty period, usually for a specific extra fee tacked onto the purchase.

It’s essentially a bet: you’re paying money now on the chance that something breaks later, which is genuinely the same structure as an insurance policy, just scaled down to one single object instead of a broader category of risk.

And like any warranty, it almost always still only covers a genuine defect or malfunction — not, say, two years of mud, puddles, and enthusiastic wear.

Marty’s sneakers didn’t malfunction. They did their job, repeatedly, until they simply wore out, which is a completely different category of “broken” than any warranty, extended or otherwise, was ever built to cover.

📊 Why They’re Priced the Way They Are

Extended warranties are generally quite profitable for retailers, which is exactly why they get pushed so consistently at checkout, by an employee who is frequently required to ask whether you’d like one before they can even finish ringing you up.

The price charged is usually well above the statistical likelihood and average repair cost of the item actually needing covered work.

That’s not a conspiracy theory — it’s just how the math works out in the retailer’s favor across enough transactions. Somebody’s paying for that profit margin, and it’s the aggregate of everyone who bought the plan and never used it.

✅ When It Genuinely Might Make Sense

Expensive electronics with a known history of specific failure points — a particular laptop model with a documented hinge problem, for instance.

Items that get heavy or rough use as a matter of course.

Or, and this one’s worth being honest with yourself about, if you already know you’re genuinely bad about being careful with fragile things. This is a real, personal risk assessment, not a blanket yes or no answer that applies to every purchase equally.

\And if replacing the item outright would be a genuine financial hardship — not an annoyance, an actual hardship — some peace of mind may be worth the cost even when the pure statistics lean against it.

❌ When It Usually Doesn’t

Inexpensive items, where the extended warranty cost approaches a meaningful fraction of the item’s own price — a $15 warranty on a $40 kitchen gadget is a much worse deal, proportionally, than a $50 warranty on a $2,000 laptop.

Products with a strong general reliability reputation. And anyone who could comfortably self-insure, meaning simply set aside the cost of the warranty itself in a savings account and use that money if something eventually breaks.

Do that consistently across enough purchases, and you come out ahead of buying the warranty every single time, because you keep the money on all the purchases that never broke at all.

💳 The Overlap Nobody Checks: Your Credit Card

Many credit cards already include purchase protection or extended warranty benefits automatically, at no extra cost, for things bought with that card — often adding a full extra year onto the manufacturer’s original warranty, or covering theft and accidental damage for a limited window after purchase.

This is genuinely worth checking in your card’s benefits guide before paying separately for coverage you might already have sitting there, unused, attached to a card you’ve had for years.

🧮 A Simple Gut-Check Before Saying Yes

Two questions, asked honestly, standing right there at the register: what’s the actual cost to repair or replace this item without coverage, and how likely does a failure genuinely feel within the extended period — not how likely does the cashier’s pitch make it sound.

If the warranty cost is a small fraction of either number, it’s a much easier yes.

If it’s creeping up toward a meaningful chunk of the item’s own value, that’s the moment to pause, the same four seconds Marty didn’t take, and actually think it through instead of nodding along.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

57009

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved

What to Do Immediately After an Accident, Insurance-Wise

The five minutes right after a car accident are genuinely disorienting. Here’s the exact order of what to actually do.

Marty’s Firefly clipped a tree at exactly the wrong angle, and now he’s standing on the sidewalk with one hand on his head, staring at a hood that used to be flat and is now shaped more like a taco.

His mind is completely blank, and not in a calm way — in the specific, buzzing way where you’re absolutely certain there’s a correct sequence of things you’re supposed to be doing right now, and you cannot, under any circumstances, remember a single one of them. He also doesn’t know what half the words on his insurance card mean. Let’s fix both problems.

🚨 Step One: Safety, Before Anything Else

Check yourself and anyone else involved for injuries first, before paperwork or insurance enter the picture at all.

If anyone’s hurt, or there’s real doubt, call 911.

If the vehicles are drivable and safe to move, get them out of active traffic. If they’re not, leave them exactly where they are and turn on your hazard lights. Nothing else on this list matters until this step is handled.

📞 Step Two: Call the Police, Even for a Minor Accident

A police report is genuinely useful even for a small, seemingly obvious accident — it’s an official, neutral, third-party record of what happened, and that becomes valuable if there’s ever any disagreement about fault later.

“Fault” just means whose driving actually caused the accident, which sounds obvious in the moment and gets surprisingly contested later once two insurance companies are involved.

Some states legally require a report above a certain damage amount. When in doubt, get one anyway.

🔄 Step Three: Exchange the Right Information

Get the other driver’s name, phone number, insurance company and policy number (the specific account number tied to their coverage, found on their insurance card), and license plate.

Share the same information about yourself.

You generally don’t need to discuss who was at fault at the scene at all — that’s genuinely not your job to determine standing on a sidewalk with a taco-shaped hood next to you. That’s what the police report and the insurance companies are for.

📸 Step Four: Document Everything, Right There, On the Spot

Photos of both vehicles, all visible damage, the license plates, the surrounding scene, and anything relevant nearby — a stop sign, a tree, skid marks.

This is the exact documentation an adjuster will lean on later.

An adjuster, in plain terms, is the insurance company’s own investigator, the person whose entire job is figuring out what actually happened and what it’ll cost to fix. Photos taken in the moment are far more convincing to that person than anything reconstructed from memory two days later.

👀 Step Five: Get Witness Info, If Anyone Saw It

If anyone witnessed the accident and is willing, grab their name and phone number too.

A neutral third party’s account can matter a lot if the other driver’s version of events doesn’t match yours once both insurance companies start asking questions.

📱 Step Six: Call Your Insurance Company, Even If You Weren’t at Fault

Report the accident to your own insurer regardless of who caused it.

This isn’t the same thing as admitting fault — it’s simply opening a claim, which is just the formal term for “officially telling my insurance company this happened so they can start figuring out what gets paid for and by whom.”

Calling promptly gets your own company aware and involved from the very start, instead of finding out about it secondhand once the other driver’s insurer calls them first.

🛠️ Gear Worth Having

Automotive Accident Report Log Book — a physical, glovebox-ready guide that walks you through exactly this checklist when your brain, understandably, isn’t at its sharpest.

As an Amazon affiliate, I earn from qualifying purchases. Thank you for supporting ScrumbleDoc.

A dash cam, if you’ve got one, does a lot of this documentation work automatically — worth reading GrumblePark‘s take on defensive driving basics if you’re thinking about adding one.

🔗 Related Reads

  • How a Claim Actually Works, Start to Finish
  • Auto Insurance: What Liability, Collision, and Comprehensive Each Cover
  • What a Deductible Actually Means

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

51001

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What a Warranty Actually Promises (and What It Doesn’t)

A warranty sounds like a blanket promise that nothing will go wrong. It’s actually a much narrower, much more specific deal than that.

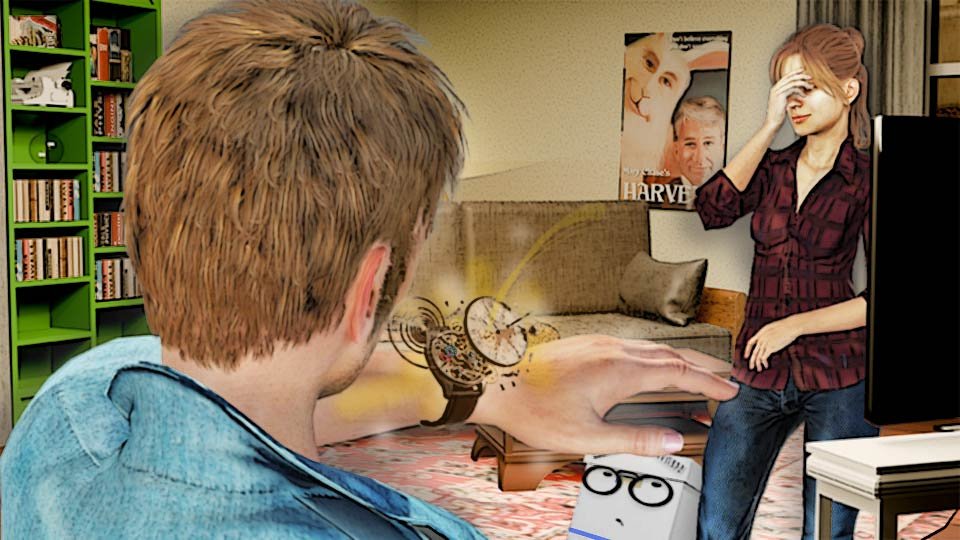
Marty bought a Firefly watch — a nice one, mechanical, the kind with visible gears you can watch tick through the case back — and saw “2-year warranty” stamped proudly on the box.

He mentally filed that away as “nothing bad can happen to this watch for two years,” a genuinely reasonable-sounding assumption.

Right up until the morning it spontaneously detonated on his wrist, gears and hairspring flying in every direction, for no reason he could identify. No drop. No water. No dumb decision on his part. Just a watch that decided, apparently on its own schedule, to stop being a watch.

Whether that two-year promise on the box actually covers something this dramatic is exactly the question worth understanding before it happens to you too.

📜 The Actual, Narrow Promise Being Made

A warranty is a promise from the manufacturer, or sometimes the seller, to repair or replace a product if it fails due to a defect in materials or workmanship.

  • It’s covered if there’s something wrong with how the thing was made.
  • It’s not covered for simply anything that could ever go wrong with it once it’s in your hands.

That distinction is the entire concept, and it’s exactly the part that gets lost in translation between the confident stamp on a box and what a customer assumes it means.

Marty’s watch spontaneously flying apart, with no outside cause anyone can point to, is close to a textbook example of the kind of failure a warranty is actually built to cover — a flaw baked in from the factory floor, not something life did to it afterward.

🔨 What a Warranty Generally Does NOT Cover

  • Normal wear and tear — a leather watch band that eventually cracks after five years of daily wear, a blender blade that dulls after thousands of smoothies.
  • Accidental damage — dropping the watch on tile, spilling something into the blender’s motor housing.
  • Misuse, or damage from ignoring the included instructions — running that same blender dry for ten minutes because you forgot to add liquid first. .

All of these are almost universally excluded, and for a consistent reason: a warranty protects against the product being flawed from the moment it left the factory. It doesn’t protect against ordinary life happening to the product afterward, no matter how sympathetic the story is

⏳ The Coverage Period: A Real, Specific Clock

Warranties run for a defined length of time — 90 days for something small and cheap, one year for most electronics, two years or more for major appliances and higher-end goods like Marty’s watch.

The clock starts on the purchase date, not from whenever you actually get around to using the thing. A watch that sat wrapped in its box for eight months as a gift, unopened, still had its warranty clock quietly ticking the entire time.

A warranty that expired while an item sat unused in a closet is still, unfortunately, expired. Nobody pauses the clock for you.

🧾 Why the Purchase Receipt Matters So Much

Nearly every warranty claim requires proof of purchase — the original receipt, an order confirmation email, or a credit card statement showing when and where the item was bought.

Without that proof, a manufacturer has no way to confirm the item is even still inside its warranty window, no matter how obviously, dramatically defective it looks sitting in pieces on your kitchen counter.

This is exactly why it’s worth photographing a receipt or forwarding an order confirmation email to yourself the day you buy anything with real warranty value. Future you, holding a broken watch and an expired memory of where it came from, will be grateful.

🔧 Repair, Replace, or Refund — Not Always Your Choice

Most warranties give the manufacturer, not you, the choice of how to resolve a valid claim: repairing the item, replacing it outright with a new one, or occasionally refunding the purchase price.

The specific wording of the warranty usually spells out which of these the company is actually obligated to offer, rather than leaving it up to your personal preference.

Marty might want a brand-new watch handed to him on the spot. Firefly’s warranty terms might only actually promise a repair. Reading the fine print before a claim, not during one, is the only way to know which outcome you’re actually entitled to.

🧭 The Big Takeaway Worth Carrying Into Every Purchase

A warranty is real, genuine protection against a product being defectively made — not a blanket insurance policy against anything that could ever happen to it in your possession.

Knowing that distinction going in means far fewer surprises when a claim actually gets filed later, whether it’s a watch that exploded for no visible reason or a blender that finally gave up the ghost on a smoothie that was, this time, entirely its own fault.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

57010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
The Last Sleepover for Lewis: What Makes a Good Houseguest

Being a good houseguest isn’t complicated. It’s just a long list of small things nobody tells you until you’ve already gotten every one of them wrong.

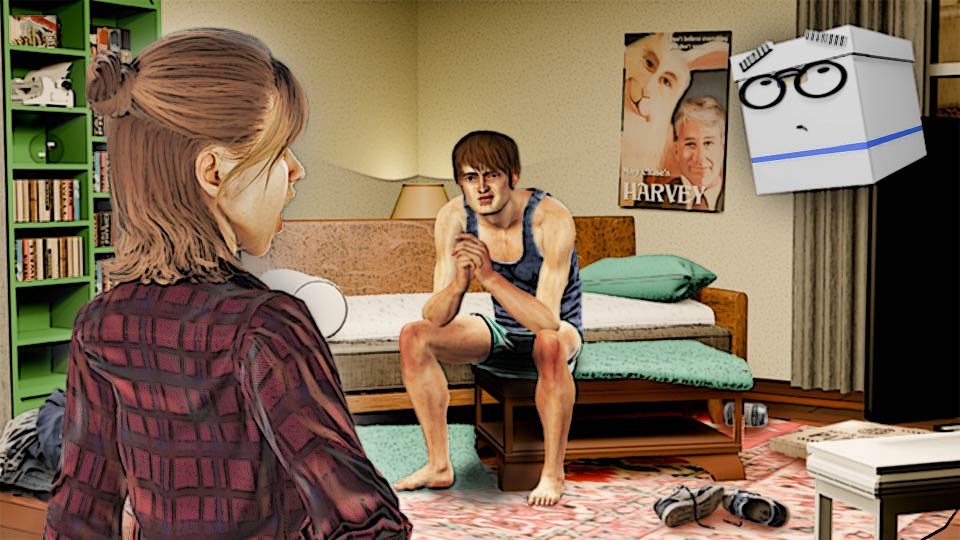
Lewis has stayed over four times now. This was going to be the last one, though he didn’t know that yet, sitting on the edge of the coffee table while Alexa delivered the news in the calm, measured tone of someone who had rehearsed this speech in the shower that morning.

Lewis is a genuinely nice guy. He is also the kind of houseguest who leaves the bed looking like a crime scene, has never once offered to buy groceries, and treats “what time works for breakfast” as a rhetorical question rather than one requiring an actual answer.

None of this made him a bad person. It made him, four visits running, a bad guest — which turns out to be its own separate skill nobody teaches directly.

🛏️ The Basics: Treat the Space With Real Respect

Keep your area reasonably tidy — not showroom-perfect, just not actively hazardous. Ask before using anything that wasn’t obviously offered to you: specific towels, the good coffee, whatever’s clearly someone’s personal shampoo and not the guest bottle.

Be mindful of noise, especially early morning and late night, when the rest of the house is asleep and you are, apparently, watching videos at full volume on your phone with the ringer still on.

None of this is complicated. It’s just “this isn’t your space” translated into the specific, boring, practical decisions that come up every single hour of an actual stay.

🍽️ Contribute Without Waiting to Be Asked

Offer to help with a meal. Pick up groceries once during the stay, unprompted.

Handle a chore — empty the dishwasher, take out the trash — without being asked to.

A host almost never asks directly for any of this, because asking a guest to help feels rude to most hosts, even when they’d genuinely appreciate it.

That means the entire signal has to come from you offering first.

Lewis, notably, never offered. Lewis assumed hospitality was a bottomless resource that simply regenerated on its own, like a video game health bar.

📅 Have a Real Sense of Your Own Schedule

Know roughly what you’re doing each day of the visit, rather than treating your host like a full-time cruise director whose entire job is entertaining you.

Your host has an actual life continuing to happen around your visit — work, errands, other obligations — and “what are we doing today?” asked fresh every single morning, with zero ideas of your own attached, gets exhausting to answer by day three.

🛏️ The Bed: Strip It or Make It, Don’t Just Leave It

On departure, strip the bedding if that’s the house norm, or at minimum make the bed neatly if it isn’t.

This is a small gesture that costs you ninety seconds and genuinely changes how the whole visit gets remembered.

A rumpled, abandoned bed is the specific image burned into Alexa’s mind from visit number three, and it is, as of this conversation, the reason visit number five isn’t happening.

🎁 The Host Gift: A Real, Worthwhile Gesture

Bring something for your host — beyond a single dinner contribution, especially for a multi-night stay.

A bottle of something, a small specialty from wherever you’re traveling from, or simply treating them to a nice meal out during the visit all genuinely round things out. It doesn’t need to be expensive.

It needs to exist, which puts it several steps ahead of whatever Lewis brought, which was nothing, four separate times, with a level of consistency that was almost impressive.

✍️ The Thank-You Afterward

Send a genuine thank-you message after you’ve left — not the rushed “thanks for having me!” shouted over your shoulder on the way out the door, but something sent later, that actually names the specific effort they put in.

For a longer or more significant stay, this is exactly the situation from the thank-you note post where an actual written note, not just a text, earns its extra effort.

Lewis sent a text. It said “lol thx.” He is currently, as far as he knows, still welcome for a fifth visit.

🔗 Related Reads

ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54009

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Tipping: Who, How Much, and When

Tipping culture has quietly expanded to include a tablet turned toward you at the coffee counter. Here’s an actual framework for navigating all of it.

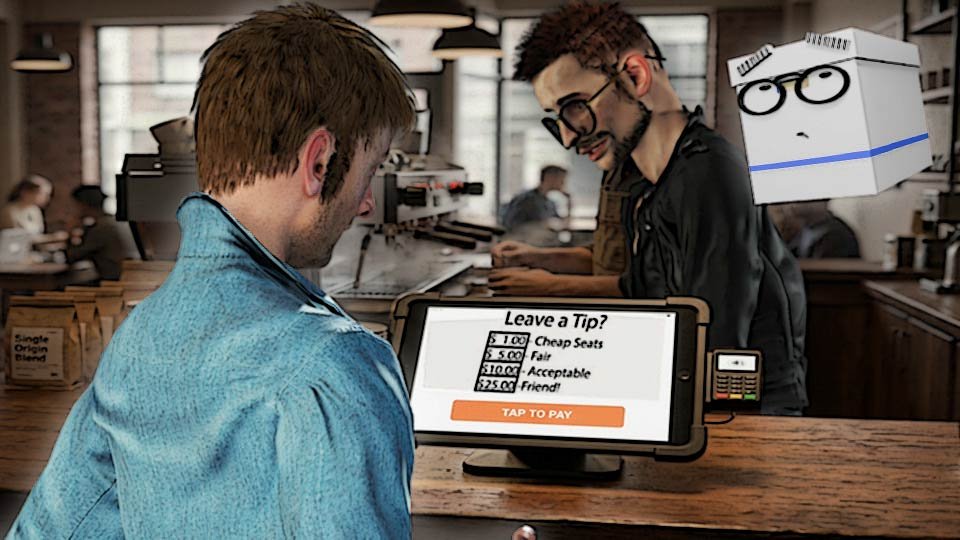
Marty ordered a single coffee. One coffee. A beverage that involved a machine and roughly eleven seconds of another human’s time. The card reader spun around to reveal three preset tip options, the lowest of which was still a genuinely startling percentage of four dollars.

He stood there, frozen, doing quiet, anxious math in front of a growing line of people, all of whom were presumably judging him for taking so long to decide the fate of sixty cents.

🍽️ Restaurants: The Most Established Baseline

Sit-down restaurant service is the one category almost everyone already agrees on: roughly 15-20% of the pre-tax bill for typical service, higher for something genuinely excellent.

It’s honestly fine to tip less for service that was genuinely bad — not “they forgot the extra napkins” bad, but “you had to physically go find your own server” bad.

Most people default toward the higher end of that range without thinking too hard about it, which is a perfectly reasonable way to not have to digest numbers while digesting dinner.

🚗 Delivery and Rideshare: A Real, Expected Category

Food delivery and rideshare drivers genuinely rely on tips as real income, not a bonus, the same way a restaurant server does.

A common range is 15-20%, or a flat few dollars for a short trip.

It’s worth treating this category with the same seriousness as sit-down dining, not as some kind of optional extra.

The driver isn’t tangential to the transaction. He is, structurally, most of it.

💇 Personal Services: Hairdressers, Barbers, and Similar

Generally 15-20%, same as a restaurant.

One wrinkle worth knowing: some salon owners who own their own chair don’t expect a tip the same way an employee stylist does, since they’re not splitting the proceeds with a business owner above them.

This is a genuinely normal thing to just ask about directly — “do you take tips?” is not an awkward question, it’s a completely standard one, asked constantly, by people who did not want to do the math either.

📱 The Tablet-Turned-Toward-You Situation: You Genuinely Have Options

Counter service — coffee shops, quick takeout, the eleven-second transactions of the world — is where tipping culture has expanded fastest and least consistently, and it’s worth understanding why that screen makes you feel the way it does before deciding what to do about it.

Those preset percentages aren’t neutral. They’re deliberately set high, because a screen that starts at 25% makes 15% feel like the stingy option, even on a four-dollar coffee that took eleven seconds to make. That’s not etiquette. That’s a psychology experiment wearing a payment terminal’s clothes.

So, the actual solution: decide your own policy in advance, before you’re standing there with a line behind you and a cashier definitely not watching your screen nearly as closely as you assume they are.

A reasonable, defensible line is to tip when something was genuinely made for you — a latte someone actually steamed and poured, a sandwich someone built — and to skip it, guilt-free, for something that was just handed to you, like a bottled drink or a bag of chips rung up at a register.

Hit “custom amount,” type in zero, and move on with your day. The moment of awkwardness lasts about two seconds and is forgotten by literally everyone else in that line before they’ve even reached the counter.

A tablet prompting you is a business choice, not a social contract. You’re allowed to treat it as optional, because it is.

🏨 Hotels: An Easy Category to Forget Entirely

Housekeeping is worth a few dollars a day, left directly in the room — in cash, and clearly marked (a small envelope, a note that says “thank you”) so it doesn’t get mistaken for money someone accidentally left behind and skipped entirely.

This is genuinely easy to forget, since unlike a server, housekeeping staff are rarely standing there for you to hand something to directly. Nobody’s going to chase you down about it.

That’s exactly why it’s worth building the habit of leaving it before you check out, not after you’re already in the elevator wondering if you should have.

🎯 The General Principle Underneath All of This

Tipping norms genuinely vary by service type, by region, and sometimes by the individual business you happen to be standing in.

When you’re truly unsure, a quick, discreet search for “tipping norms for [specific situation]” settles most uncertainty faster than the anxious math Marty was doing in that coffee line.

And here’s the part worth actually believing: nobody has ever once been offended by a guest who clearly put a little thought into it — whichever way that thought landed.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

54007

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
What a Credit Score Actually Measures

A credit score sounds like a mysterious verdict handed down from on high. It’s really just a report card for one very specific behavior.

Marty has heard the phrase “good credit score” roughly a thousand times in his life, has a general sense that a higher number is better, and could not, if put on the spot, explain what a credit score is actually measuring — good at what, exactly? Being a nice person? Showing up on time? He genuinely didn’t know.

🎯 What It’s Actually Measuring: One Thing

A credit score is a three-digit number, typically ranging from 300 to 850, that predicts one specific thing: how likely you are to repay borrowed money on time, based entirely on your past history of borrowing and repaying.

It’s not a measure of income, net worth, intelligence, or general trustworthiness as a human being — purely and only a track record of debt behavior.

🧮 The Five Ingredients, and Roughly How Much Each One Weighs

Your credit score is determined by these five factors:

  • Payment history (do you pay on time) is the single biggest factor, roughly 35% of the score.
  • Credit utilization (how much of your available credit you’re actually using, covered in its own post) is next, around 30%.
  • Length of credit history — how long you’ve had credit accounts open — makes up about 15%.
  • The mix of credit types you have (credit cards, loans, etc.) contributes about 10%.
  • And new credit inquiries — how often you’ve recently applied for new credit — rounds out the last 10%.

📊 What the Actual Ranges Mean

Roughly speaking, these are the credit range rankings:

  • 800-850 is considered exceptional
  • 740-799 very good
  • 670-739 good
  • 580-669 fair
  • below 580 poor

Lenders use these ranges to decide not just whether to approve you, but what interest rate to actually offer — a real, dollars-and-cents difference, not just a bragging-rights number.

🎢 Interest Rates: The Price of Being a Mystery

Here’s the part that last section undersells: that number doesn’t just decide whether you get approved. It decides how much the approval actually costs you.

Every loan and card comes with an interest rate attached — basically a rental fee for borrowing someone else’s money. Lenders don’t hand that fee out equally. A high score says “this person pays reliably, historically, boringly” and earns a better rate. A low score, or no score at all, says “no idea, never met this person” — and lenders protect themselves from that uncertainty the only way they know how: by charging more, just in case.

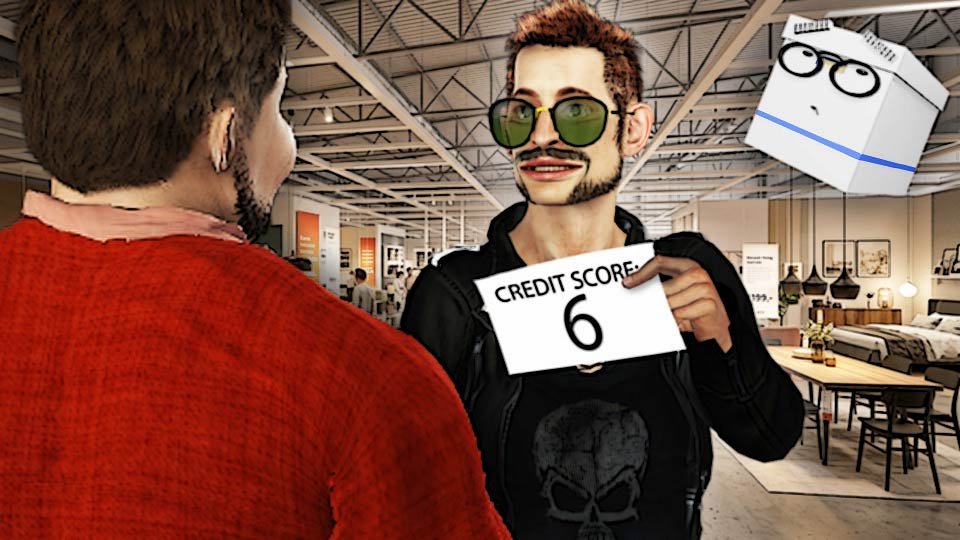
The gap adds up fast, too. Same car, same dealership, same day: the guy with a low credit score might be looking at $785 a month, while the guy with excellent credit drives off in the identical car for as little as $550. Same loan. Different mystery level. Different price tag every single month for the next five years.

So the number isn’t a report card. It’s a discount code, earned one on-time payment at a time — and the alternative is paying full price for being a stranger.

👻 The Myth Worth Killing Immediately

Checking your own credit score does not lower it.

This is one of the most persistent, wrong beliefs out there, and it keeps people from looking at a number that genuinely affects their financial life.

Checking your own score is called a “soft inquiry” and has zero impact — it’s only when a lender checks your credit as part of an actual application (a “hard inquiry”) that it can cause a small, temporary dip.

🆓 How to Actually Check It, for Free

Many credit card companies and banks now offer free credit score access right inside their app.

Sites like AnnualCreditReport.com provide free access to your full credit report (a different, more detailed document than just the score) once a year from each of the three major bureaus.

There’s no good reason to pay a monthly fee just to see a number you’re entitled to check for free.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52010

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved
Secured vs. Unsecured Credit Cards: Which One You Actually Need

One of these cards asks for a deposit before it trusts you with credit. That’s not a punishment — it’s actually a smart starting move.

Alexa applied for a regular credit card, got denied for having “insufficient credit history,” and felt the specific, circular frustration of being told she needed credit history to get credit, with no apparent door leading in. There’s a door. It’s just a slightly different one than she was knocking on.

🛋️ Secured vs. Unsecured: What’s the Difference?

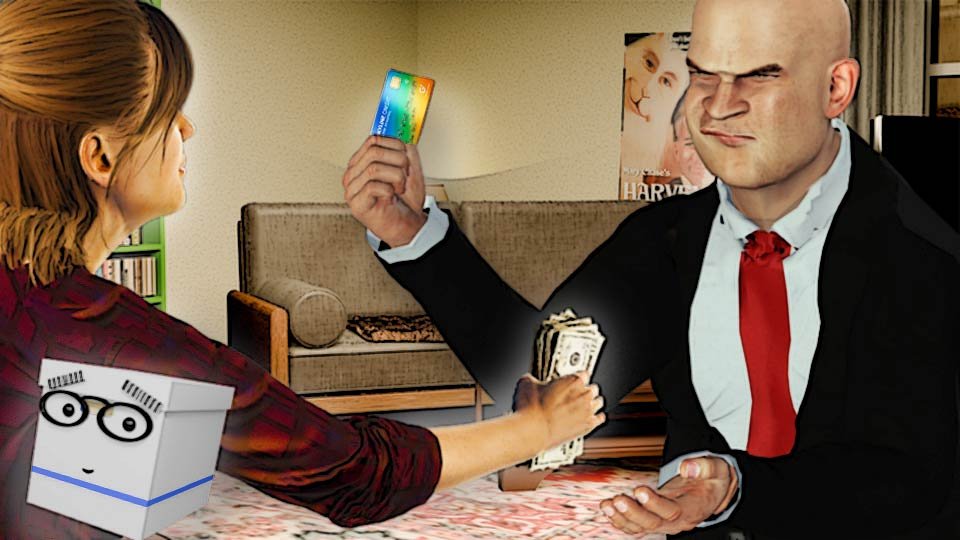
Picture two strangers who show up at your door on the same afternoon, both wanting to borrow $300, both with an honest face and a suspiciously specific repayment plan.

The first guy hands you a driver’s license, shakes your hand, and promises to pay you back $27.50 a month for the next twelve months — $330 total, meaning you walk away $30 richer for helping him out. Nice guy. You believe him. You have, however, no actual leverage beyond his word and a mild sense that he seemed trustworthy.

The second guy wants to buy your couch, also for $300, and offers the exact same deal — $27.50 a month for a year. Except he takes the couch home with him today, right now, sofa cushions and all, on nothing but that same promise to pay.

Here’s the entire difference in one sentence: if guy number two stops paying, you know exactly where your couch is, and you’re legally entitled to go get it back. If guy number one stops paying, you’ve got a phone number, a memory of a firm handshake, and absolutely nothing else.

That’s secured versus unsecured credit in a nutshell. A secured line is backed by real, repossessable property — the couch, a car, a house. An unsecured line is backed by nothing but your word that you’ll pay it back, which is exactly why lenders charge more interest for it and check your credit history more carefully before handing it over. Collateral isn’t a technicality. It’s the entire reason one of these guys sleeps easier than the other.

🔓 Unsecured: The “Normal” Credit Card

An unsecured credit card is what most people picture when they think of a “credit card” — no deposit required, the credit limit is based purely on the bank’s assessment of your creditworthiness.

The catch: banks and credit card companies typically require an existing credit history before they’ll approve you for one in the first place — which is exactly the wall Alexa ran into.

The second catch: because they’re lending you money on nothing but your word, banks and credit card companies usually charge a higher interest rate on that line of credit than they would on a secured one.

🔒 Secured: The Same Card, With a Deposit Attached

A secured credit card requires a refundable security deposit upfront — commonly matching your credit limit, so a $300 deposit gets you a $300 limit.

That deposit is the bank’s insurance policy against someone with no track record yet — not a punishment, just how a bank manages risk with an unknown quantity.

It’s the same idea as the couch. If you don’t pay, the bank keeps your $300 — the equivalent of you collecting the couch.

🪜 Why Secured Cards Are Genuinely the Smart Starting Move

A secured card reports to the credit bureaus exactly the same way an unsecured one does — on-time payments build real credit history either way.

It’s specifically designed as a stepping stone: use it responsibly for a while, and many issuers will actually convert it to an unsecured card automatically, refunding your original deposit once they do.

The downside: you have to come up with $300 first.

Now, you’re not paying a $300 fee that just vanishes. You’ll get that money back eventually, and in the meantime it’s sitting there as your actual credit limit, doing its job.

And it’s available to you on your new credit card – you’ll most likely have at least a $300 credit limit. Use the card to buy your groceries and stuff, just paying off the card at the end of the month.

But you do need to have that $300 up front.

💵 What Happens to the Deposit

As long as the account stays in good standing, the deposit isn’t a fee — it’s held, and returned to you either when the card converts to unsecured or when you close the account with no outstanding balance.

It’s genuinely your money the entire time, just serving as collateral rather than sitting in a regular savings account.

🎯 The Actual Decision

If you have zero credit history, a secured card is very often the realistic starting point, not a lesser option — plenty of people with excellent credit today started on exactly this kind of card.

If you already have some credit history through another route (a co-signed account, a student loan, being an authorized user on a parent’s card), you may already qualify for unsecured directly.

🔗 Related Reads


ScrumbleDoc is part of the WhistleBump Group — find the rest of the family at WhistleBump.com.

52004

©2026 John D Reinhart/ScrumbleDoc.com — All rights reserved